
Sep
Financial Planning for Bloomfield Hills Business Owners
Your business is likely your most significant asset, yet it’s often the one least integrated into your personal estate strategy. Most entrepreneurs find themselves managing a fragmented collection of advice from tax, legal, and investment professionals who rarely speak the same language. This lack of coordination doesn’t just create administrative friction; it creates significant tax liabilities that erode both corporate profits and personal wealth. Integrating financial planning for business owners requires a partner who understands that your corporate success and personal legacy are fundamentally linked.
Strategic growth demands clarity. It’s natural to feel uncertain about succession timing or how to protect your life’s work from shifting tax brackets. In this guide, Timothy Roberts & Associates, LLC will demonstrate how a fractional CFO perspective can unify your financial life into a single, cohesive roadmap. We will explore methods to minimize tax exposure, optimize your business for an eventual exit, and establish a clear path toward a work-optional lifestyle. By the end, you’ll understand how to secure your legacy through intentional, high-level coordination that respects both your creative vision and your financial requirements.
Key Takeaways
- Synthesize corporate strategy with personal wealth management to eliminate the coordination gaps that often dilute entrepreneurial success.
- Discover how a fractional CFO approach redefines financial planning for business owners bloomfield hills by prioritizing long-term business value over simple portfolio management.
- Identify the essential benchmarks for a high-net-worth advisor; focusing on the critical intersection of fiduciary responsibility and proactive tax coordination.
- Move beyond the “sale as retirement” myth by implementing sophisticated continuity tools that protect both your business operations and your family’s future.
The Strategic Intersection of Personal Wealth and Business Value
For most entrepreneurs, the business represents more than a career; it’s the primary engine of wealth. This creates a unique burden. While your peers might maintain diversified portfolios, your net worth is likely concentrated in a single, illiquid entity. This concentration creates a precarious balance where the success of the enterprise dictates the security of your family. Effective financial planning for business owners bloomfield hills must address this concentration risk by treating the business as a strategic asset that must eventually be harvested rather than just a source of annual income.
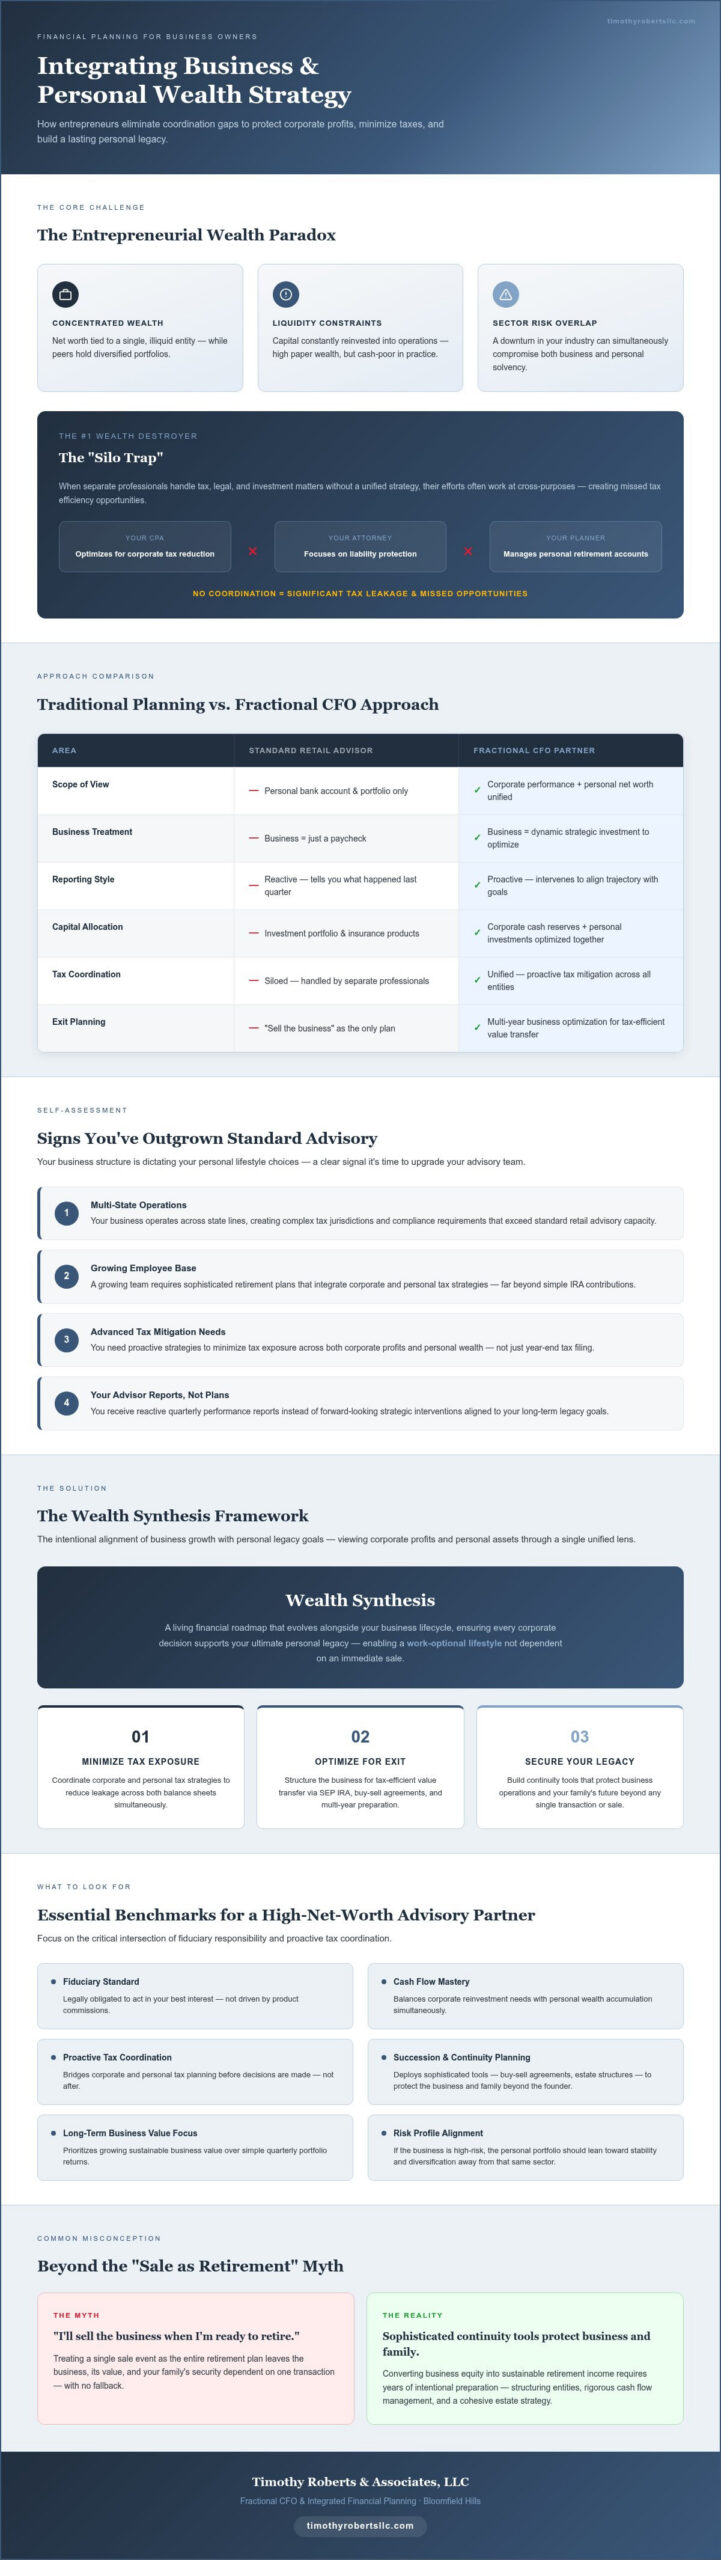
Many owners fall into the “Silo Trap.” This occurs when separate professionals handle tax, legal, and investment matters without a unified strategy. Your CPA might optimize for corporate tax reduction, while your attorney focuses on liability, and your financial planner looks at personal retirement accounts. Without coordination, these efforts often work at cross-purposes, leading to missed opportunities for tax efficiency. True stability requires a living financial roadmap that evolves alongside your business lifecycle, ensuring every corporate decision supports your ultimate personal legacy.
The Entrepreneurial Wealth Paradox
Success often brings high paper wealth paired with significant liquidity constraints. You might lead a multi-million dollar firm yet find yourself cash-poor because capital is constantly reinvested into operations. Your personal investment profile must account for this imbalance. If your business operates in a high-risk sector, your personal portfolio should lean toward stability and diversification away from that specific industry. Balancing these risk profiles ensures a downturn in your sector doesn’t simultaneously compromise your personal solvency.
Bridging the Gap Between Balance Sheets
Converting business equity into a sustainable retirement income requires years of intentional preparation. It isn’t enough to simply grow the top line. You must structure the business to facilitate a tax-efficient transfer of value through entities like a SEP IRA or a structured buy-sell agreement. This involves rigorous cash flow management that balances the need for corporate reinvestment with the necessity of personal wealth accumulation. Wealth Synthesis is the intentional alignment of business growth with personal legacy goals. Viewing corporate profits and personal assets through a single lens allows for a work-optional lifestyle that isn’t dependent on an immediate sale.
Evaluating Fractional CFO Services vs. Traditional Financial Planning
Traditional financial planning often stops at the edge of your personal bank account. For the entrepreneur, this boundary is artificial. A Fractional CFO approach integrates corporate performance with personal net worth, treating your business as a dynamic investment rather than just a paycheck. While traditional advisors manage what you’ve already earned, a strategic partner helps you optimize how you earn it and how you keep it. This distinction is vital for effective financial planning for business owners bloomfield hills, where the complexity of the business often exceeds the scope of retail advisory services.
Standard retail advisors typically focus on investment portfolio management and insurance. While these are necessary components, they don’t address the operational drivers of your wealth. A fiduciary partner with a CFO mindset provides strategic oversight of capital allocation, ensuring that your corporate cash reserves are working as hard as your personal investments. This level of coordination is the hallmark of high-level financial planning for business owners bloomfield hills, moving beyond simple asset allocation into the realm of organizational evolution.
When to Move Beyond Standard Advisory
You’ve likely outgrown a standard retail financial advisor when your business structure begins to dictate your personal lifestyle choices. Complexity often manifests through multi-state operations, a growing employee base requiring sophisticated retirement plans, or the need for advanced tax mitigation. Standard advisors often provide reactive reporting; they tell you what happened last quarter. In contrast, Timothy Roberts & Associates, LLC offers a proactive intervention, aligning your corporate trajectory with your long-term legacy goals.
The Fractional CFO Advantage for Growth
The true value of a CFO-level advisor lies in identifying blind spots within your corporate structure that threaten your personal wealth. This includes auditing debt management and capital expenditures to ensure they align with your eventual exit strategy. Effective business tax planning strategies are not just about filing returns; they’re about structuring your firm to minimize liabilities years before a sale. A visionary strategist evaluates how every dollar spent inside the business impacts the valuation you’ll eventually harvest. This oversight ensures that when you finally decide to step away, the value you’ve built is fully realizable and protected from unnecessary erosion. If you’re ready to see how a unified strategy can accelerate your progress, exploring a comprehensive wealth assessment is a logical next step.
Key Criteria for Selecting a High-Net-Worth Advisory Partner
Selecting a partner to oversee your life’s work requires a rigorous vetting process that goes beyond surface-level certifications. High-net-worth individuals often find that generic filter tools don’t account for the unique complexities of business ownership. Effective financial planning for business owners bloomfield hills must be anchored in a framework of transparency, independent ownership, and deep technical expertise. You aren’t just looking for someone to manage a portfolio; you’re seeking a visionary strategist who can navigate the nuances of corporate structures and personal legacy with equal precision.
The structure of your advisory relationship is just as important as the advice itself. While asset-based fees are standard for ongoing management, complex planning projects such as business valuations or exit preparation may benefit from fixed-fee arrangements that reflect the intensive nature of the work. This flexibility ensures that the advisor’s incentives are aligned with the project’s success rather than just the size of the managed account. A multi-generational perspective is also essential, as it ensures your estate and legacy planning accounts for the long-term stewardship of the wealth you’ve created.
The Fiduciary Standard for Business Owners
The fiduciary standard isn’t a marketing buzzword; it’s a legal obligation to put your interests first. For entrepreneurs, this “Best Interest” baseline is the only acceptable standard, as it removes the conflicts of interest often found in insurance or proprietary product sales. When you research how to choose a financial advisor, prioritize those with documented experience in business exits and succession. Ask prospective partners how they’ve handled complex liquidity events in the past and how they coordinate with legal teams to protect client assets during a transition.
Integrated Tax Preparation and Strategy
Relying on a separate CPA and financial advisor often leads to missed opportunities in capital gains management and income timing. True wealth elevation happens when your tax advising is woven directly into your investment strategy. This year-round approach allows for proactive adjustments rather than reactive seasonal filing. Tax-efficient portfolio management can increase net-of-tax returns for business owners by strategically timing the realization of gains and losses to coincide with your business’s fluctuating income cycles. This level of coordination ensures that your financial planning for business owners bloomfield hills is truly optimized, keeping more of your hard-earned capital working for your future goals.
Strategic Tax and Estate Coordination for the Entrepreneur
The most common retirement strategy for entrepreneurs is also the most precarious: the assumption that a future business sale will fund their entire lifestyle. Relying solely on a liquidity event ignores the realities of market timing, valuation shifts, and the potential for unforeseen health events. Financial planning for business owners bloomfield hills must move beyond this singular hope by building a resilient framework that harvests value throughout the business lifecycle. A strategic exit is a choice, not a necessity, when your personal balance sheet is decoupled from your corporate operations.
A properly structured buy-sell agreement serves as more than a legal contingency; it’s a vital estate planning tool. It ensures that your family receives fair market value for your interest without being forced into active management. When coordinated with a series of trusts, these agreements shield your business assets from personal liabilities and ensure corporate control remains with those best equipped to lead. This synthesis of corporate governing documents and personal wealth protection creates a fortress around your legacy.
Succession Planning as Wealth Management
Transitioning a business involves more than finding a successor; it requires a deep analysis of tax and income implications. Internal transitions to family or employees often provide continuity but may require creative funding strategies like using corporate cash flow or insurance to facilitate a buyout. Conversely, external sales often provide immediate liquidity but come with significant capital gains liabilities. You must ensure your retirement income stream isn’t entirely dependent on the new owner’s success. Diversifying your wealth into an investment portfolio management strategy while still at the helm provides the stability needed for a smooth transition.
Legacy and Estate Protection
As we approach the 2026 sunset of current tax provisions, the urgency for sophisticated estate planning has never been higher. High-earners may face a reversion to the 39.6% top marginal rate and a significant reduction in estate tax exemptions. Proactive coordination between your corporate structure and your personal estate plan allows for charitable giving strategies that provide immediate corporate deductions while fulfilling your personal philanthropic goals. Regular reviews of these structures are mandatory to ensure your legacy remains intact as the regulatory environment evolves. If you haven’t reviewed your succession strategy in the last eighteen months, it’s time to schedule a strategic legacy audit to protect what you’ve built.
Elevating Your Business Legacy with Timothy Roberts & Associates
Your business is a masterpiece of effort and ingenuity. It shouldn’t be left to chance or fragmented advice. We believe that true wealth isn’t just about the numbers on a balance sheet; it’s about the freedom those numbers provide. Timothy Roberts & Associates positions itself as the visionary strategist for the growth-minded owner who demands more than a generic retail experience. By synthesizing high-level investment portfolio management with sophisticated tax advising, we ensure your corporate success fuels your personal legacy. This is the essence of intentional financial planning for business owners bloomfield hills.
A Partnership Built on Experience and Rigor
For over 25 years, our firm has operated with a steadfast commitment to fiduciary excellence. We don’t just report on your assets; we handle the heavy lifting of financial coordination so you can focus on your firm’s evolution. Managing the wealth of a business owner requires a specialized rigor that traditional firms often lack. We bridge the gap between your corporate capabilities and your personal creative vision, offering a single, authoritative point of coordination. This partnership provides the peace of mind that comes from knowing every strategic lever is being pulled in your favor. Our focus remains on your upward progression, treating your development as a journey of shared success rather than a series of transactions.
Your Next Step Toward Strategic Evolution
The transition from fragmented advice to a unified financial roadmap begins with a conversation about your “Ideal Tomorrow.” We don’t start with your current assets; we start with your vision for the future. Our initial dialogue focuses on the qualitative aspects of your success. We want to understand what a work-optional lifestyle looks like for you and how your business serves that end. From there, we work backward to the technical execution. This process moves you away from the “Silo Trap” and toward a cohesive, actionable plan. You’ll gain a clear understanding of how your tax liabilities, investment risk, and succession timing all intersect.
This high-level intervention is designed for those who value depth and personal attention over superficial solutions. During an initial strategic consultation, we’ll explore how your business value can be optimized to support your long-term goals. This isn’t a sales pitch; it’s a deep dive into the practicalities of execution, moving you toward a state of clarity and confidence. If you’re ready to evolve your strategy and secure your business legacy, Schedule a consultation with Timothy Roberts & Associates today. We’ll help you navigate the complexities of financial planning for business owners bloomfield hills with the precision your life’s work deserves.
Securing Your Strategic Evolution
The journey from operational success to a lasting legacy requires more than simple asset management. It demands a sophisticated synthesis of your corporate strategy and personal wealth. By adopting a fractional CFO lens, you move beyond fragmented advice and toward a unified roadmap. This proactive approach ensures your business remains your greatest asset rather than a source of uncertainty. Integrating financial planning for business owners bloomfield hills with expert tax coordination allows you to protect your profits and your personal future simultaneously.
Timothy Roberts & Associates brings over 25 years of fiduciary advisory experience to this partnership. As members of a sophisticated national network of advisors, we provide the high-level rigor necessary to handle the coordination of your complex financial life. Our integrated tax preparation and wealth management services ensure every strategic lever is pulled in favor of your “Ideal Tomorrow.” It’s time to transition from managing complexity to leading a visionary strategy. Elevate your business and personal wealth strategy; schedule a consultation today. Your legacy deserves the precision of a craftsman and the foresight of a strategist.
Frequently Asked Questions
What is the difference between a financial planner and a fractional CFO for a business owner?
A traditional financial planner primarily focuses on personal assets and retirement accounts. In contrast, a fractional CFO views the business as a strategic engine for wealth. They coordinate corporate cash flow, capital allocation, and debt management to maximize the firm’s valuation. This level of oversight ensures the business isn’t just a place of work but a liquid asset ready for a future transition that supports your personal legacy.
How can integrated tax planning help me keep more of my business profits?
Integrated tax planning ensures your investment choices and business decisions work together to reduce your total liability. When tax preparation is linked to your wealth strategy, you can time the realization of capital gains or business income to hit lower brackets. This holistic approach prevents the “silo trap” where separate advisors miss opportunities to harvest losses or defer income, keeping more profit available for reinvestment or personal wealth accumulation.
Why do business owners need a different type of retirement income planning?
Entrepreneurs often possess high paper wealth but lack the immediate liquidity found in traditional employment. Retirement income planning for business owners requires a specific strategy to convert illiquid business equity into a sustainable cash stream. It involves balancing corporate distributions with diversified portfolios to ensure you aren’t solely dependent on the performance of a single company or industry during your work-optional years. This approach prioritizes long-term stability over short-term gains.
What happens to my personal wealth if I don’t have a business succession plan?
Without a succession plan, your personal wealth is highly vulnerable to market volatility and forced liquidations. An unplanned exit often leads to a significant loss in business valuation and massive tax hits that erode your estate. Strategic financial planning for business owners bloomfield hills mitigates these risks by establishing buy-sell agreements and continuity plans. These tools protect your family’s financial security and ensure your life’s work isn’t dismantled by unforeseen operational changes.
How does a fiduciary advisor specifically benefit an entrepreneur?
A fiduciary advisor is legally obligated to act in your best interest, which is critical when navigating complex corporate structures. For an entrepreneur, this means receiving objective advice on risk management and retirement plans without the conflict of interest found in commission-based sales. This transparency is vital for long-term trust, especially when coordinating high-stakes decisions like business valuations, tax-efficient distributions, or multi-generational wealth transfers that require a steady, unbiased hand.
Can I coordinate my business exit strategy with my personal estate plan?
Coordination between your exit strategy and personal estate plan is essential for preserving your legacy. Your exit strategy should dictate how and when business assets flow into your personal estate, often using trusts to minimize tax exposure. By aligning corporate governing documents with your personal estate goals, you ensure a seamless transition of control and capital. This intentional synthesis protects your family’s future while respecting the creative vision you’ve built within the firm.
What are the tax implications of selling my business in 2026?
The year 2026 marks a significant shift as current tax provisions are scheduled to sunset. High-earners may face higher marginal rates and a reduction in estate tax exemptions, making the timing of a business sale critical. Proactive financial planning for business owners bloomfield hills involves analyzing these upcoming changes now to structure your exit. This preparation ensures you minimize the impact of potential regulatory shifts while maximizing the net-of-tax value you eventually harvest.
Why is a fixed-fee financial planning model often better for complex business needs?
A fixed-fee model provides transparency and aligns the advisor’s work with the complexity of your needs rather than just account size. For business owners, this is ideal for intensive tasks like estate coordination or retirement strategy development. It ensures you receive dedicated, project-based analysis without the distractions of asset-based incentives. This model allows for a more focused and intentional approach to solving your firm’s unique financial problems while maintaining professional stability and clarity.
