A familiar stock can become the biggest risk in a portfolio. Advisors commonly consider a position above 10% of investable assets concentrated, and strategies for diversifying out of a single stock holding can include staged sales, reinvestment, and tax-aware planning.
Selling shares can reduce reliance on one company, but it may also trigger capital gains taxes. That tradeoff can make a gradual approach worth considering, especially if the shares have appreciated substantially.
This guide explains how to assess concentration risk, compare gradual diversification with the potential step-up in basis at death, and choose an approach that fits your time horizon and broader financial goals. It also covers how a coordinated financial plan can address tax exposure and align your portfolio with the future you want it to support.
Key Takeaways
- Assess how much of your portfolio depends on one company and how that exposure fits your broader financial goals.
- Compare gradual sales and reinvestment with alternatives such as exchange funds, including their tradeoffs and time commitments.
- Plan sales around potential capital gains taxes, available portfolio losses, and the pace at which you want to reduce concentration.
- Weigh the benefits of diversifying during your lifetime against the possible step-up in basis at death in light of your estate and legacy plans.
1. What Is a Concentrated Stock Position?
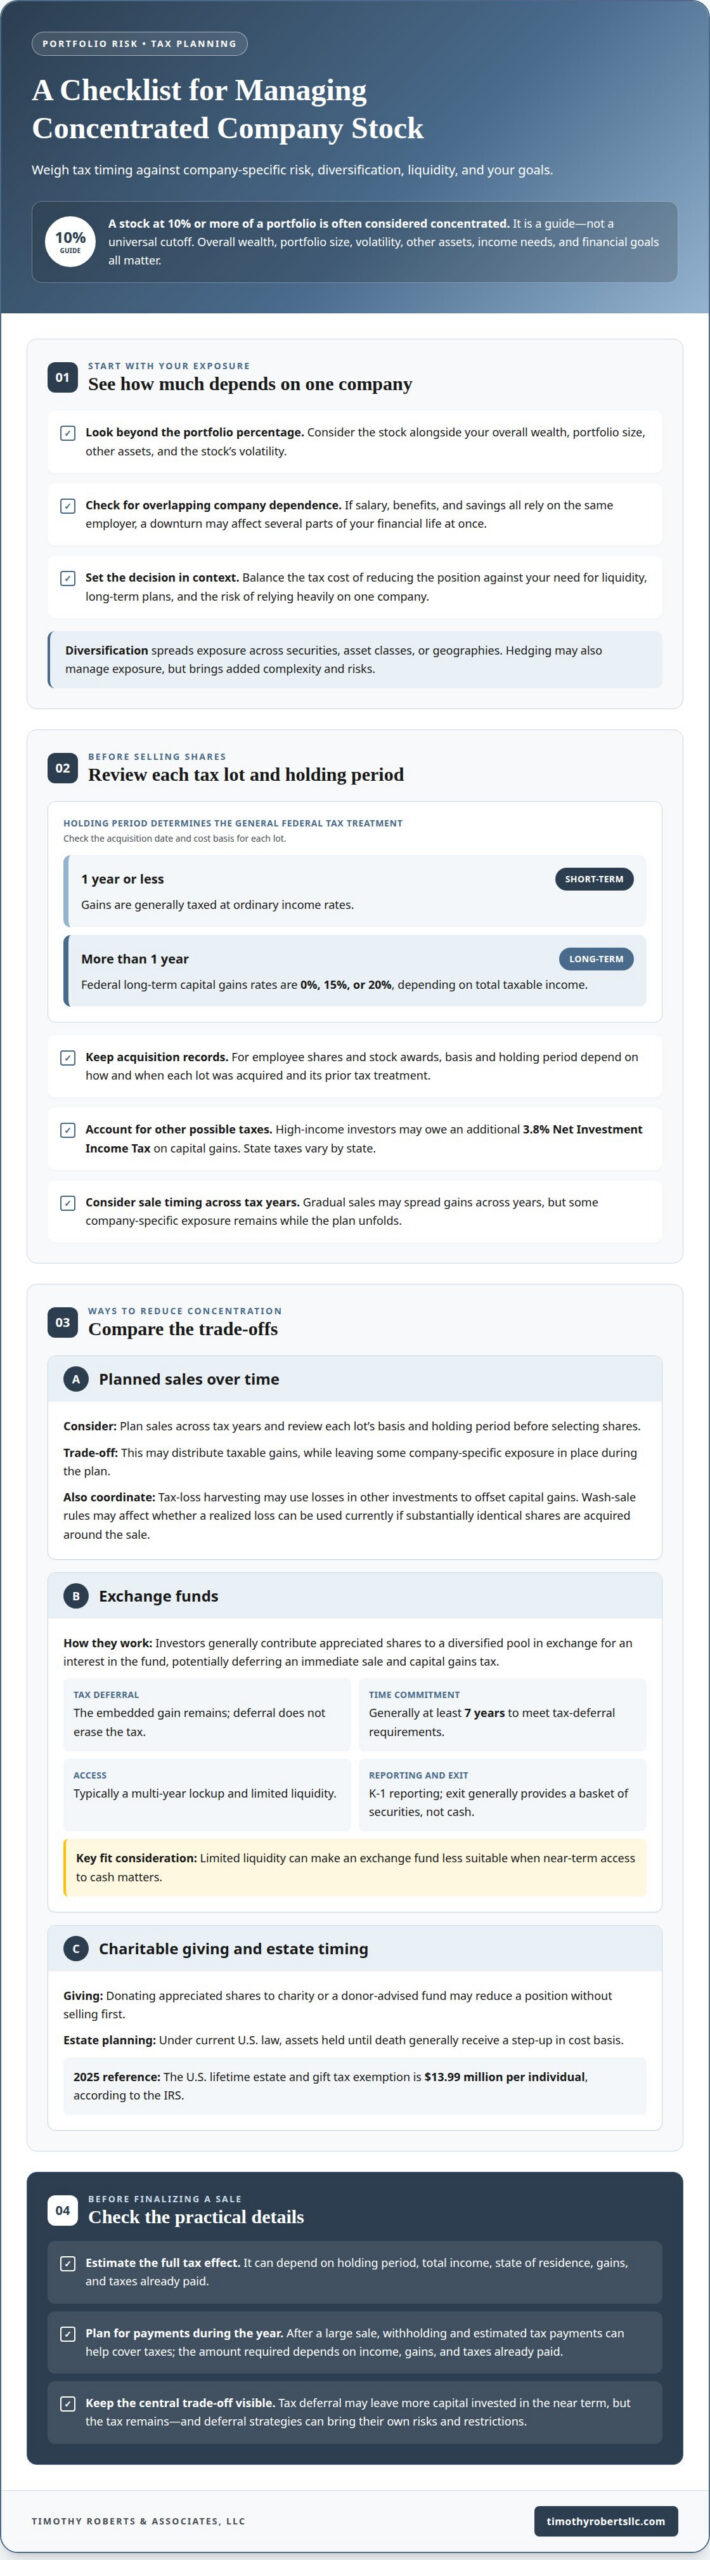
A concentrated stock position is a holding in one company that dominates an investor’s portfolio. Advisors commonly define a position above 10% of investable assets as concentrated. Even a holding around 5% can create unwanted risk when other investments share its industry or economic drivers. The full exposure matters, including shares held through funds or workplace plans.
An exchange fund is one way to exchange eligible shares for an interest in a diversified pool of securities. Investors contribute stock, and the fund combines holdings into a broader portfolio. This can reduce single-company exposure without immediate tax consequences, but it requires a long commitment. The IRS requires investors to hold an exchange fund for at least 7 years to receive a basket of securities. The period can limit liquidity, and exiting within the first 3 years may trigger a 1% fee.
Entry requirements also shape whether an exchange fund is practical. Qualified-investor access is described for investors with at least $5 million in investable assets; eligibility commonly also cites net worth of at least $1 million, excluding a primary residence. These thresholds are distinct from the fund’s minimum investment, so both affect access. Fund terms determine how distributions work and when investors can receive securities; the long holding period means this is not a ready source of cash.
Employer stock can add trading constraints. Insider trading rules and company blackout periods may limit when employees can trade, so sales may need to fit within permitted windows. A financial planner can help map your exposure, consider tax consequences, and develop a staged schedule that reflects your goals.
Donating appreciated shares can reduce a concentrated holding while supporting charitable goals. Donor-advised funds and charitable remainder trusts may offer flexibility and potential tax advantages. The right option depends on your charitable intentions, income needs, and estate plans.
Before a major sale, exchange, or gift, consider how the decision could affect liquidity, taxes, and your portfolio’s intended risk level. When employer trading restrictions, capital gains, or estate decisions overlap, coordinate financial planning with advice from a tax professional.
2. Assessing concentrated-stock risk
A portfolio can look diversified while still depending heavily on one company. Measure the stock position against total investable assets, then examine indirect exposure through funds, workplace plans, and related holdings. A broad index fund may own the same large-cap company, adding exposure rather than offsetting it. The Russell 1000 and S&P 500 can provide useful comparison points, but neither removes company-specific risk.
Historical figures show why concentration deserves careful attention. Since 2014, individual Russell 1000 stocks averaged 37% annual volatility, compared with 15% for the index. The average stock’s maximum decline was 50%, while the index’s maximum drop was 25%. Also since 2014, 85% of those stocks experienced a larger decline than the index. These figures describe past periods, not a forecast for any particular holding.
A completion portfolio is designed around the concentrated holding. Rather than buying a standard mix that may repeat the same exposure, a planner shapes the remaining investments to complement it. The allocation can account for sector exposure, time horizon, income needs, liquidity, and tolerance for loss. Modeling how holdings work together can help establish a suitable reduction target and connect portfolio decisions to your broader goals.
Selling can reduce exposure quickly, but capital gains may affect how much you sell and when. Staged sales can spread transactions over time, while tax losses elsewhere in the portfolio may help offset gains. A planner can compare these options with reducing concentration through new investments, taking account of cash needs and the risks of remaining exposed. If the shares come from employer compensation, the plan should also account for permitted trading windows.
Discuss concentration when one company’s performance could materially alter a financial plan, or when liquidity needs and tax decisions are approaching. A tailored portfolio risk assessment can bring exposure, allocation, and sale timing into one decision framework. That makes the tradeoffs visible before a transaction changes the portfolio.

3. Gradual stock sales and reinvestment
A gradual plan turns a large holding into a sequence of deliberate portfolio decisions. An investment advisor can model sale amounts, timing, and reinvestment so the remaining shares fit the investor’s target allocation. Gradual diversification through sales and broad-market reinvestment is best suited to investors with at least a 10-year horizon. Among strategies for diversifying out of a single stock holding, staged sales suit investors who can accept continued exposure while the plan unfolds.
Before setting a schedule, an advisor reviews the holding’s cost basis, expected cash needs, other equity exposure, and tax situation. A tax professional can help model sales across tax years and evaluate how gains interact with available losses. The IRS says unused tax-loss-harvesting losses carry forward at $3,000 per year. Such losses may offset gains, but the plan should account for sale timing and the investor’s wider tax picture.
Executives may also use a 10b5-1 plan to map out share amounts and price limits for trades over time. This can structure planned sales, while company trading restrictions and blackout periods still affect transaction timing. An advisor coordinates the schedule with reinvestment decisions, directing proceeds toward assets that reduce overlap and support the portfolio’s intended balance.
Gradual selling can spread transactions over time and preserve flexibility, but it leaves you exposed to the stock’s performance during the sale period. Selling all at once reduces that exposure sooner, but may concentrate gains in one tax year and require reinvesting the proceeds at once. The right strategies for diversifying out of a single stock holding depend on tax consequences, liquidity needs, your investment horizon, and how comfortable you are with continued concentration.
For a complex concentrated position, an advisor can revisit the plan as circumstances change. Reviews can adjust sale amounts, reinvestment choices, and potential loss offsets while keeping your long-term allocation in view.
4. Capital gains taxes and step-up in basis at death
Selling appreciated shares can create a capital gain, generally based on the difference between the sale proceeds and your cost basis. The tax impact depends on your basis, sale timing, and broader tax circumstances.
The potential tax bill can make lifetime diversification less attractive to investors focused on preserving wealth for heirs. A step-up in basis at death may change that comparison: inherited assets receive a basis adjustment that can reduce the taxable appreciation measured from the original purchase or vesting value. Exchange-fund shares passed to heirs also receive a step-up in basis.
Timing matters. Gradual sales can reduce concentrated positions while spreading gains across tax years, but they leave the remaining shares exposed to company-specific risk. For an investor closer to age 80, the potential step-up at death may weigh more heavily than immediate diversification. That is not a universal answer; expected income needs, portfolio risk, health, estate intentions, and the amount of appreciation all shape the decision.
Charitable giving offers another route for appreciated stock. Donating shares to a donor-advised fund or charitable remainder trust can support charitable goals, diversify assets, and provide flexibility with potential tax advantages. Gifts of stock to charitable organizations are typically fully deductible in the year of the gift, up to 30% of adjusted gross income. The right charitable structure depends on the investor’s giving goals and cash-flow needs.
Compare these paths together: sell and pay gains now, retain shares with potential basis treatment later, or donate appreciated stock for charitable purposes. A coordinated review of income needs, estate plans, and portfolio risk can clarify which tradeoffs matter most. Plan your stock and legacy strategy with those priorities in view.
Timothy Roberts & Associates
Timothy Roberts & Associates can help place a concentrated stock decision within a broader financial strategy. Its fiduciary advisors consider how portfolio exposure, potential capital gains, cash-flow needs, and legacy goals interact when developing a plan in your best interest.
Wealth & Investment Management can inform allocation and reinvestment decisions, while Financial Planning connects those choices to income needs and long-term priorities. Estate & Trust Planning can help frame the tradeoff between reducing risk during your lifetime and preserving assets for heirs. Insurance & Annuities can add another perspective on the role one holding plays in your overall financial picture.
Consider a coordinated review if you’re weighing staged sales, charitable giving, or retaining shares for potential step-up-in-basis treatment. Start by discussing your goals, existing holdings, and upcoming decisions with Timothy Roberts & Associates.
Shape Your Next Move With Intention
The next step is to make a complex holding decision fit your wider financial life. Before changing the position, clarify what you want the capital to support, how much liquidity you may need, and what role the remaining shares should play. These priorities can guide strategies for diversifying out of a single stock holding without treating the decision as a stand-alone trade.
Timothy Roberts & Associates, LLC can connect Investment Portfolio Management with Retirement Income Planning and Estate & Legacy Planning, bringing portfolio choices into conversation with future income and the legacy you want to shape. The aim is a considered path, not a rushed transaction. You can discuss the choices ahead and how they relate to your priorities with Start a conversation with Timothy Roberts & Associates, LLC.
A clear next step can make a concentrated position easier to approach. Move forward with a strategy grounded in your goals.
Frequently Asked Questions
What Is a Concentrated Stock Position?
A concentrated stock position is one in which a company’s shares make up a substantial portion of an investor’s assets. For example, an employee may hold company shares directly, through stock awards, and indirectly through a fund that owns the same company. Reviewing all these sources gives a clearer picture of exposure than looking at a brokerage account alone.
What are the risks of holding most of a portfolio in one stock?
Your portfolio’s value may become closely tied to one company’s results, leadership, industry, and prospects. A setback could affect both your investments and, if you work for the company, your income or future compensation. This overlap can limit financial flexibility, especially if you need to sell during a downturn or cover an upcoming expense.
What are the tax consequences of selling appreciated stock in the United States?
Selling appreciated shares can create a taxable capital gain, generally measured as the difference between the sale proceeds and the shares’ tax basis. How the gain is treated depends on factors such as the holding period and your overall tax circumstances. Reviewing purchase or vesting records before a sale helps clarify which shares you’re selling and their potential tax impact.
How can a financial advisor and tax professional help reduce capital gains taxes when diversifying stock holdings?
A financial advisor can coordinate sale timing, portfolio needs, and reinvestment, while a tax professional can evaluate the tax effects of specific transactions. Reviewing tax lots can help identify whether losses may offset gains and compare sales across tax years. For example, selling shares with different bases in separate transactions can change the realized gain and the portfolio’s remaining exposure.
How do exchange funds help diversify concentrated stock positions, and what are their costs and restrictions?
An exchange fund pools contributed stock into a diversified securities portfolio, potentially reducing exposure without immediate tax consequences. The required holding period is at least 7 years to receive a basket of securities; an exit within the first 3 years may incur a 1% fee.
Can investors use options or collars with professional guidance to manage risk in a concentrated stock position?
Yes. Protective puts, covered calls, and equity collars can help manage risk or generate income while you retain stock ownership. Each approach changes the position’s potential outcomes, so an advisor can assess how its terms interact with your risk tolerance, liquidity needs, and diversification timeline. Options don’t remove the underlying company exposure, and their structure matters.