
Sep
The Wealth Equilibrium: How Advisors Balance Growth and Risk as Assets Scale
At what point does the portfolio that built your success become the primary threat to your future security? For many high-net-worth individuals, the realization that generic investment models no longer apply to their tax bracket is both unsettling and inevitable. This transition marks a shift from aggressive accumulation toward an intentional evolution of wealth management. Understanding how financial advisors help balance growth and risk management as wealth increases is essential for those who have moved beyond standardized methodologies. It’s no longer just about picking winners; it’s about the sophisticated synthesis of tax efficiency and defensive preservation.
You likely feel that the stakes have changed and the margin for error has narrowed. This article reveals the strategic framework visionary stewards use to protect their lifestyle while still capturing purposeful market growth. We will explore the evolution of asset-based oversight, the necessity of tax-optimized structures, and the peace of mind that comes from a dedicated fiduciary partnership.
Key Takeaways
- Transition from simple accumulation to strategic preservation to ensure your wealth survives the transition between significant financial milestones.
- Explore how financial advisors help balance growth and risk management as wealth increases through the lens of modern portfolio theory and risk mitigation.
- Leverage tax efficiency as a primary driver of portfolio performance by synthesizing investment management with proactive tax preparation strategies.
- Establish a sophisticated wealth architecture by conducting a holistic asset audit and defining the minimum capital required to secure your lifestyle.
- Secure a fiduciary partnership that prioritizes personalized attention and strategic rigor over the standardized solutions of large institutions.
The Evolution of Wealth: Why Scaling Assets Demand a New Strategic Equilibrium
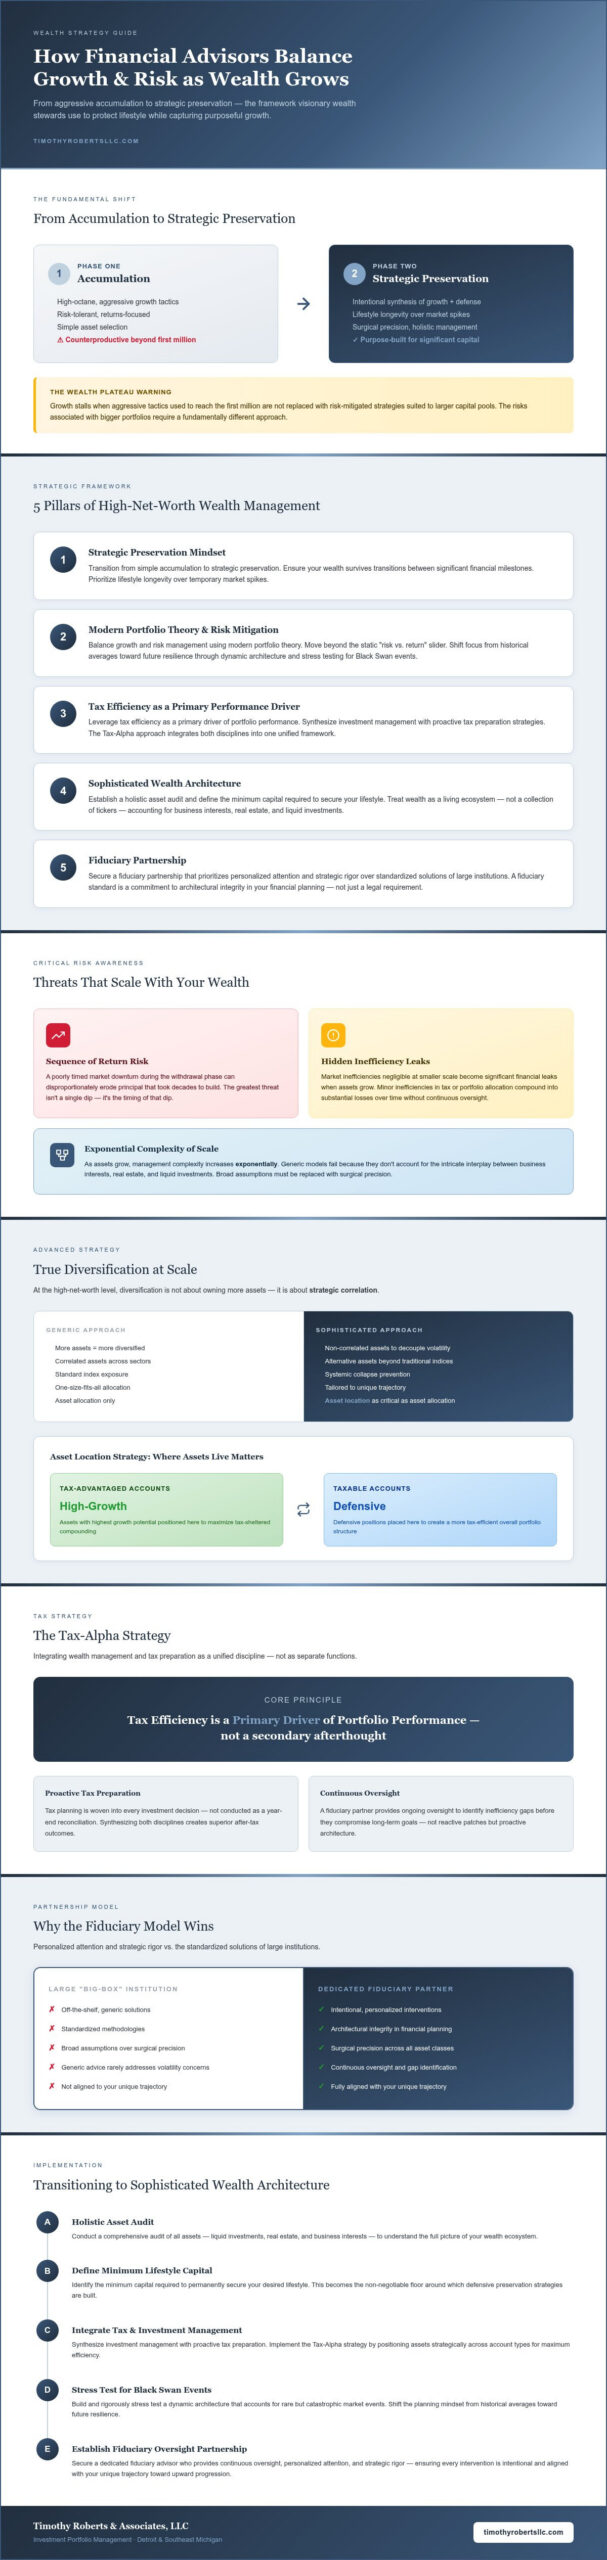
Building a substantial portfolio requires a different set of skills than maintaining one. Many investors find that the aggressive tactics used to reach their first million are counterproductive when aiming for their tenth. This realization often leads to the “Wealth Plateau,” where growth stalls because the risks associated with larger capital pools haven’t been properly mitigated. Professional wealth management moves beyond simple asset selection. It involves a fundamental shift in perspective. Understanding how financial advisors help balance growth and risk management as wealth increases is the first step toward long-term stability.
Passive management often feels safe, yet it carries hidden costs for high-net-worth individuals. When assets scale, market inefficiencies that were once negligible become significant leaks in your financial bucket. A fiduciary partner provides the continuous oversight necessary to identify these gaps before they compromise your long-term goals. Unlike off-the-shelf solutions found at big-box institutions, a personalized approach ensures that every intervention is intentional and aligned with your unique trajectory. This fiduciary standard isn’t just a legal requirement; it’s a commitment to architectural integrity in your financial planning.
Accumulation vs. Preservation: A Mindset Shift
Moving past the accumulation phase requires immense emotional discipline. It’s tempting to chase the same high-octane growth that built your initial capital, but significant portfolio fluctuations can be devastating when the numbers are larger. The fear of volatility eroding decades of effort is a valid concern that generic advice rarely addresses. Strategic Preservation is the intentional synthesis of growth and defense. This mindset shift allows you to move past the plateau with quiet ambition. It prioritizes the longevity of your lifestyle over the temporary thrill of a market spike, ensuring your success remains a permanent fixture.
The Complexity of Scale
As your assets grow, the complexity of managing them increases exponentially. Minor inefficiencies in tax or portfolio allocation can result in substantial losses over time. Generic models fail because they don’t account for the intricate interplay between business interests, real estate, and liquid investments. This is exactly how financial advisors help balance growth and risk management as wealth increases; they replace broad assumptions with surgical precision. You need an Investment Portfolio Management strategy from Timothy Roberts & Associates, LLC that treats your wealth as a living ecosystem rather than a collection of tickers. This level of customization ensures your growth remains purposeful and your downside is rigorously protected, allowing for a steady, logical progression.
Decoding the Paradox: Managing Market Risk Without Stifling Growth
Managing a substantial portfolio requires moving beyond the static “risk versus return” slider found in retail investing. For those with significant assets, the greatest threat isn’t a single market dip; it’s the Sequence of Return Risk. This silent predator strikes during withdrawal phases, where a poorly timed downturn can disproportionately erode the principal that took decades to build. Understanding investment risk and growth strategies involves more than just picking stocks. It requires a dynamic architecture that accounts for “Black Swan” events through rigorous stress testing. This is exactly how financial advisors help balance growth and risk management as wealth increases, by shifting the focus from historical averages toward future resilience.
The Science of Diversification at Scale
True diversification at a high-net-worth level isn’t achieved by simply owning more assets. It’s about strategic correlation. Advisors use non-correlated assets to decouple from broad market volatility, ensuring that a downturn in one sector doesn’t trigger a systemic collapse of the entire net worth. This approach often incorporates alternative assets that don’t move in lockstep with traditional indices. Additionally, asset location becomes as critical as asset allocation. Placing high-growth assets in tax-advantaged accounts while keeping defensive positions in taxable ones creates a more robust, tax-efficient structure that preserves capital while seeking upside.
Dynamic Rebalancing: The Fiduciary’s Watchful Eye
Standard, calendar-based rebalancing often misses critical market opportunities or fails to catch rapid declines before they impact the bottom line. A sophisticated approach utilizes threshold-based rebalancing, where interventions occur only when an asset class drifts beyond a predefined limit. This method requires continuous monitoring and a deep understanding of the client’s “floor,” the minimum assets required to maintain a lifestyle indefinitely. Integrating these triggers into Comprehensive Financial Plans is central to how financial advisors help balance growth and risk management as wealth increases, as it prevents lifestyle creep from quietly siphoning off portfolio health. It’s a proactive, rather than reactive, stance that preserves the strategic equilibrium. If you’re ready to move beyond generic advice, exploring a partnership with a fiduciary firm can provide the clarity your portfolio demands.
The Tax-Alpha Strategy: Integrating Wealth Management and Tax Preparation
For the high-net-worth investor, the most consistent source of outperformance isn’t found in market timing; it’s found in the tax code. This strategic focus is a pillar of how financial advisors help balance growth and risk management as wealth increases. By reducing the “tax drag” on a portfolio, advisors allow the principal to compound more efficiently without requiring higher volatility. Efficiency is the ultimate engine. If you keep a larger percentage of your returns, you don’t need to chase aggressive, high-risk growth to meet your financial objectives. This synthesis of tax preparation and investment management creates a predictable form of “alpha” that generic strategies simply cannot replicate.
Year-round coordination ensures that capital gains realized during portfolio rebalancing don’t create an unexpected liability that erodes your net-after-tax returns. Unlike generic firms that treat tax preparation as a separate business line, a sophisticated partner integrates these functions to identify surgical interventions. This proactive stance transforms tax planning from a seasonal chore into a continuous tool for wealth elevation.
Tax-Loss Harvesting as a Risk Mitigation Tool
Realizing losses isn’t a sign of failure; it’s a calculated move to offset gains. This lowers the tax hurdle for future growth, effectively acting as a defensive buffer during volatile periods. Precision matters here. This requires professional oversight to navigate complex regulations like the “Wash Sale” rule, which can easily trap the unwary. A structured approach to Tax Advising ensures these interventions remain compliant while maximizing your portfolio’s upward progression. It’s a method of continuous oversight that turns market downturns into strategic opportunities for long-term tax savings.
Estate Coordination and Legacy Planning
This long-term perspective is central to how financial advisors help balance growth and risk management as wealth increases. Legacy preservation requires protecting assets from excessive taxation during transfer. The transition of wealth is often where the most significant risks lie, not in the market itself, but in the lack of structural preparation. Strategic use of trusts and specialized vehicles creates a roadmap for multi-generational success, ensuring that your hard work isn’t diluted by avoidable liabilities. By integrating Estate Planning into the broader wealth management framework, you ensure the architecture of your success remains intact. A visionary strategist understands that estate coordination isn’t a one-time event but a journey of upward progression.
Implementation: Transitioning to a Sophisticated Wealth Architecture
Transitioning from a phase of rapid accumulation to one of strategic preservation requires more than a shift in mindset; it demands a technical overhaul of your financial structure. This implementation phase is where the vision becomes reality. Understanding how financial advisors help balance growth and risk management as wealth increases is best achieved through a four-step framework designed for the complexities of scale. This process replaces broad assumptions with surgical precision, ensuring every asset serves a distinct purpose within the larger ecosystem.
- Step 1: Conduct a holistic audit. This involves a deep dive into all assets, including business interests, private equity, and real estate holdings, to identify overlapping risks.
- Step 2: Define your ‘Floor’. Determine the exact minimum capital required to sustain your current lifestyle indefinitely, creating a psychological and financial safety net.
- Step 3: Establish a ‘Growth Bucket’. Allocate surplus capital here to capture long-term market upside, allowing for higher risk tolerance without jeopardizing your lifestyle.
- Step 4: Implement fiduciary-led monitoring. Continuous oversight ensures the architecture adjusts to legislative shifts and evolving market conditions in real time.
Auditing Your Current Risk Exposure
Many high-net-worth individuals unknowingly carry significant concentration risk in company stock or specific industrial sectors. This lack of diversification can lead to catastrophic losses if that specific sector faces a downturn. A neutral third-party audit is essential to uncover these vulnerabilities and expose hidden fees that quietly drain portfolio value. Objective growth is impossible without a clear-eyed assessment of these internal frictions. If you’re ready to audit your exposure and define your floor, consider a partnership with a fiduciary advisor who understands the nuances of high-value portfolios.
The Role of Education and Philanthropy
Wealth is a tool for progress, and its management should reflect your personal values. Integrating Education Funding Strategies into the broader risk-growth framework ensures that legacy goals don’t compromise your primary growth objectives. Similarly, charitable giving serves as a strategic intervention to optimize tax outcomes. By using donor-advised funds or other specialized vehicles, you can fulfill philanthropic desires while lowering your tax hurdle, further demonstrating how financial advisors help balance growth and risk management as wealth increases. This holistic approach ensures that your wealth serves your family and your community with equal efficiency.
Partnering for Upward Progression: Why the Fiduciary Model Wins
Choosing a financial partner is one of the most consequential decisions a high-net-worth individual can make. As your portfolio gains complexity, the distinction between a broker and a fiduciary moves from a technicality to a fundamental pillar of your success. Brokers often operate under a “suitability” standard, which may prioritize products that meet basic needs but don’t necessarily optimize for your specific growth and tax requirements. In contrast, a fiduciary is legally and ethically bound to act in your best interest at all times. This higher standard is central to how financial advisors help balance growth and risk management as wealth increases, ensuring every decision is filtered through the lens of your long-term stability.
Boutique firms provide a level of personal attention that large, “big box” institutions simply cannot replicate. While major platforms rely on automated tools and standardized asset buckets, a specialized firm approaches your wealth as a unique architectural project. This is where the synthesis of aesthetics and functionality occurs; your personal vision for the future is supported by rigorous corporate capabilities and strategic depth. This craftsman-like approach ensures that your wealth management isn’t just a collection of services but a carefully curated intervention designed for your specific life stage.
The Visionary Strategist as Partner
A true partnership moves beyond the transactional. It’s a narrative of shared success where your advisor acts as a visionary strategist rather than a mere service provider. This relationship thrives on a blend of personal curiosity and professional rigor, allowing your partner to uncover opportunities that generic models miss. By understanding the nuances of your business interests and legacy goals, a dedicated advisor can craft a roadmap that feels both exclusive and accessible. Discover how a personalized strategy can elevate your wealth and provide the strategic oversight your hard work deserves.
Consistency in a Volatile World
Market cycles are inevitable, but your experience of them should be steady and logical. A professional consultancy model prioritizes a deliberate communication rhythm over the frantic, sales-driven tactics common in the broader industry. This steady pace prevents emotional decision-making and reinforces the idea that your wealth is on a journey of upward progression. By focusing on depth and intellectual curiosity, a fiduciary partner helps you build a rhythmic path to stability. It’s an intentional approach that transforms complex financial problems into structured, executable solutions, ensuring your legacy remains secure through every market shift.
Securing Your Financial Evolution
Mastering the equilibrium between aggressive growth and strategic preservation is the hallmark of financial maturity. We’ve explored how a sophisticated wealth architecture moves beyond generic retail models to address sequence of return risk and the technical necessity of tax-integrated planning. This shift ensures your portfolio remains a resilient engine for your lifestyle rather than a source of volatility. Understanding how financial advisors help balance growth and risk management as wealth increases allows you to transition from reactive management to visionary stewardship.
With over 25 years of specialized wealth management expertise, our firm provides the fiduciary-led, tax-integrated planning required for complex portfolios. We focus on personalized interventions that align your individual vision with structured corporate capabilities. This craftsman-like approach creates a rhythmic, logical path for your upward progression. Partner with a fiduciary strategist to secure your financial evolution. Your success is a journey of continuous refinement; it’s time to ensure every step is taken with calm confidence and strategic purpose.
Frequently Asked Questions
How do financial advisors determine the right balance of growth and risk?
Advisors determine this balance by first establishing your financial floor, which is the minimum capital required to maintain your current lifestyle indefinitely. Once this foundation is secure, surplus assets are allocated to a growth bucket designed to capture market upside. This methodology is a core part of how financial advisors help balance growth and risk management as wealth increases. It ensures that your essential security is never compromised by the pursuit of higher returns.
What is the ‘fiduciary standard’ and why is it critical for high-net-worth individuals?
The fiduciary standard is a legal and ethical obligation that requires advisors to act solely in their clients’ best interests. For high-net-worth individuals, this distinction is critical because complex portfolios often involve intricate fee structures and potential conflicts of interest. A fiduciary partner provides the objective, professional rigor necessary to navigate these complexities. This standard ensures that every intervention is selected for its strategic value rather than its commission potential.
Can an advisor help me reduce my tax liability as my investments grow?
An advisor significantly reduces your tax liability by integrating investment management with proactive tax preparation. This tax-alpha strategy focuses on maximizing net-after-tax returns through techniques like tax-loss harvesting and strategic asset location. By treating tax planning as a year-round discipline rather than a seasonal task, advisors identify surgical opportunities to lower your tax hurdle. This approach preserves more of your principal, allowing for more efficient compounding over the long term.
What is sequence of return risk and how does it affect my wealth?
Sequence of return risk is the danger that a market downturn occurs early in your withdrawal phase, which can disproportionately deplete your principal. Unlike the accumulation phase, where timing matters less, the withdrawal phase makes the order of returns vital for portfolio longevity. Advisors mitigate this risk by building defensive buffers and utilizing non-correlated assets. This protection is essential for ensuring your lifestyle remains sustainable regardless of when you begin drawing from your assets.
At what level of wealth should I move from self-management to a professional advisor?
Most individuals transition to professional management when the complexity of their tax obligations and investment structures exceeds their personal bandwidth or expertise. This often occurs when assets scale to a point where minor inefficiencies result in significant financial leaks. Professional advisors provide the visionary strategy and intellectual curiosity required to manage these intricate details. Moving toward a fiduciary partnership at this stage ensures your wealth is managed with the professional rigor it deserves.
How often should a high-net-worth portfolio be rebalanced for optimal risk management?
High-net-worth portfolios benefit most from threshold-based rebalancing rather than simple calendar-based intervals. This method involves continuous monitoring and taking action only when an asset class drifts beyond a predefined percentage of its target allocation. This proactive stance is another example of how financial advisors help balance growth and risk management as wealth increases. It allows the advisor to capture gains or buy into undervalued sectors without incurring unnecessary transaction costs.
Does balancing risk mean I have to accept lower returns?
Balancing risk doesn’t automatically mean settling for lower returns; it means seeking more efficient, purposeful growth. By reducing the tax drag and minimizing catastrophic downside exposure, you can often achieve better net-after-tax outcomes with less volatility. The goal is to maximize the probability of reaching your specific objectives rather than chasing arbitrary market benchmarks. This strategic equilibrium allows you to capture meaningful upside while ensuring your lifestyle and legacy are rigorously protected.
