
Sep
How to Choose a Financial Advisor Who Understands Family Business Succession
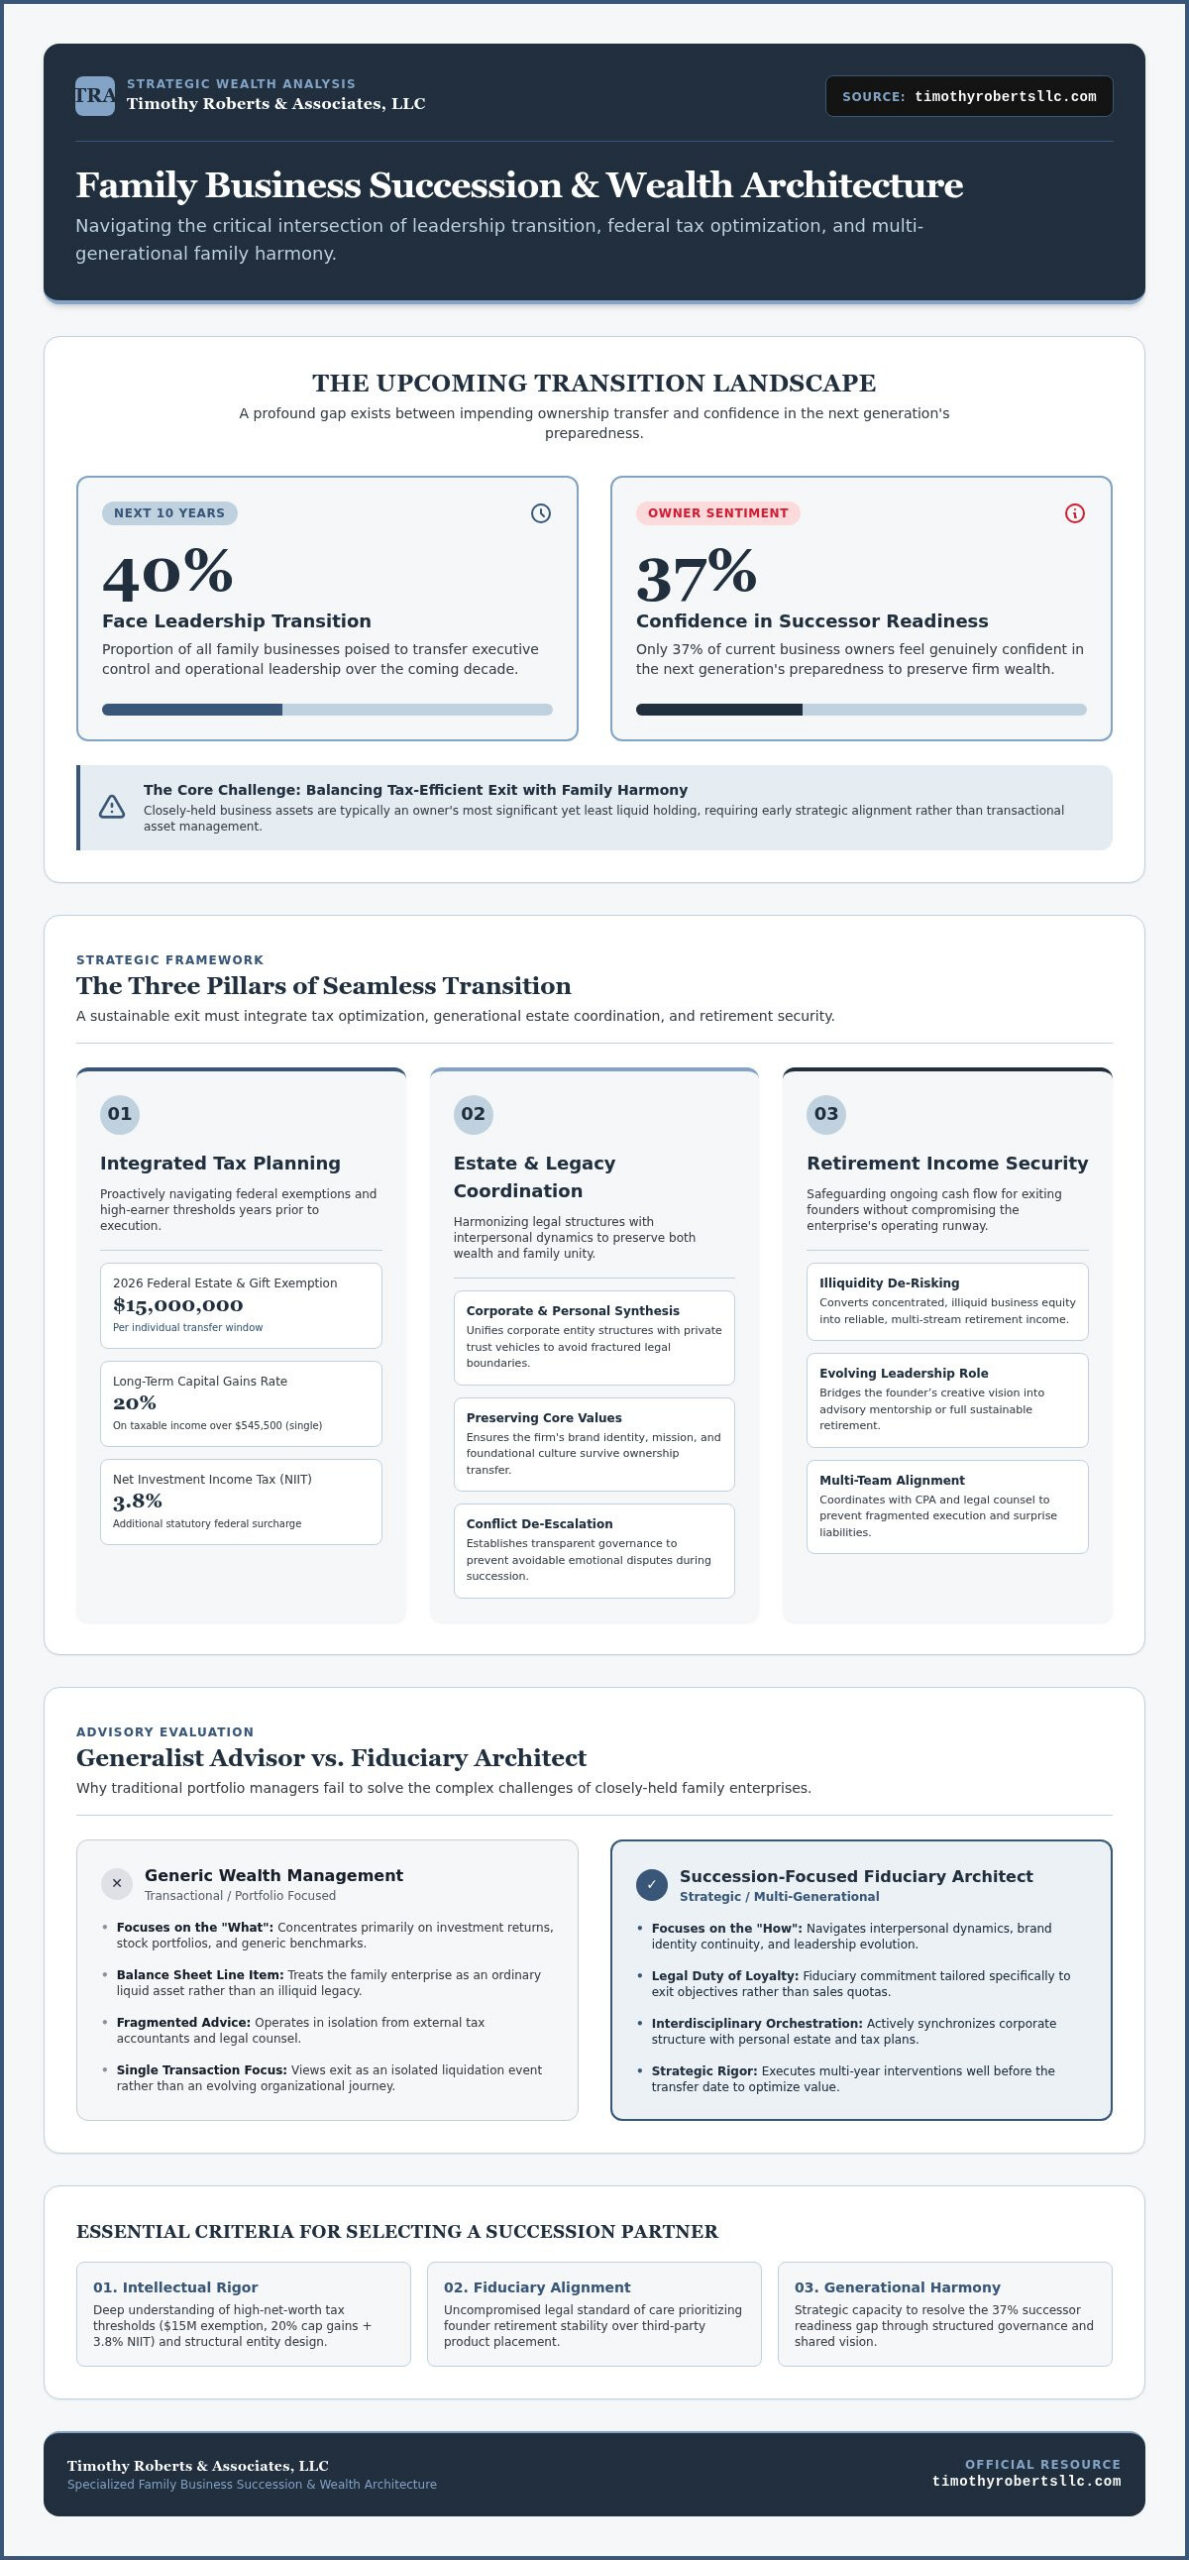
Forty percent of family businesses will face a leadership transition within the next decade, yet only 37 percent of owners feel truly confident in the next generation’s readiness. This gap represents more than just a management hurdle; it is a profound risk to the wealth you have spent a lifetime cultivating. Finding a financial advisor who understands family business succession is not about hiring a generalist to manage a portfolio. It is about identifying a visionary strategist who can harmonize the technical demands of a 15 million dollar estate tax exemption with the delicate nuances of family harmony.
You likely feel the weight of this transition, balancing the desire for a tax-efficient exit with the fear of triggering avoidable family conflict. It is a complex landscape where personal legacy meets corporate structure. In this article, you will discover the critical criteria for selecting a fiduciary partner capable of navigating the intersection of family legacy, tax optimization, and organizational transition. We will outline a clear roadmap for securing your retirement income while ensuring your business remains a source of pride for generations to come.
Key Takeaways
- Learn why generic wealth management fails to account for the unique illiquidity of business assets and requires a sophisticated synthesis of corporate strategy and personal wealth.
- Understand how to balance the three essential pillars of transition-tax, estate, and retirement-to ensure long-term stability for both the family and the firm.
- Identify the legal and ethical distinctions of a fiduciary financial advisor who understands family business succession, ensuring your interests remain the priority throughout the exit process.
- Discover the specific qualitative traits, such as intellectual curiosity and strategic rigor, that distinguish a visionary partner from a transactional consultant.
- Gain a clear roadmap for evolving your role from active leadership to sustainable retirement, bridging your personal creative vision with structured corporate capabilities.
Beyond Asset Management: The Specialized Role of a Succession-Focused Advisor
Traditional wealth management often treats a business as just another line item on a balance sheet. This perspective is fundamentally flawed for the closely-held enterprise. True Succession planning requires a sophisticated synthesis of corporate strategy and personal wealth, acknowledging that your business is likely your most significant yet least liquid asset. A generalist might focus on diversifying your stock portfolio, but they often overlook the technical and emotional gravity of transitioning a family legacy. A succession-focused advisor is a fiduciary architect of organizational and personal transition.
Identifying a financial advisor who understands family business succession is the first step in protecting what you’ve built. They act as a visionary strategist for the entire family unit, ensuring that the transition doesn’t just move capital, but preserves the values that defined the company’s growth. Succession is not a single transaction. It is an evolution.
To gain perspective on the interpersonal challenges inherent in this process, watch this discussion on succession dynamics:
The Distinction Between Generalists and Succession Specialists
Generalists prioritize the “what,” focusing on investment returns and market benchmarks. In contrast, a financial advisor who understands family business succession focuses on the “how.” They navigate the intricate intersection of aesthetics and business functionality, ensuring the firm’s brand identity remains intact while the leadership structure evolves. This role demands managing the emotional gravity of family dynamics alongside rigorous tax rules. It transforms a potentially volatile exit into a controlled, professional progression.
Why Business Owners Need a Fiduciary Architect
A fiduciary architect provides a layer of professional stability that transactional advisors simply cannot match. Their legal duty of loyalty ensures that advice is tailored to your specific exit goals rather than a standardized sales quota. This specialized partner doesn’t just manage money; they orchestrate the entire transition journey. They bridge the gap between your individual creative vision and the structured corporate capabilities required for a sustainable future. By coordinating with your existing tax and legal teams, they ensure that the roadmap for leadership is as tax-efficient as it is culturally sound. This collaborative approach prevents the fragmented advice that often leads to massive tax liabilities or organizational friction.
The Three Pillars of a Seamless Family Business Transition
A successful transition relies on a three-dimensional framework: tax optimization, estate coordination, and retirement security. Each pillar must be meticulously balanced to maintain structural integrity. Failing to integrate these components can lead to the rapid erosion of multi-generational wealth. Effective interventions cannot be rushed; they must occur years before the actual transfer date to maximize efficiency. Aligning these elements requires a financial advisor who understands family business succession and treats succession planning for small business as an ongoing strategic evolution rather than a one-time event.
Integrated Tax Planning and Compliance
Transferring ownership involves navigating significant fiscal hurdles. In 2026, the federal estate and gift tax exemption stands at 15 million dollars per individual, providing a substantial window for strategic wealth transfers. However, high-income earners face federal long-term capital gains tax rates of 20 percent on taxable income over $545,500 for single filers, plus a 3.8 percent Net Investment Income Tax (NIIT). Utilizing specialized tax advising allows owners to mitigate these liabilities and protect the core valuation of the enterprise. Year-round compliance serves as a critical defense against regulatory audits during the transition phase.
Estate Coordination and Legacy Protection
Basic wills are insufficient for securing a corporate transition. Sophisticated trust structures are required to maintain leadership continuity and shield operations from probate court. When structured correctly, advanced estate planning protects the company from external creditors and ensures that operational control transitions smoothly to qualified successors. This structural clarity minimizes the leadership gaps that frequently spark internal family disputes.
Sustainable Retirement Income Planning
Founders often struggle to separate their personal identity and lifestyle funding from the company’s operational cash flow. Developing a comprehensive retirement income plan ensures that your personal financial future survives the exit intact. This process involves establishing independent income streams that do not rely on the daily performance of the business. Additionally, robust risk management and insurance analysis protect your post-business life from unforeseen liabilities. If you want to explore how these pillars apply to your enterprise, consider speaking with the team at Timothy Roberts & Associates to evaluate your current transition readiness.
Fiduciary Standards vs. Transactional Advice in Business Exits
A business exit is often mischaracterized as a single, culminating deal. Transactional advisors typically focus on the sale event itself, driven by the lure of a one-time commission. This approach is inherently limited; it treats your life’s work as a discrete project rather than a continuous narrative of upward progression. In contrast, a fiduciary partner operates under a legal mandate of loyalty and care that extends far beyond the closing table. Selecting a financial advisor who understands family business succession involves looking past the immediate transaction to find a partner legally bound to your long-term prosperity. This relationship provides the calm confidence necessary to evolve from an active operator to a strategic steward of wealth.
The Long-Term Impact of Asset-Based Management
Ongoing asset-based management is fundamentally superior to project-based exit advice. When a business transitions from an illiquid enterprise into a liquid portfolio, the complexity of wealth management does not disappear; it simply changes form. A fiduciary advisor ensures the continuous monitoring and rebalancing of this new liquidity, aligning their incentives with the growth of your family’s legacy. This model avoids the “product-push” pitfalls common among broker-dealers held only to the Regulation Best Interest (Reg BI) standard. By prioritizing the journey over the transaction, you ensure that your capital remains productive and protected through every stage of your retirement.
Vetting the Advisor’s Strategic Rigor
Organizational evolution requires more than just financial spreadsheets; it demands a visionary strategist who respects the human-led nature of family enterprises. Research indicates that the most significant barriers to successful succession are relational, not technical. Relational friction, such as a founder’s reluctance to relinquish control or doubts regarding next-gen readiness, can derail even the most tax-efficient plans. You should evaluate an advisor’s intellectual curiosity regarding your specific business culture and their framework for handling these “soft” dynamics. Only a financial advisor who understands family business succession can bridge the gap between business liquidity and personal peace of mind while navigating these complex interpersonal waters. Their role is to provide a blend of creative passion and business-minded rigor, treating your development as a sophisticated evolution rather than a simple exchange of assets.
Key Criteria for Evaluating a Succession Planning Partner
Selecting a partner for organizational evolution requires a discerning eye for craftsmanship. It is not enough to simply review a list of credentials. You must evaluate the advisor’s depth of intellectual curiosity regarding your specific business model. A visionary strategist doesn’t offer generic advice; they seek to understand the intersection of your personal creative vision and the firm’s structured corporate capabilities. This synthesis is what allows a transition to feel like a natural progression rather than a disruptive event. Finding a financial advisor who understands family business succession is about identifying a partner who values depth over superficiality.
Experience and Longevity in Wealth Management
Stability is a proxy for professional rigor. When evaluating a firm, prioritize those with over 25 years of experience in wealth management. This longevity indicates they have navigated multiple market cycles and seen the long-term outcomes of various succession strategies. A firm that has maintained its own stability is better equipped to guide yours. You aren’t just hiring a consultant; you’re securing a partner whose team stability reflects the permanence you desire for your own legacy. This historical perspective is vital when moving away from aggressive sales tactics toward a narrative of shared success.
The ‘Sophisticated Partner’ Test
A high-end partner avoids a frantic or cluttered feel in favor of a steady, logical flow. During your evaluation, observe their communication rhythm. Do they explain complex tax strategies with a polished and intentional clarity? Do they offer carefully crafted interventions or off-the-shelf solutions? A financial advisor who understands family business succession will prioritize partnership over transaction, ensuring every recommendation is a bespoke response to your unique challenges. To see this level of strategic rigor in practice, you can schedule a consultation with Timothy Roberts & Associates.
Use this checklist during your initial consultation to gauge professional stability and strategic alignment:
- Intellectual Curiosity: They should ask probing questions about the company’s culture and internal family dynamics.
- Customization: They must demonstrate past interventions that weren’t generic templates.
- Communication Style: Their tone should be polished, intentional, and authoritative without being frantic.
- Fiduciary Commitment: They should clearly articulate their fiduciary duty for the entire duration of the relationship.
- Synthesis: They must be able to explain how your personal retirement goals directly influence the business’s tax structure.
Strategic Partnership: Advancing Your Legacy with Timothy Roberts & Associates, LLC
Timothy Roberts & Associates, LLC operates as a visionary strategist, moving away from the generic to the bespoke. We understand that your business is a reflection of your individual creative vision. Our role is to bridge that vision with structured corporate capabilities, ensuring that your exit is not an end, but a sophisticated evolution. As a financial advisor who understands family business succession, we treat your development as a journey of upward progression. We craft personalized financial strategies that respect your unique goals and specific risk tolerance, providing a stable foundation for the next chapter of your legacy. Our firm prioritizes personal attention, ensuring that high-level expertise is always paired with a deep understanding of your family’s values.
A Personalized Roadmap for Organizational Evolution
A successful transition requires a roadmap that addresses both the technical exit and the life that follows. We provide a human-led, results-driven identity that distinguishes our firm from anonymous corporate entities. By integrating sophisticated investment portfolio management into your broader succession plan, we ensure your newly liquid wealth continues to serve your family’s needs. This high-end, intentional partnership offers the peace of mind that comes from knowing every detail is managed with an expert craftsman’s precision. We focus on the intersection of aesthetics and functionality, ensuring your personal lifestyle is decoupled from the business while remaining fully funded. Our strategies aren’t off-the-shelf solutions; they’re carefully crafted interventions designed for long-term stability.
Taking the First Step Toward Your Strategic Future
The most critical decision an owner can make is deciding when to start the conversation. Waiting too long often leads to missed opportunities in tax optimization and organizational readiness. We specialize in minimizing liabilities for high-net-worth family businesses, utilizing our 25 years of experience to navigate the complexities of current tax thresholds. Our fiduciary-first approach ensures that every intervention is designed solely for your benefit, moving beyond aggressive sales tactics toward a narrative of shared success. We invite you to experience a professional consultancy that values depth over superficiality. By beginning this journey today, you ensure that your legacy is not left to chance, but is instead a carefully crafted masterpiece of strategic planning. Let’s discuss how we can bridge your creative vision with the structured corporate capabilities required for a sustainable future.
Secure Your Legacy Through Strategic Evolution
Transitioning from active leadership to a sustainable retirement is the ultimate test of a founder’s foresight. It requires more than just an exit plan; it demands a fiduciary architect who can harmonize complex tax thresholds with your family’s unique dynamics. By integrating comprehensive tax and estate strategies into your broader wealth plan, you protect the core valuation of your enterprise while securing your personal future. Identifying a financial advisor who understands family business succession ensures that your life’s work remains a source of pride and stability for the next generation.
With over 25 years of fiduciary expertise, Timothy Roberts & Associates provides the personalized wealth management small business owners need to navigate this journey with calm confidence. Don’t leave your organizational evolution to chance. Schedule a strategic consultation to begin your family business succession journey with Timothy Roberts & Associates. You’ve built a masterpiece; now is the time to ensure its permanence.
Frequently Asked Questions
What is the difference between a business broker and a succession-focused financial advisor?
A business broker primarily focuses on the transaction and finding a buyer to earn a commission. In contrast, a financial advisor who understands family business succession focuses on the long-term wealth strategy, tax optimization, and family legacy. Brokers handle the exit event, while advisors handle the life and wealth that follow. They ensure the sale aligns with your broader financial goals rather than just maximizing the immediate price.
How early should I hire a financial advisor before selling my family business?
Strategic interventions should ideally begin three to five years before a planned exit date. This timeline allows for the implementation of advanced tax planning strategies and the development of successors. Starting early helps in maximizing the 15 million dollar federal estate tax exemption available in 2026. Proactive planning ensures you don’t rush into a suboptimal deal due to a lack of structural preparation or sudden market shifts.
Can a financial advisor help with family disputes during a succession transition?
Advisors act as neutral, third-party strategists who facilitate objective discussions based on financial data and legacy goals. While they aren’t therapists, they use structured corporate capabilities to address the human-led nature of family enterprises. By creating a clear roadmap for leadership and wealth distribution, an advisor helps mitigate the emotional gravity of transitions. This structured approach provides the calm confidence needed to navigate potential friction among heirs.
What are the tax implications of passing a business to my children versus selling to a third party?
Passing a business to children often involves utilizing the annual gift tax exclusion, which is $19,000 per recipient in 2026, or the lifetime exemption. Selling to a third party typically triggers long-term capital gains taxes, which can be as high as 20 percent plus the 3.8 percent Net Investment Income Tax. A financial advisor who understands family business succession will analyze these variables to minimize massive tax liabilities for your specific situation.
How does fiduciary duty protect me during a business exit?
Fiduciary duty legally mandates that your advisor acts solely in your best interest at all times. This standard is significantly higher than the Regulation Best Interest (Reg BI) standard used by many brokers. It protects you from product-push tactics and ensures that advice regarding your exit is objective. Fiduciaries provide a duty of loyalty and care, ensuring your family’s wealth and legacy are prioritized over advisor commissions or project-based fees.
What should I bring to my first meeting with a succession planning advisor?
You should bring current business valuations, recent corporate and personal tax returns, and existing estate documents. It’s also helpful to have a clear outline of your individual creative vision for the company’s future. Providing a list of potential successors and your desired retirement timeline allows the advisor to begin crafting a personalized strategy. This data helps the firm understand the intersection of your professional assets and personal goals.
How do fixed-fee financial planning and asset-based fees work together in succession?
Fixed-fee financial planning covers specific project-based analysis, such as creating a succession roadmap or estate coordination. Asset-based management fees apply to the ongoing oversight and rebalancing of your investment portfolio after liquidity is achieved. These two structures work together to provide both a strategic initial plan and long-term fiduciary management. This combination ensures you receive high-level expertise for complex problems while maintaining a sustainable, results-driven management model for your future.
Can an advisor help me ensure my retirement income is not tied to the business’s future performance?
Yes, decoupling personal lifestyle needs from business cash flow is a primary goal of retirement income planning. An advisor helps you establish independent income streams through diversified investment portfolio management. By building a wealth strategy that doesn’t rely on the daily operations of the firm, you secure your future regardless of the business’s performance post-exit. This creates a sustainable retirement that survives the transition of leadership and protects your personal legacy.
