Living in a state without a death tax often creates a false sense of financial security. While the statutory michigan estate tax rate sits at zero percent, assuming your wealth will transfer entirely untaxed is an expensive oversight. A zero percent state tax rate does not mean zero transfer liability.
It’s easy to see why confusion surrounds this process. You likely appreciate that Michigan imposes neither a local estate tax nor an inheritance tax, yet genuine anxiety persists regarding federal brackets, inherited retirement accounts, and properties owned across state lines. Protecting what you have built requires separating state-level exemptions from broader federal exposure.
You’ll discover how Michigan estate rules genuinely function, how the federal $15 million individual baseline exclusion impacts your household in 2026, and how proactive wealth architecture shields family assets. What follows is a clear analysis of your true transfer liabilities and the strategic steps needed to preserve your multi-generational legacy.
Key Takeaways
- Understand why the absence of a statutory michigan estate tax does not eliminate liability, leaving high-net-worth households open to substantial federal exposure.
- Evaluate how the permanent 2026 federal exclusion thresholds impact family wealth and what remaining brackets require proactive structuring.
- Uncover hidden transfer liabilities affecting multi-state real estate holdings, inherited retirement assets, and embedded capital gains.
- Explore advanced wealth preservation techniques, including basis management and lifetime gifting frameworks, designed to insulate family capital across generations.
- Learn how coordinating continuous portfolio management with fiduciary tax planning protects long-term assets far more effectively than isolated legal documents.
Does Michigan Have an Estate Tax in 2026? State Laws and Inheritance Rules
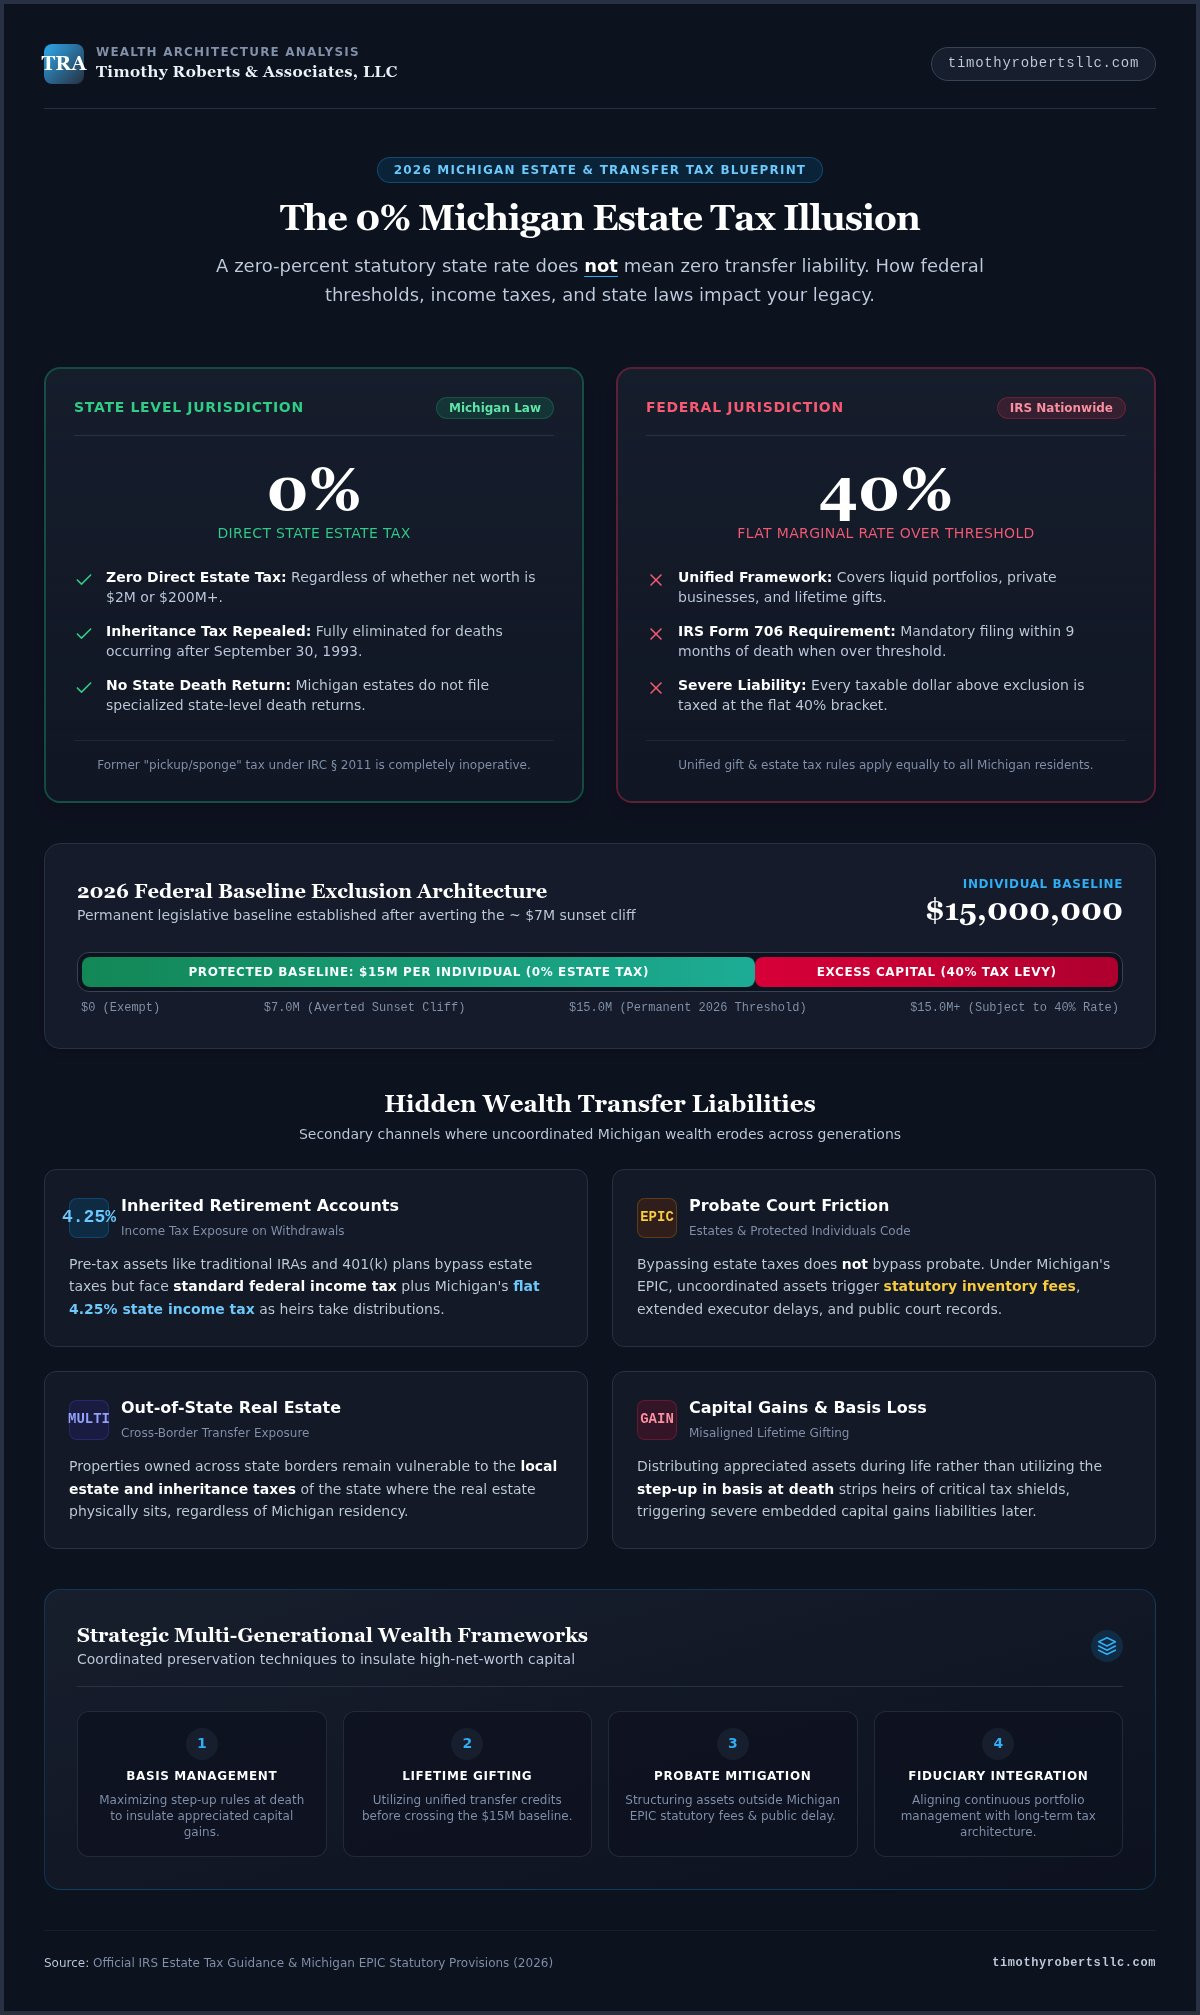
Clarity begins with a definitive answer. Michigan does not impose a state-level estate tax in 2026. If you pass away as a Michigan resident, your estate owes zero dollars directly to the state treasury, regardless of whether your net worth is two million or two hundred million dollars. Michigan estates don’t need to file a specialized state death return.
This reality often creates unjustified complacency. Historically, Michigan maintained an estate levy tied to the federal state death tax credit, commonly referred to as a “pickup” or “sponge” tax. When federal reforms replaced that credit under IRC § 2011 with a deduction, the mechanism powering the statutory michigan estate tax became completely inoperative. Surviving heirs also face no Michigan inheritance tax, which was repealed for deaths occurring after September 30, 1993. Beneficiary status, whether you leave capital to children, siblings, or lifelong friends, triggers no state transfer assessment.
However, total state exemption doesn’t mean your wealth transfers unburdened. The broader architecture of the estate tax in the United States still dictates substantial exposure once your cumulative holdings cross federal thresholds.
The Mechanics of Michigan Estate and Inheritance Tax Laws
Understanding transfer liabilities requires distinguishing the target of the taxation:
- Estate Tax: Levied against the total fair market value of the decedent’s assets before any distribution takes place. Michigan enforces no such levy.
- Inheritance Tax: Assessed directly against the beneficiary receiving the wealth, often calibrated by their familial closeness to the deceased. Michigan levies no inheritance tax on any heir.
Because the state statutes defer entirely to the federal code rather than establishing independent state-level thresholds, local residency provides complete relief from separate state transfer filings.
Common Misconceptions Regarding Wealth Transfer in Michigan
Transferring capital involves far more than checking a single state statutory box. Significant leaks frequently erode multi-generational wealth through secondary channels:
- Income Tax on Inherited Assets: While the inheritance itself isn’t taxed as a transfer, pre-tax accounts such as traditional IRAs and 401(k) plans remain subject to standard state (flat 4.25%) and federal income taxes as beneficiaries withdraw funds.
- Probate Court Friction: Bypassing estate taxes doesn’t bypass probate court. Under Michigan’s Estates and Protected Individuals Code (EPIC), uncoordinated assets trigger statutory inventory fees, prolonged executor delays, and public record disclosures.
- Capital Gains Exposure: Distributing assets improperly during life instead of taking advantage of basis step-ups at death can burden heirs with heavy income tax liabilities down the road.
Federal Estate Tax Exposure: Navigating the 2026 Exemption Changes
Federal rules dictate the real financial consequences for affluent families. While local statutes offer relief from a direct michigan estate tax, the Internal Revenue Service enforces a unified gift and estate transfer framework nationwide. Recent legislative changes permanently altered the long-anticipated Tax Cuts and Jobs Act (TCJA) sunset, establishing a definitive $15,000,000 baseline exemption per individual for 2026. This federal intervention averted a steep cliff that threatened to cut exemptions to approximately $7 million, yet it leaves estates above the threshold facing severe liability.
Any taxable dollar transferring beyond these statutory exclusions triggers a flat 40% marginal rate. A high-net-worth estate holding liquid portfolios, private business interests, and real estate can quickly accumulate substantial tax exposure without deliberate intervention. Official IRS estate tax guidance outlines that cumulative gross estates, coupled with adjusted lifetime gifts, must file Form 706 within nine months of death. Strategic alignment between your financial holdings and estate vehicles remains essential to insulate multi-generational wealth.
Understanding the Federal Lifetime Gift and Estate Tax Exemption
The unified credit connects what you give away during life with what transfers at death. In 2026, the federal exemption stands at $15 million per donor, mirroring the generation-skipping transfer (GST) tax exemption. Married couples can shield up to $30 million through the portability election of the Deceased Spousal Unused Exclusion (DSUE). Annual gifting parameters allow up to $19,000 per recipient ($38,000 for couples utilizing gift-splitting) without encroaching on this lifetime credit.
The Impact of the Sunset on Wealthy Estates
While the sudden reduction to $7 million was halted, statutory “permanence” merely means there is no pre-scheduled expiration date. Congress routinely evaluates wealth transfers during broader budget negotiations. Families with balance sheets ranging from $10 million to $50 million face the greatest exposure to shifting political winds and dynamic rate structures.
Preserving your assets requires moving beyond isolated legal forms to actively integrate investment portfolios, retirement vehicles, and wealth strategies. Coordinating your financial architecture through comprehensive estate planning ensures that portfolio distributions, charitable intentions, and generation-skipping trusts work in complete harmony. Taking a strategic approach today positions your heirs to receive wealth intact, turning complex statutory thresholds into an organized path of upward family progression.
Hidden Wealth Transfer Liabilities: Multi-State Property, Income Taxes, and Capital Gains
Tax exposure rarely respects state borders. While a primary residence escapes any direct michigan estate tax, your balance sheet often extends far beyond local lines. Secondary vacation homes, rental units, and family cottages located outside Michigan immediately introduce the jurisdictional tax statutes of those locations. Twelve states and Washington, D.C., levy separate estate taxes with exemptions reaching as low as $2 million, while six other states assess inheritance taxes directly on beneficiaries.
Cross-border asset ownership creates immediate complications for wealth preservation. Understanding the legal distinction between estate and inheritance taxes proves essential when tangible holdings trigger foreign state death duties. Without unified wealth architecture, an otherwise exempt family estate can face sudden tax liabilities in an external jurisdiction.
Out-of-State Real Estate and Ancillary Probate Exposure
Tangible property is taxed where it sits physically, not where the owner resides. When a Michigan resident passes away owning titled real estate in Illinois, Massachusetts, or New York, those states assert tax claims over that specific property value. Additionally, titled assets outside the home state force your family into ancillary probate, a secondary court proceeding requiring separate legal filings, additional executor fees, and prolonged administrative delays.
Holding out-of-state parcels inside revocable living trusts or limited liability companies converts real property into intangible personal property. This structural evolution avoids ancillary probate and insulates family assets from non-resident state estate taxes.
Taxation of Inherited Retirement Accounts and Capital Assets
Retirement savings present an entirely different financial hurdle. Qualified balances such as traditional IRAs and 401(k) plans constitute Income in Respect of a Decedent (IRD). They do not benefit from a step-up in basis. Under the SECURE Act, non-spouse beneficiaries must empty inherited accounts entirely within ten years of the account owner’s passing. This forced acceleration routinely pushes heirs into their peak earning brackets, subjecting distributions to combined federal and state income tax burdens reaching upward of 40%.
Taxable brokerage portfolios, conversely, gain an IRC § 1014 step-up in basis to fair market value at death, eliminating embedded capital gains taxes. Combining investment management with strategic tax advising allows families to orchestrate systematic Roth conversions and lifetime charitable distribution models, dramatically lowering IRD burdens while maximizing basis appreciation for rising generations.
Strategic Legacy Structuring: Core Wealth Preservation Frameworks
Preserving family capital demands an intentional blueprint. While statutory relief from a direct michigan estate tax simplifies state filings, federal exposure requires dynamic structural discipline. Building an enduring legacy isn’t accomplished through static paperwork. It requires integrating portfolio growth, tax mitigation, and wealth architecture into a cohesive long-term plan.
Fiduciary wealth managers design this strategic framework, collaborating directly with estate attorneys who draft the underlying legal instruments. Synchronizing your balance sheet with structural protections shields assets from premature depletion.
Maximizing Lifetime Gifting and Irrevocable Trust Vehicles
Systematic gifting removes significant future appreciation from your taxable gross estate. Utilizing the 2026 annual gift exclusion allows you to transfer up to $19,000 per recipient, or $38,000 for married couples utilizing gift-splitting, without filing Form 709 or reducing your lifetime exclusion. Over several years, gifting across children and grandchildren shifts substantial capital entirely tax-free.
For larger estates, specialized irrevocable trusts insulate high-growth holdings:
- Irrevocable Life Insurance Trusts (ILITs): Remove policy death benefits from your gross estate, providing immediate, tax-free liquidity to satisfy liabilities without forcing the liquidation of core family assets.
- Spousal Lifetime Access Trusts (SLATs): Lock in generous federal exemption thresholds by gifting assets to an irrevocable vehicle for a spouse, removing future growth from estate tax calculations while preserving indirect marital access.
Retirement Portfolio Repositioning and Beneficiary Optimization
Mitigating transfer friction also requires addressing qualified retirement balances. Systematically converting traditional pre-tax funds into Roth accounts shifts the tax burden to earlier, lower-bracket retirement years. When non-spouse heirs inherit a Roth IRA, their mandated distributions across the ten-year SECURE Act timeline remain completely tax-free. This approach insulates heirs from sudden marginal tax spikes during their peak earning years.
Beneficiary designations require continuous review. These designations supersede testamentary instructions in a will, transferring assets directly by contract. Failing to align contingent beneficiaries, per stirpes designations, and trust titling invites unnecessary court intervention.
Coordinating distribution frameworks directly with tailored retirement income planning bridges current lifestyle needs with generational transfer goals. If you are ready to insulate your assets against unnecessary taxation, connect with our fiduciary advisory team to construct an integrated legacy strategy.
Integrating Tax Strategy with Wealth Management: The Role of a Fiduciary Advisor
True financial stewardship transcends static legal forms. Too many families assume that executing a will or establishing a trust concludes their estate planning. While statutory rules relieve residents of a direct michigan estate tax, capital preservation requires active, continuous management. Without disciplined coordination between your investment allocations and evolving tax codes, the wealth you spent decades accumulating remains vulnerable to preventable erosion.
A fiduciary wealth advisor operates as your strategic architect. While legal professionals specialize in drafting essential documents, fiduciary advisors ensure your day-to-day balance sheet actually reflects those legal intentions. With over 25 years of wealth management and tax advisory experience, an integrated fiduciary synchronizes portfolio positioning, annual tax harvesting, and multi-generational distributions into a single, cohesive framework.
The Triad of Fiduciary Wealth Management, Tax, and Legal Strategy
Siloed advisory relationships create systemic blind spots. An attorney might draft an exceptional trust, but if your investment manager never funds the vehicle or misclassifies asset titling, the legal protection fails. Fiduciary oversight harmonizes wealth management, tax planning strategies, and legal structures into a collaborative triad. This ongoing discipline ensures that dynamic shifts in federal transfer thresholds, capital gains rates, and portfolio valuations are systematically managed year-round.
Initiating Your Comprehensive Legacy Review
Elevating your family wealth preservation strategy starts with an objective evaluation of your current financial architecture:
- Balance Sheet and Titling Audit: Examine all held real property, closely held business entities, and investment accounts to verify appropriate titling and primary or contingent beneficiary accuracy.
- Transfer Exposure Stress-Testing: Model your gross taxable estate against current and prospective federal transfer thresholds, quantifying potential tax friction before statutory windows adjust.
- Asset Location and Basis Optimization: Calibrate liquid portfolios across taxable, tax-deferred, and tax-free accounts to maximize basis step-ups while curbing beneficiary income liabilities.
Safeguarding family wealth extends beyond relying on the absence of a localized michigan estate tax. Engaging a dedicated fiduciary advisory team bridges portfolio performance with deliberate legacy design, turning complex tax regulations into an enduring framework of multi-generational growth.
Securing Multi-Generational Wealth Beyond Statutory Boundaries
A zero percent michigan estate tax offers genuine statutory relief, but lasting capital preservation demands looking well beyond local borders. Federal transfer brackets, out-of-state property liabilities, and compressed retirement distributions can quickly erode what took decades to build. Real wealth protection isn’t a passive event; it’s an evolving, highly coordinated discipline.
Safeguarding family assets requires complete harmony between your investment portfolio, proactive tax advising, and long-term legacy structures. Backed by over 25 years of specialized fiduciary wealth management experience, our firm delivers the comprehensive integration needed to protect your household balance sheet. Schedule a Strategic Estate and Wealth Consultation today, and take the definitive step toward shielding your assets, empowering your heirs, and advancing your multi-generational vision with calm confidence.
Frequently Asked Questions
Does Michigan impose an estate tax or inheritance tax in 2026?
No. There is no statutory michigan estate tax or inheritance tax in 2026. The state’s previous sponge tax became inoperative when federal law eliminated the state death tax credit. Michigan estates owe zero dollars directly to the state treasury, and heirs pay no inheritance tax regardless of familial relationship. However, you must still account for potential federal transfer exposure on higher-value household balances.
Who is subject to the federal estate tax if living in Michigan?
Michigan residents whose worldwide gross taxable estates exceed the federal lifetime exclusion threshold face federal transfer taxes. For 2026, the baseline exclusion is $15 million per individual or $30 million for a married couple utilizing portability. Any assets transferred above that combined exclusion face a flat 40% marginal rate. Your gross estate includes real property, investment accounts, business interests, and life insurance death benefits.
Do beneficiaries have to pay income tax on inherited assets in Michigan?
While receiving an inheritance isn’t treated as taxable income, underlying asset classes determine income tax liability. Non-qualified assets such as taxable brokerage accounts receive a basis step-up, eliminating capital gains on prior growth. Pre-tax retirement accounts like traditional IRAs and 401(k)s remain fully taxable as ordinary income when withdrawn. Non-spouse beneficiaries must empty these accounts within ten years under SECURE Act rules, paying standard income taxes.
What happens if a Michigan resident owns real estate in another state?
Real property is subject to the legal jurisdiction where it sits physically. If you own vacation properties or rental units in one of the states levying independent estate taxes, your estate may owe transfer taxes to that state even with no local michigan estate tax due. Real estate titled solely in your personal name also triggers ancillary probate, creating secondary court proceedings, separate legal fees, and prolonged administrative delays.
How does the 2026 federal estate tax sunset affect existing estate plans?
Federal legislation averted the steep 50% exemption reduction originally scheduled under the Tax Cuts and Jobs Act, establishing a $15 million baseline per person for 2026. Existing plans designed under previous sunset fears should be reviewed immediately. The strategic focus has shifted from aggressive use-it-or-lose-it lifetime gifts toward optimizing the step-up in basis under IRC § 1014, ensuring highly appreciated assets avoid unnecessary capital gains taxes.
Can establishing a trust help protect my assets from estate taxes?
Yes, but the specific trust structure dictates the tax result. Standard revocable living trusts avoid probate and streamline distributions, but they don’t reduce gross taxable estate calculations. Irrevocable vehicles, such as Irrevocable Life Insurance Trusts (ILITs) or Spousal Lifetime Access Trusts (SLATs), remove asset values and future appreciation from your taxable estate. These strategic instruments insulate family wealth, provide necessary liquidity, and shield multi-generational legacies.
What is the difference between an estate planning attorney and a wealth advisor?
An estate planning attorney focuses on legal compliance, structuring statutory frameworks, and drafting legal instruments such as trusts, wills, and powers of attorney. A fiduciary wealth advisor directs strategic wealth architecture, managing investment portfolios, optimizing retirement distributions, and modeling ongoing tax strategies. Both disciplines coordinate closely, aligning day-to-day asset titling and investment allocations with the attorney’s formal legal instruments to ensure complete protection.