
Oct
How to Fire Your Financial Advisor Gracefully: A Clear Transition Plan
Ending an advisory relationship doesn’t have to become a confrontation. The clearest way to approach how to fire your financial advisor gracefully is to treat it as a documented transition, with continuity in your financial plan at the center.
It’s understandable to worry about an awkward conversation, unclear paperwork, outstanding fees, or a gap in retirement and investment planning. You can be respectful and direct while taking time to understand what happens to your accounts and how your next steps will be coordinated.
This guide explains what to review before making a change, how to communicate your decision in writing, and what to consider during an account transfer. It also covers ways to keep investments, retirement income, and tax planning connected as you move forward. A thoughtful sequence can help you close one advisory relationship professionally and make your next decision with greater confidence.
Key Takeaways
- Recurring gaps in communication, service, or strategy can signal a mismatch worth addressing, without turning the decision into a personal conflict.
- Before deciding how to fire your financial advisor gracefully, review your agreement, fee terms, account list, and recent statements.
- Consider whether resetting expectations or narrowing the planning scope could better fit your needs than ending the relationship.
- A brief written notice can state your decision, effective date, and request for records while keeping the transition professional.
- Organize key plan documents, account details, and upcoming financial decisions to support continuity as responsibilities shift.
How to Know When to Fire Your Financial Advisor
Ending an advisory relationship can be a considered financial decision, not a personal attack. Your needs, priorities, or expectations may have changed, or the arrangement may no longer provide the support you understood you were receiving. A Financial adviser may offer guidance across investments and other financial matters, but each relationship has its own scope. Compare the support you need with the services you agreed to receive before deciding whether the fit still works.
Try not to make a long-term decision based on one missed call or disappointing meeting. Look for a pattern instead. Write down each concern, when it occurred, what you expected, and whether you raised the issue. Note the response and any effort to resolve it. This record can help you distinguish a temporary frustration from a persistent mismatch and clarify what you want from the relationship going forward.
Which concerns signal a persistent mismatch?
Repeated communication gaps, unclear responsibilities, or recommendations that seem out of step with your stated goals deserve attention. For example, if retirement income planning is a priority but your conversations repeatedly focus elsewhere, review what your agreement says about the services provided. Compare the agreed scope with the support you actually receive, rather than relying on assumptions about what an advisor should do.
- Communication: Are questions regularly left unanswered, or are updates less frequent than you agreed?
- Responsibilities: Is it clear who handles planning tasks, account questions, and follow-up?
- Strategy: Do recommendations reflect your goals, time horizon, and stated comfort with risk?
Dissatisfaction alone doesn’t establish misconduct. If you have specific concerns about how an account or recommendation was handled, preserve relevant records and separate those facts from broader frustration with service. A recurring mismatch may support a change; a concern involving possible wrongdoing may call for more formal attention.
Can you reset expectations before ending the relationship?
A direct conversation may show whether the relationship can improve. Arrange a meeting with a short agenda: identify your priorities, describe where support has fallen short, and explain the communication rhythm and planning responsibilities you want clarified. Keep the discussion specific and focused on what happens next. For instance, describe the decisions you need help preparing for instead of making the conversation a judgment of the advisor’s character.
Afterward, consider whether the advisor understood your concerns and whether the proposed approach fits your needs. If your priorities have shifted, clarify which services matter most. A useful distinction is this: a mismatch may be repairable when expectations are unclear and both sides can agree on a practical reset; it’s more likely to persist when the same gap continues after expectations have been clearly discussed.
You’re not obligated to stay simply because you raised the issue, and you don’t have to leave after one candid conversation. Decide based on the pattern, your priorities, and whether the relationship still supports the financial plan you want. That measured judgment is central to how to fire your financial advisor gracefully, if ending the engagement is the right next step.
What to Review Before You End a Financial Advisory Relationship
Preparation can make the transition more orderly and help you avoid overlooking an account or responsibility. Before giving notice, gather the documents that describe your relationship and your current financial picture. Termination provisions, billing practices, and transfer procedures depend on the agreement you signed and the institutions involved, so review the actual terms rather than relying on assumptions.
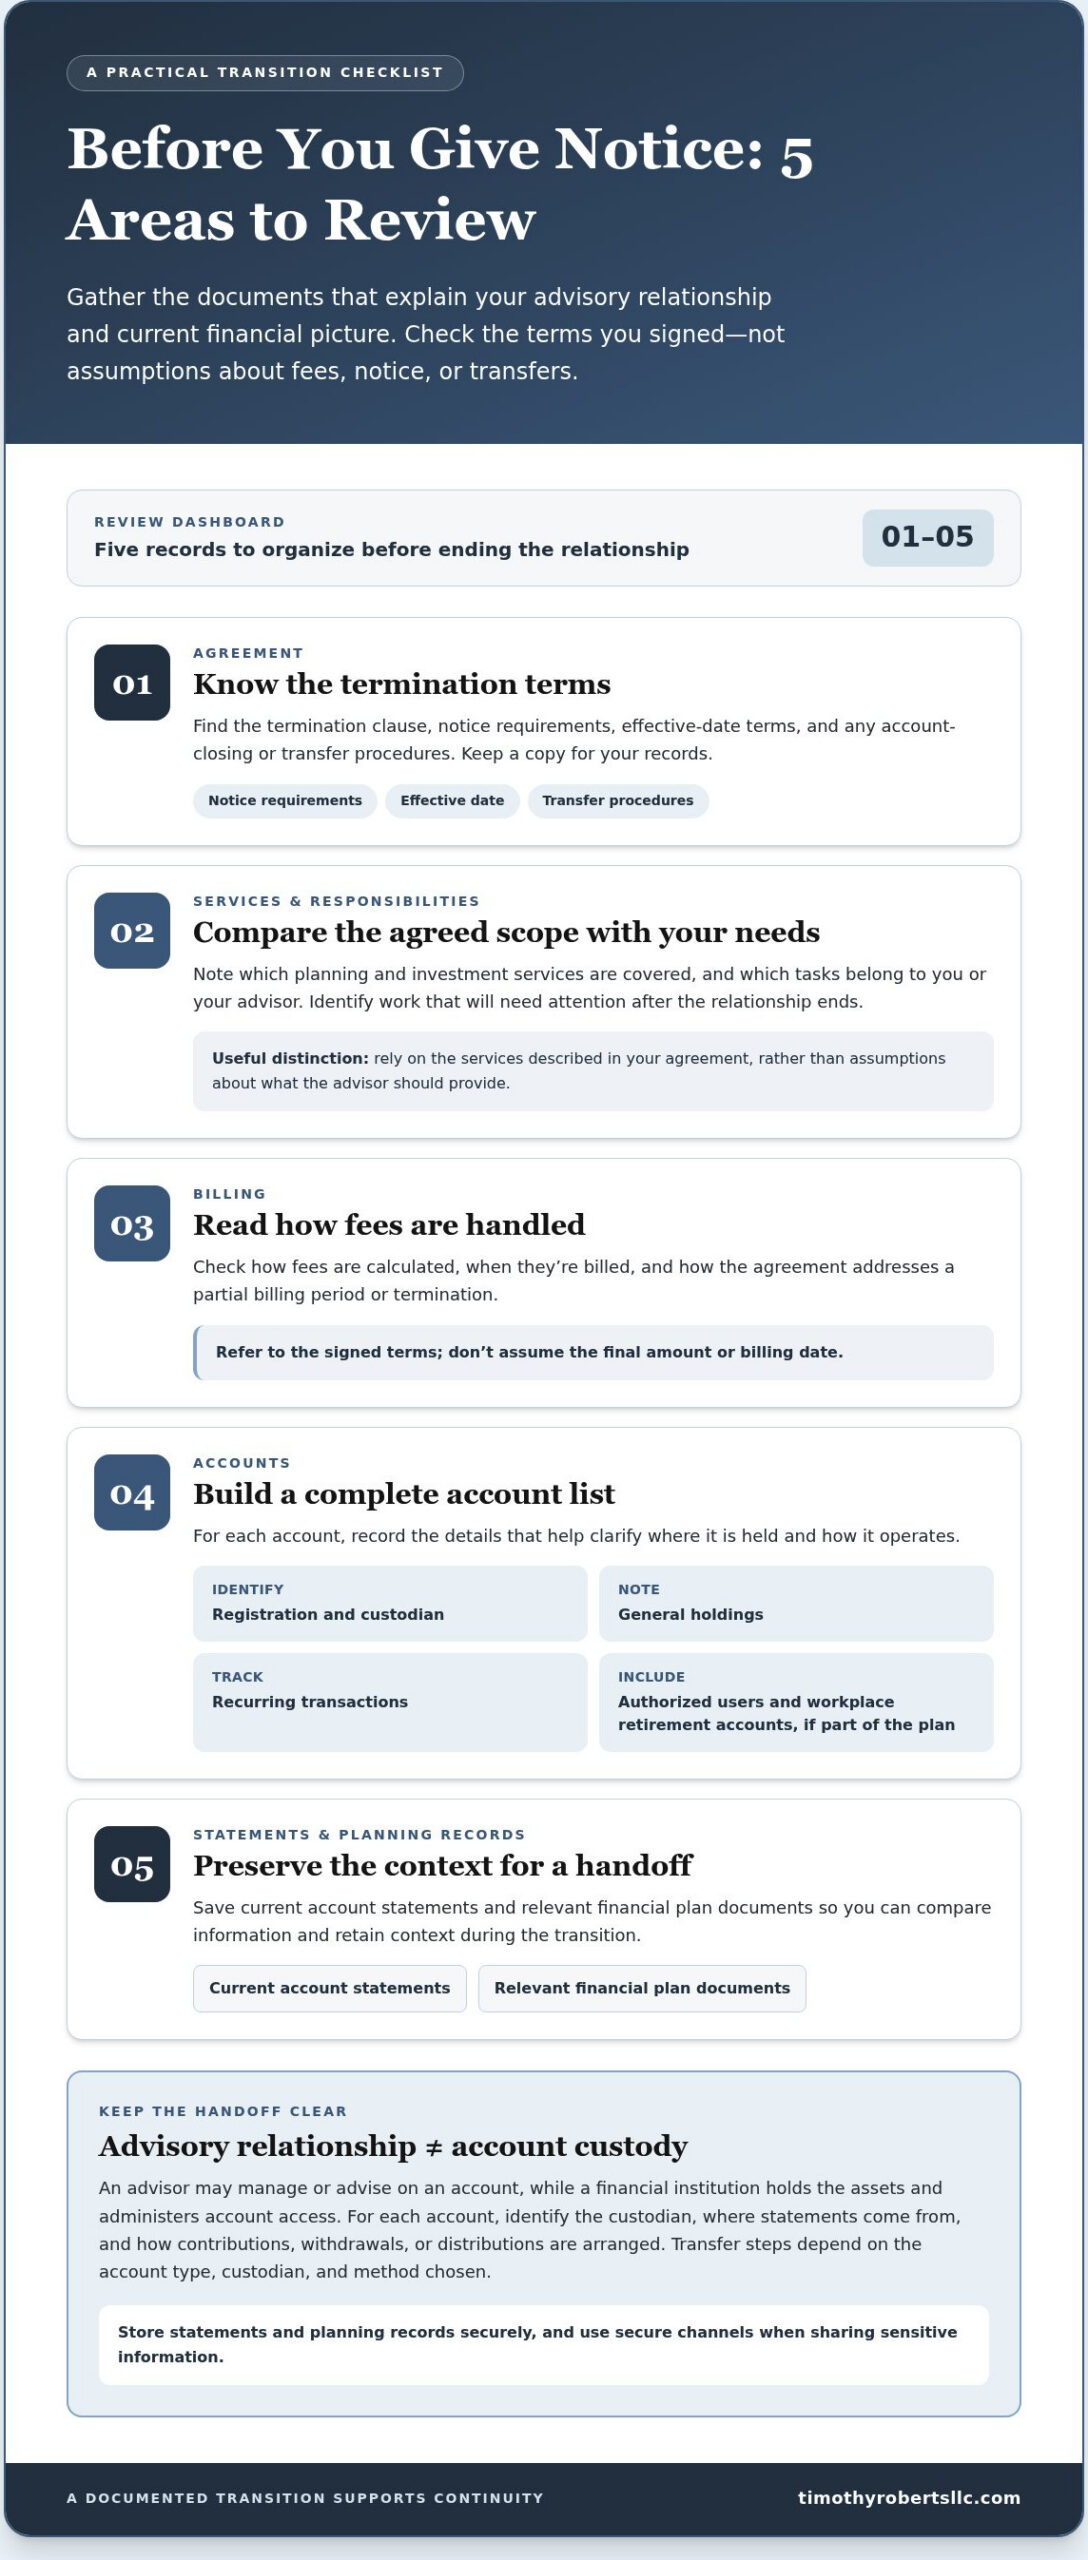
Use this checklist to build a clear record before taking action:
- Review your advisory agreement. Locate the termination clause, notice requirements, effective-date terms, and any account-closing or transfer procedures. Keep a copy for your records.
- Compare services with your needs. Note the planning and investment services covered, along with responsibilities assigned to you or your advisor. This helps identify work that will need attention after the relationship ends.
- Read the billing terms. Check how fees are calculated, when they’re billed, and how the agreement handles a partial billing period or termination. Refer to the signed terms rather than assuming the final amount or billing date.
- Create a complete account list. Record each account’s registration, custodian, general holdings, recurring transactions, and authorized users. Include workplace retirement accounts if they’re part of the planning relationship.
- Collect recent statements and planning records. Save current account statements and relevant financial plan documents so you can compare information and preserve context during the handoff.
Which agreement and account details should you gather?
Separate the advisory relationship from account custody. An advisor may manage or provide advice about an account, while a financial institution holds the assets and administers account access. For each account, identify the custodian, where statements come from, and how recurring contributions, withdrawals, or distributions are arranged. Transfer steps depend on the account type, custodian, and method you choose.
Store statements and planning records securely, and use secure channels when sharing sensitive information. Avoid sending account numbers, tax records, or login credentials through ordinary email. A complete inventory helps you identify what needs attention without relying on memory.
What should you understand about fees, taxes, and transfers?
Ending advisory services doesn’t automatically mean selling investments or closing accounts. Those are separate actions, and the right sequence depends on your circumstances and the institutions involved. Before authorizing a transaction, clarify whether it’s part of the transfer or a separate decision. The agreement and applicable institutions determine final billing, any transfer or closing charges, and processing timelines.
If assets may be sold, consider potential tax consequences before giving instructions. The impact can depend on the account and asset, so review the question with an appropriate tax professional. Preparing before you decide how to fire your financial advisor gracefully can help maintain continuity across investments, retirement income, and tax planning. A coordinated financial planning approach can help keep those priorities connected as your arrangements change.
Should You Leave, Reset Expectations, or Change Your Planning Arrangement?
Leaving isn’t the only response when an advisory relationship no longer feels like the right fit. Clearer expectations or a narrower scope may address the issue; in other cases, a full transition may better reflect your needs. Compare the options against the planning support you need, how you want to communicate, and how much transition work each choice involves. No option guarantees a particular result.
| Option | Best fit when | Communication and planning needs | Likely transition complexity |
|---|---|---|---|
| Stay as-is | The current arrangement still fits your goals and concerns are limited or temporary. | Existing communication and service scope remain acceptable. | Low, since no change is planned. |
| Reset expectations | Responsibilities or contact preferences need clarification. | Agree on priorities, follow-up, and a meeting rhythm that fits your needs. | Low to moderate, depending on whether processes need to change. |
| Narrow the scope | You need help with a defined planning issue but not the full existing arrangement. | Clarify which needs remain in scope, such as a specific planning priority versus ongoing portfolio oversight. | Moderate, since services and responsibilities may need to be revised. |
| End the engagement | Persistent misalignment, trust concerns, or changing needs point toward a different arrangement. | Plan how to maintain support for investments and broader financial decisions. | Higher, because records, responsibilities, and any account transitions may need coordination. |
When might a conversation or narrower scope be enough?
A reset may make sense if the main issue is an unclear division of responsibilities or an inconvenient meeting cadence. You might agree on what you’ll provide before each review, which questions the advisor will address, and how often you’ll discuss progress. A narrower arrangement could also fit if you need focused planning around retirement income while preferring to handle other financial tasks independently.
Ongoing investment portfolio management differs from help with a specific planning decision. Clarifying which type of support you want can reveal whether the mismatch concerns the relationship itself or its scope. You’re not required to preserve an arrangement that no longer serves you.
When might a full transition better fit your goals?
A departure may be worth considering if the same concerns continue after expectations have been discussed, if trust has materially changed, or if your planning needs have evolved beyond the existing relationship. Weigh those reasons against the work required to transfer responsibilities and keep important decisions on track. The right choice depends on your circumstances, not a universal rule.
If you decide to leave, a clear, documented plan can help you move forward respectfully and protect continuity. That’s the practical foundation of how to fire your financial advisor gracefully: choose the arrangement that fits, then coordinate the next steps with care.
How to Tell Your Financial Advisor You Are Leaving
A clear written message documents your decision and the transition actions you’re requesting. You don’t need to make the conversation confrontational or provide a detailed defense. Keep the tone professional, state what you’ve decided, and focus on the practical steps needed to close the relationship and coordinate any account changes.
Use this sequence:
- Make your decision. Decide whether you’re ending the engagement and identify the date you intend the change to take effect.
- Review your notice terms. Check your agreement for any required notice period or instructions about ending services.
- Send written notice. Address it to the appropriate advisor or firm contact, using the delivery method specified in your agreement if one is provided.
- Coordinate next steps. Request relevant records and clarify who will handle remaining administrative tasks. Coordinate account-related instructions with the institution that holds the assets.
What should a professional departure message say?
Include your name, the advisory relationship or account identifiers needed to locate your records, your decision, and the intended effective date. Request final statements, relevant records, and confirmation of remaining administrative steps. Keep your explanation brief and share only what you’re comfortable putting in writing. Don’t include passwords, full account credentials, or unnecessary sensitive details in an email.
Here’s a concise template you can adapt:
Subject: Notice to End Advisory Relationship
Hello [Advisor Name],
I’m writing to end my advisory relationship with [Firm Name], effective 2026, subject to the terms of my agreement. Please provide any final account statements and relevant planning records, and let me know what administrative steps remain. I’ll coordinate any account-related instructions with the applicable custodian.
Thank you for your work on [specific service or support you value]. Please confirm receipt of this notice.
Regards,
[Your Name]
How can you keep the transition courteous and clear?
Direct language is usually kinder than a vague message that leaves the decision open to interpretation. If there’s work you genuinely appreciated, a brief acknowledgment can preserve a respectful tone without weakening your decision. You don’t have to debate your reasons or make personal criticisms. If asked for feedback, share only what you’re comfortable discussing and keep it focused on your experience and needs.
Save a copy of your notice and any responses in a secure personal record. Follow up if you haven’t received confirmation or a requested record is outstanding. Before treating the transition as complete, confirm that advisory services have ended as intended and that any account changes have been processed by the relevant institution. Clear communication supports continuity across investments, retirement income, and tax planning.
If you’re preparing for a new chapter in your financial plan, explore comprehensive financial planning to bring your investment and retirement priorities into one coordinated picture.
How to Protect Financial Planning Continuity After You Leave
A change in advisor doesn’t have to mean putting every financial decision on hold. The goal is to carry forward the information and priorities that shape your plan, without rushing into changes simply because the relationship has ended. An organized handoff can help you see what’s already in motion and what needs attention next.
Gather the records that give a new planning conversation a clear starting point:
- Plan documents: Save your current financial plan, recent planning summaries, and notes on goals or assumptions that informed past decisions.
- Account statements: Collect recent statements for investment and retirement accounts, and note each account’s custodian and registration.
- Beneficiary details: Keep available records of beneficiary designations and identify any accounts where you want to review them.
- Income and transactions: List scheduled withdrawals, recurring contributions, and upcoming distributions, including the dates and accounts involved.
- Upcoming decisions: Flag deadlines, planned purchases, retirement milestones, or other financial choices that may require timely attention.
Which planning priorities deserve attention first?
Start with near-term cash-flow needs and dates that may affect your options, such as a scheduled retirement distribution, a tax deadline, or a pending financial decision. Then bring investment, insurance, and estate-planning records together for a cohesive review. Keeping these details in one place helps connect portfolio decisions with income needs and broader priorities, rather than treating each account in isolation.
Ending the advisory relationship isn’t itself an instruction to liquidate investments or change your portfolio. Don’t assume existing investment instructions, recurring transactions, or account access will change automatically. Coordinate account access and any investment instructions with the custodian that holds the assets, and make sure you understand which arrangements remain active during the transition.
How can a fiduciary planning relationship support the next phase?
As you consider what comes next, look for a planning approach that reflects your goals and risk tolerance while keeping connected decisions in view. Personalized wealth management can bring investment portfolio management and retirement income planning into the same discussion. That coordination may also involve tax advising and estate and legacy planning, since a decision in one area can affect questions you’re considering in another. These capabilities support an integrated review without promising a particular result.
Timothy Roberts & Associates, LLC brings retirement income, investment, tax, and legacy considerations into personalized wealth management. Explore a thoughtful approach to retirement and wealth planning as you decide how to fire your financial advisor gracefully and preserve continuity in the plan you’re building.
Make Your Next Financial Chapter Deliberate
Choosing how to fire your financial advisor gracefully is ultimately about making a thoughtful decision for the future, not simply closing a chapter. Give yourself time to consider what you want your financial life to support next and what kind of guidance could help you pursue those priorities with clarity.
If you’re looking for a planning partner for that next phase, Timothy Roberts & Associates, LLC brings more than 25 years of experience to personalized strategies shaped around clients’ goals and risk tolerance. Its fiduciary advisors can help connect investment and retirement decisions with the broader direction of your financial plan.
Explore a thoughtful approach to retirement and wealth planning and consider what a more coordinated path could look like for you. A well-chosen next step can turn a transition into an opportunity to move forward with greater purpose and confidence.
Frequently Asked Questions
Can I fire my financial advisor without giving a reason?
Generally, you can end an advisory relationship without providing a detailed explanation, but follow the notice and termination terms in your signed agreement. If you’re deciding how to fire your financial advisor gracefully, a brief statement that you’ve chosen to end the relationship is enough to communicate your decision. You may share feedback if you wish, but you don’t need to debate your reasons. Keep a copy of your written notice.
Can I fire my financial advisor and keep my investments?
Often, yes. Ending advisory services doesn’t automatically require you to sell investments or close accounts. Whether specific holdings can move to another institution without being sold depends on the asset, account type, and receiving custodian. Some holdings may need separate handling. Before authorizing a sale or transfer, identify which assets are involved and ask the relevant custodian how they can be held or moved.
How long does it take to transfer investments to a new advisor?
Most brokerage transfers through the Automated Customer Account Transfer Service (ACATS) take about 5 to 7 business days, while partial transfers may take around 3 to 5 business days. The full process can take a few weeks if it includes paperwork, asset settlement, or holdings that need extra handling. These are general estimates, not a guaranteed schedule. Confirm transfer status with the institutions involved, especially if a transaction date is approaching.
Will firing my financial advisor trigger taxes?
Ending the advisory relationship alone doesn’t necessarily create a taxable event. Taxes may become relevant if investments are sold, since the consequences depend on the account and the asset. A transfer that keeps investments intact may be treated differently from selling them, so don’t assume every transfer has the same tax impact. Before authorizing sales, review the potential consequences with a tax professional who can consider your specific holdings and circumstances.
Can my financial advisor charge me after I terminate the relationship?
Possibly, depending on the agreement’s billing terms and when services end. For example, an agreement may explain how fees are calculated through the termination date or how a previously billed period is handled. Review the final invoice against those terms, and request an explanation of any charge you don’t recognize. Don’t assume that sending notice immediately stops all billing; request written confirmation of the service end date and final billing treatment.
Should I hire a new financial advisor before firing my current one?
It can help, but it isn’t required. Having a new planning relationship in place first may make it easier to coordinate records, account-transfer paperwork, and time-sensitive decisions. Take time to understand the new arrangement and how it fits your priorities before moving assets or sharing instructions. If you haven’t chosen a new advisor, you can end the current relationship and manage the transition deliberately, tracking upcoming distributions and financial deadlines.
