
Sep
SEP IRA vs. Solo 401(k) in 2026: A Strategic Comparison for Michigan Entrepreneurs
The plan with the highest possible contribution isn’t automatically the best fit for your business. In the sep ira vs solo 401k decision, the key questions are how you earn income, whether you want to make employee deferrals, and how much plan administration you’re prepared to handle.
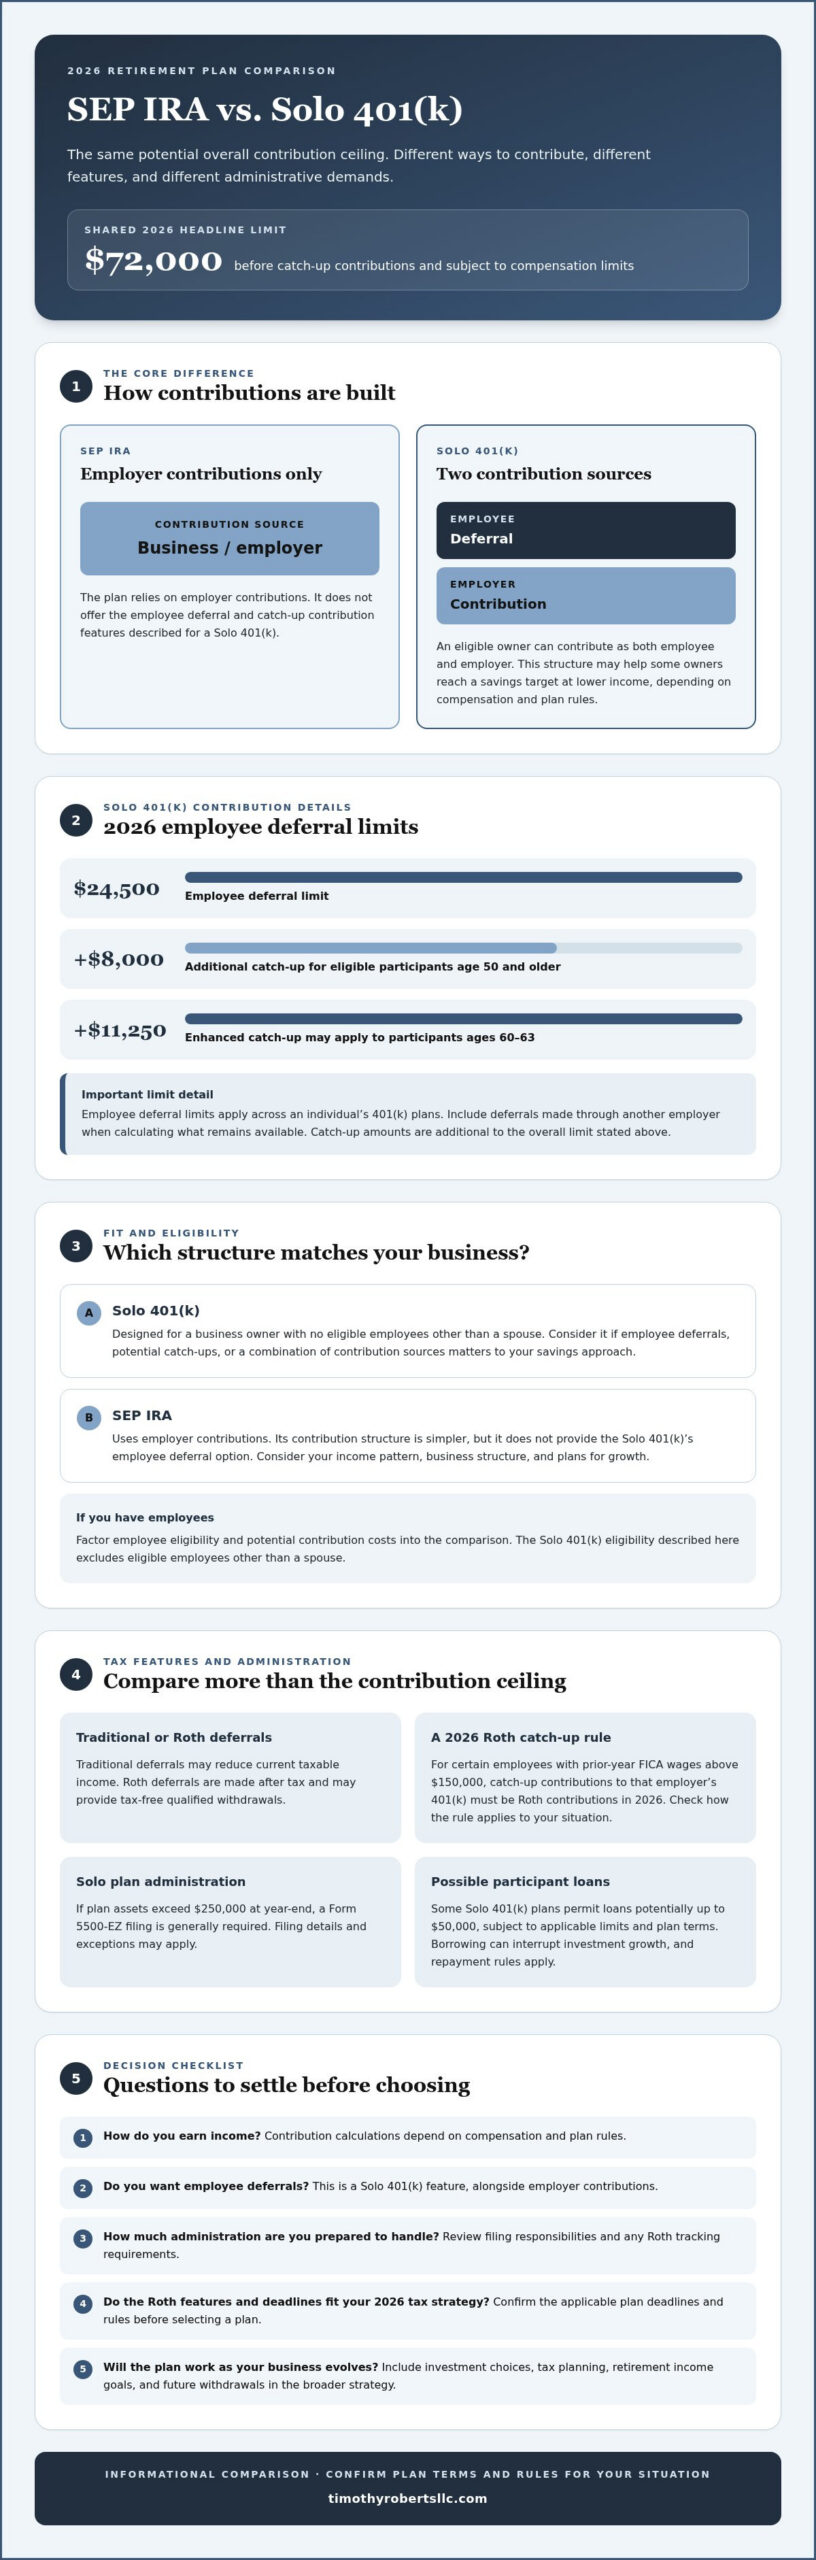
Both plans can allow total contributions of up to $72,000 in 2026, before catch-up contributions and subject to compensation limits. But they reach that ceiling differently: a SEP IRA uses employer contributions, while a Solo 401(k) can combine employee deferrals with employer contributions. The headline limit is only a starting point.
This guide compares contribution rules, Roth features, deadlines, and ongoing responsibilities. Use it to assess which plan fits your income, business structure, and retirement goals, and what to confirm before setting one up.
Key Takeaways
- Compare how each plan reaches the 2026 overall contribution limit of $72,000: a Solo 401(k) combines employee and employer contributions, while a SEP IRA relies on employer contributions.
- For eligible savers age 50 or older, a Solo 401(k) may allow catch-up contributions, an option a SEP IRA doesn’t offer.
- Use the sep ira vs solo 401k michigan comparison to weigh contribution potential against setup, administration, and your business structure.
- Check how Roth features and contribution deadlines fit your 2026 tax strategy before selecting a plan.
- Include investment and tax planning in your retirement strategy so the plan can support your goals as your business evolves.
The Self-Employed Retirement Landscape: Why Your Choice Matters in 2026
For self-employed people saving for retirement, the SEP IRA and Solo 401(k) are two common options. A SEP IRA is funded by employer contributions. An eligible business owner can contribute to a Solo 401(k) as both employee and employer. That difference affects how contributions are calculated, how they may fit uneven income, and what administration the plan requires.
SECURE 2.0 provisions add considerations for 2026. Eligible savers age 50 and older can make catch-up contributions to a 401(k), with a higher catch-up limit for people ages 60 to 63. Roth treatment may also matter: for certain employees with prior-year FICA wages above $150,000, catch-up contributions to that employer’s 401(k) must be Roth contributions in 2026. Check how these rules apply to your situation.
For a concise visual comparison, watch this overview:
The Strategic Advantage of Self-Employed Plans
Compared with relying only on a traditional or Roth IRA, these business plans can offer more room to save because contributions may include an employer component. Depending on the plan and tax treatment, contributions may also create a business tax deduction while investments grow toward retirement. The potential tax benefit depends on your business structure, income, and contribution choices. Consider current tax savings alongside how withdrawals may be taxed later.
A retirement plan is one part of a broader strategy. Pairing contributions with an investment approach that reflects your goals and risk tolerance can help connect your savings to your financial plan. For an overview of Solo 401(k) features, including plan provisions, consult this reference.
Who Should Be Comparing These Plans?
The sep ira vs solo 401k michigan decision is relevant to solopreneurs, consultants, and independent contractors, as well as business owners whose only employee is a spouse. If you have employees, factor their eligibility and potential contribution costs into the comparison. Consider not only how much you can contribute, but also how the plan may affect future retirement income and withdrawals.
Compare contribution potential and simplicity with your current business structure and plans for growth. The right fit should work with your tax strategy today and leave room for your retirement needs to change over time.
The Solo 401(k): Maximum Velocity for Strategic Savers
A Solo 401(k) is designed for a business owner with no eligible employees other than a spouse. Its two-part contribution structure lets the owner contribute as an employee and make an additional employer contribution through the business. This can help some entrepreneurs save more, particularly when they want to direct a substantial share of their earnings toward retirement.
For 2026, the employee deferral limit is $24,500. Participants age 50 and older may contribute an additional $8,000, while those ages 60 to 63 may qualify for an enhanced $11,250 catch-up. These limits apply across an individual’s 401(k) plans, so include any deferrals made through another employer when calculating the amount available.
The Power of the Employee Deferral
Unlike a SEP IRA, which is funded only by employer contributions, a Solo 401(k) gives the owner an employee deferral as well as an employer contribution. That may allow some business owners to reach a savings target at a lower income, depending on compensation and plan rules. Traditional deferrals may reduce current taxable income. Roth deferrals are made after tax and may provide tax-free qualified withdrawals. The appropriate mix depends on your current tax picture and expectations for retirement.
Some plans also permit participant loans, potentially up to $50,000, subject to applicable limits and plan terms. Treat this as a possible liquidity feature, not a replacement for emergency savings. Borrowing can interrupt investment growth, and repayment rules apply.
Administration and the $250,000 Threshold
Solo plans bring administrative responsibilities. If plan assets exceed $250,000 at year-end, a Form 5500-EZ filing is generally required. Check the official IRS rules for Solo 401(k)s for filing details and exceptions. If the plan permits Roth contributions, those contributions must also be administered and tracked accordingly. Confirm plan features and reporting requirements with the provider before adopting the plan.
A one-participant plan covers a business owner with no eligible employees other than a spouse. Transactions involving plan assets must follow applicable rules to avoid prohibited transaction consequences.
Before choosing between a SEP IRA and Solo 401(k), decide whether the employee deferral and catch-up potential justify the additional administration in your circumstances. A coordinated tax and financial planning review can help you compare contributions with your business structure and long-term priorities.
For a broader perspective on how retirement plans fit within financial planning, explore retirement and tax planning considerations.
The SEP IRA: Elegant Simplicity for Growing Businesses
A SEP IRA can offer a straightforward way to establish a workplace retirement plan. The employer makes contributions and can generally adjust the contribution rate from year to year, including contributing nothing in a lean year. For 2026, contributions are capped at the lesser of 25% of an employee’s compensation or $72,000. A sole proprietor’s calculation uses a different formula based on net earnings from self-employment, so the headline percentage may not be the amount you can contribute.
This flexibility can suit a business with uneven cash flow. The trade-off is that if you have eligible employees, SEP contributions generally must be made for them using the same percentage of compensation as for you. As your team grows, those required contributions can affect the plan’s cost. Review the IRS guidelines for self-employed retirement plans alongside your business structure and employee situation.
The 2026 Landscape for SEP Roth Contributions
SECURE 2.0 made it possible for SEP plans to permit employer contributions designated as Roth contributions, but not every SEP IRA provider offers this feature. Confirm availability, account setup, and tax reporting with the provider before choosing this option. Roth contributions are generally included in taxable income for the year they’re made. Qualified withdrawals can receive different tax treatment from traditional SEP assets.
Roth treatment or a conversion may be part of a broader tax strategy, but neither is automatically beneficial. A conversion from traditional pre-tax assets can create taxable income. Weigh its potential long-term role against the current-year tax impact with a qualified tax professional.
Minimalism in Retirement Administration
A SEP IRA generally avoids the annual Form 5500 filing associated with many employer retirement plans, regardless of account balance. One common setup route is IRS Form 5305-SEP, a model agreement, though it isn’t suitable for every business arrangement. Employers establish SEP IRAs for eligible employees, and contributions are immediately vested, meaning employees own the amounts contributed to their accounts.
Streamlined administration can leave more attention for running the business, but it doesn’t eliminate the need to assess eligibility, contribution amounts, and employee costs. In the sep ira vs solo 401k michigan comparison, a SEP IRA may suit an entrepreneur who values variable employer contributions and lighter administration, provided the employee contribution rules fit the business.
Strategic Comparison: Contribution Limits and Tax Efficiency
For 2026, both a SEP IRA and a Solo 401(k) have a $72,000 overall contribution limit before catch-up contributions, subject to compensation-based limits. The route to that ceiling differs: SEP contributions come from the employer, while a Solo 401(k) can combine employee deferrals and employer contributions. For eligible participants, Solo 401(k) catch-ups can raise the total to $80,000 at age 50 or older, or $83,250 at ages 60 to 63. SEP IRAs don’t allow catch-up contributions.
There isn’t one income level where a Solo 401(k) always comes out ahead. The result depends on your business structure, compensation, and how much an employee deferral adds beyond the employer contribution available under a SEP. Self-employment tax also matters: a sole proprietor’s plan contribution calculation generally uses net earnings after an adjustment for the deductible portion of self-employment tax, not gross business revenue.
The Decision Matrix: Income vs. Contribution
Use income as a starting point, not a verdict. At $100,000, $200,000, or $300,000 of income, calculate eligible plan compensation first. Then compare the SEP employer contribution with the Solo 401(k)’s employee deferral plus employer contribution. A Solo 401(k) may be especially compelling below the income needed to reach the SEP ceiling because its employee deferral can create additional savings capacity. There is no universal $200,000 cutoff: the result depends on the calculation and plan terms.
- $100,000: Check whether the employee deferral adds more potential than the SEP employer contribution alone.
- $200,000: Compare the remaining room under each plan after accounting for compensation and business structure.
- $300,000: Assess whether compensation limits or the overall cap constrain additional contributions, and whether catch-ups apply.
Entity structure changes the calculation. For an S corporation, contributions generally relate to W-2 compensation, not shareholder distributions. Employee deferrals also come from compensation. A sole proprietor uses net earnings calculations instead. Model the plans using your actual figures before deciding.
Tax Diversification: Roth vs. Pre-Tax
Traditional contributions may reduce taxable income now, while Roth contributions are made after tax and can provide tax-free qualified withdrawals. Holding assets with both tax treatments may offer more flexibility in retirement, but the right mix depends on your current and expected future tax situation.
Solo 401(k) plans may offer Roth employee deferrals, while SEP Roth availability depends on provider support. Confirm plan features before opening an account. In 2026, eligible employees whose prior-year FICA wages from an employer exceeded $150,000 must make catch-up contributions to that employer’s 401(k) on a Roth basis. Participants ages 60 to 63 may contribute an enhanced $11,250 catch-up.
Frame the sep ira vs solo 401k michigan choice around future withdrawals as well as current contributions. Retirement income planning connects today’s savings decisions to the income strategy you’ll need later. For a coordinated review of plan contributions and tax efficiency, consider integrated tax and retirement planning.
Beyond the Plan: Integrating Your Retirement Strategy
Choosing a SEP IRA or Solo 401(k) establishes the framework. The investment strategy inside the account, and how it fits your broader financial picture, also shape how the plan may support future goals. Contribution limits matter, along with diversification, investment costs, risk tolerance, and the role each account may play in retirement income.
A fiduciary advisor can help assess investment choices in light of your circumstances and objectives. Self-directed plans give owners control, but a wide range of options can make it difficult to choose or can result in a portfolio that lacks diversification. Ongoing investment portfolio management can bring structure to those decisions and help keep the strategy aligned as your business and priorities evolve. No investment approach can guarantee performance, so focus on a disciplined process rather than promises of returns.
Fiduciary Oversight and Portfolio Management
Plan rules deserve the same attention as investment selection. Prohibited transactions, such as certain dealings between a plan and a disqualified person, can have serious tax consequences. Professional guidance can help you recognize potential issues and understand when to seek specialized tax or legal advice. It doesn’t replace your responsibility to follow plan rules.
For retirees with substantial assets, consider the retirement account alongside other investments and anticipated income needs. A coordinated strategy can assess risk, diversification, and investment costs across the broader portfolio rather than evaluating the plan in isolation.
The Path Forward: Customization Over Off-the-Shelf
Online calculators can provide a starting point, but may not capture details that affect a self-employed owner’s plan choice, including business structure, employee eligibility, tax treatment, and future withdrawal goals. A tailored financial roadmap can bring those moving parts together and connect retirement savings with estate and legacy planning, so you can consider how retirement assets fit into your long-term plans.
The sep ira vs solo 401k michigan decision is about choosing a structure that fits your business and long-term financial priorities. Timothy Roberts & Associates, LLC offers fiduciary wealth management and integrated tax and investment strategy as part of its financial planning services.
As you refine your 2026 strategy, consider reviewing your retirement plan, investments, and tax priorities together. Explore financial planning with Timothy Roberts & Associates, LLC as a next step toward a strategy shaped around your business and personal goals.
Build a Retirement Strategy That Grows With Your Business
The right plan is one that fits how your business earns, saves, and evolves. A SEP IRA offers flexibility through employer contributions, while a Solo 401(k) can add employee deferrals and catch-up opportunities for eligible participants. Compare contribution potential with administrative needs, tax treatment, and the investment approach behind the account.
The sep ira vs solo 401k michigan decision also goes beyond this year’s tax bill. Consider how contributions may support future retirement income, how account investments fit your broader portfolio, and how the plan connects with your long-term priorities. A well-chosen structure can become part of a financial roadmap rather than a decision made in isolation.
Timothy Roberts & Associates provides fiduciary guidance and integrated wealth and tax planning. Its financial planning services can help connect retirement choices with your business and personal goals.
Request a Strategic Retirement Planning Consultation to discuss your retirement, investment, and tax planning priorities.
Frequently Asked Questions
Can I have both a SEP IRA and a Solo 401(k) at the same time?
Yes, you may be able to maintain both, but you need to coordinate the plans’ contribution limits and eligibility rules. Employee salary deferrals to 401(k) plans share an annual limit across plans. If the same business sponsors multiple plans, other combined contribution limits may also apply. Your business structure, employees, and whether the plans are sponsored by related businesses affect the analysis. Review the full arrangement with a tax professional.
What is the maximum I can contribute to a Solo 401(k) in 2026?
The 2026 combined employee and employer contribution limit is $72,000, subject to eligible compensation and plan rules. Participants age 50 or older may add an $8,000 catch-up, for a potential total of $80,000. Those ages 60 to 63 may qualify for an enhanced $11,250 catch-up, bringing the potential total to $83,250. Employee deferrals are capped at $24,500 and count toward the overall limit.
Does a SEP IRA offer a Roth option for Michigan business owners in 2026?
A SEP plan may permit employer contributions designated as Roth contributions under SECURE 2.0, but availability depends on the provider and plan setup. Confirm that your custodian supports the feature and ask how contributions will be reported for tax purposes. SEP IRAs don’t allow employee salary deferrals, so this Roth feature works differently from Roth deferrals through a Solo 401(k).
What happens to my Solo 401(k) if I hire a full-time employee?
Hiring an employee may mean your plan can no longer operate as a one-participant 401(k). Whether the employee must be included depends on eligibility rules and the plan’s terms. Full-time status alone doesn’t answer every coverage question. You may need to update plan administration and include eligible employees. Review the plan before hiring, since eligibility and participation can create new responsibilities for the business.
Are catch-up contributions available for both SEP IRAs and Solo 401(k)s?
No. SEP IRAs don’t allow catch-up contributions. A Solo 401(k) may allow them for eligible participants age 50 or older. In 2026, the standard catch-up limit is $8,000, while participants ages 60 to 63 may qualify for an enhanced $11,250 catch-up. These amounts are in addition to the regular employee deferral limit, but remain subject to plan rules and applicable contribution limits.
Which plan is better if I have a side hustle but also a 401(k) at my day job?
It depends on your side-business earnings, existing employee deferrals, and business structure. The $24,500 employee deferral limit for 2026 applies across your 401(k) plans, so contributions at your day job reduce the amount available for employee deferrals to a Solo 401(k). Employer contributions may be calculated separately under applicable rules. A SEP IRA has no employee deferrals, but may allow employer contributions based on eligible business income.
How do I report my SEP IRA contributions on my 2026 tax return?
Reporting depends on your business structure and whether contributions are for you or eligible employees. A self-employed person generally reports their own deductible SEP contribution separately from business income, while a corporation generally deducts employer contributions on its business return. Don’t report a contribution as an employee salary deferral. Keep contribution records and confirm the correct forms and treatment with a tax professional when preparing your 2026 return.
Can my spouse participate in my Solo 401(k) even if they aren’t an owner?
Yes. A spouse who works in the business and receives eligible compensation may generally participate without an ownership stake. Their employee deferrals are subject to the applicable annual limits, and any employer contribution must follow the plan’s terms and compensation rules. Keep records supporting the spouse’s work and compensation, and check the plan document and provider requirements before making contributions.
