
Oct
How to Protect Assets from Economic Uncertainty: A 2026 Guide
What if the greatest risk to your wealth isn’t a market downturn, but a plan that leaves too much exposed in one place? If you’re wondering how to protect assets from economic uncertainty, it’s understandable to feel pulled between concerns about inflation, investment losses, and access to your savings. Before making a quick change, take stock of what you own, what you owe, and when you may need your money.
Resilience doesn’t come from one investment or a single defensive move. It comes from coordinating liquidity, diversification, insurance, taxes, retirement income, and estate goals around your priorities and tolerance for risk. That helps you consider how a decision in one area may affect the rest of your financial picture.
This 2026 guide explains how to identify financial vulnerabilities before making changes, compare common approaches, and decide which risks may deserve attention first. The goal isn’t to eliminate uncertainty, but to build a practical plan you can revisit as your circumstances and the economy evolve.
Key Takeaways
- Learn how to protect assets from economic uncertainty by assessing your full financial picture before making changes.
- Understand how cash reserves, diversified investments, insurance, tax planning, and estate coordination serve different purposes and have different limits.
- Use a practical checklist to review account concentration, cash access, debts, beneficiaries, and income plans.
- Prioritize next steps by urgency, potential impact, reversibility, and whether professional guidance may be useful.
- Build a repeatable process for documenting decisions and reviewing your plan as your goals and circumstances change.
How economic uncertainty can put different parts of your financial life at risk
Economic uncertainty describes conditions that can change in ways that affect your finances. It doesn’t mean a downturn is inevitable. Market volatility can lower investment values, and inflation can reduce what cash buys. An income disruption can make regular bills harder to meet. Interest-rate changes may affect borrowing costs and savings returns, while unexpected expenses can strain cash reserves.
Your financial picture may include investments, cash, retirement accounts, property, debts, and insurance that helps manage certain risks. These pieces are connected. Financial resilience is the ability to adapt to disruption while keeping important goals in view, without assuming any asset is risk-free. The principles of financial risk management offer a foundation for recognizing and assessing different exposures.
For a related perspective on changing conditions in the housing market, watch this video:
Which financial risks should households identify first?
Start by separating near-term cash-flow needs from long-term investment goals. List upcoming bills and planned expenses, then identify which accounts are available to cover them. Money needed soon has a different purpose and time horizon from retirement savings. Next, look for concentrated holdings, debt payments that could become difficult, reliance on one source of income, insurance gaps, and estate plans that may no longer reflect your wishes.
Risks can compound. An income interruption, for example, may lead someone to draw from investments during a market decline, while ongoing debt payments leave less room to adjust. Reviewing each issue on its own can miss how one disruption affects the whole plan.
Does protecting assets mean avoiding every investment risk?
No. Risk can’t be removed without trade-offs. Keeping everything in cash may provide access and a steadier stated balance, but inflation can erode its purchasing power over time. Investments carry different risks and may fluctuate. Choices should reflect what the money is for, when you may need it, and your tolerance for loss.
Understanding how to protect assets from economic uncertainty means preparing for plausible disruptions, not predicting every outcome. Identify vulnerabilities and make deliberate choices, while recognizing that every approach has limits. A coordinated review can connect investment decisions with income needs, insurance analysis, tax considerations, and estate goals.
How to protect assets from economic uncertainty with a coordinated plan
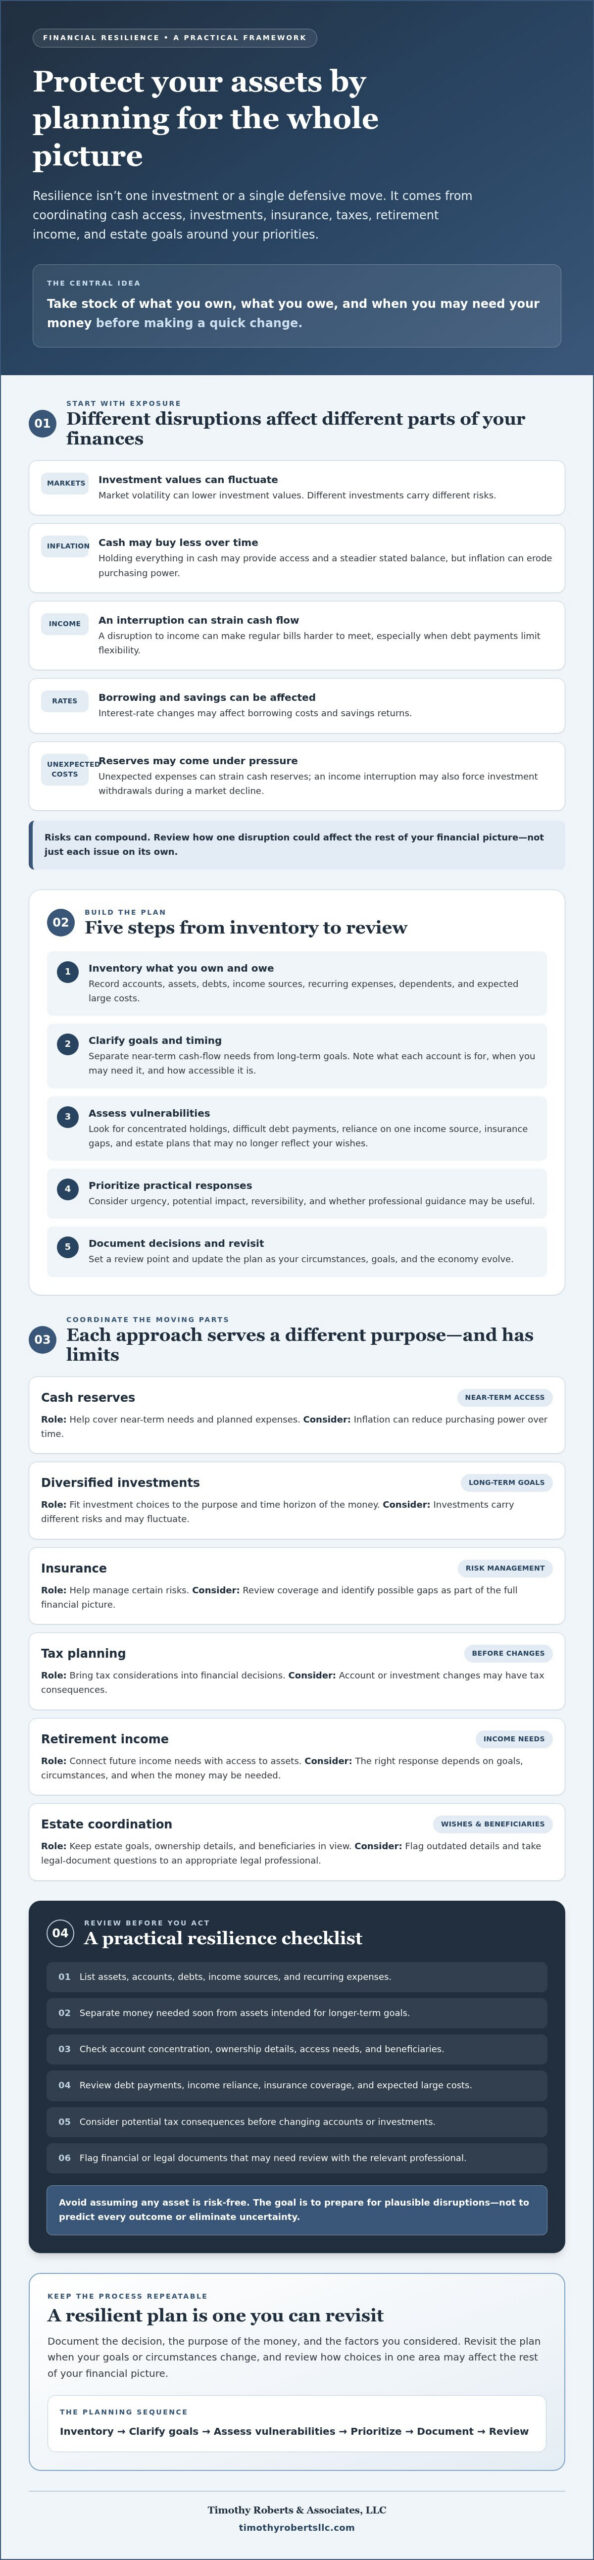
A sound plan starts with a clear picture, not a sudden portfolio change. To decide how to protect assets from economic uncertainty, work through a sequence: inventory what you own and owe, clarify your goals, assess vulnerabilities, prioritize practical responses, and set a date to review the plan.
For each account, record its ownership, purpose, access needs, and time horizon. List major obligations, including recurring expenses, debt payments, education costs, and planned purchases. This helps distinguish money you may need soon from assets intended for longer-term goals. Before changing accounts or investments, consider potential tax consequences, insurance coverage, and beneficiary designations. Take questions about legal documents to an appropriate legal professional.
How should you organize an asset and obligation inventory?
Group assets by type and purpose: cash accounts for near-term needs, retirement accounts for future income, investments for long-term goals, and property or other significant holdings. List debts, income sources, dependents, recurring expenses, and expected large costs. Flag accounts with outdated ownership details or beneficiaries. Note any documents that may need review with the relevant financial or legal professional.
Then clarify what matters most. A household nearing retirement may prioritize access to income, while someone with a longer time horizon may focus on a strategy suited to long-term goals. The right response depends on the household’s circumstances.
How can diversification and liquidity work together?
Diversification spreads investment exposure across different holdings. It can reduce reliance on any one investment, but it can’t guarantee gains or prevent losses. Cash serves a different role: it can help cover expenses without requiring an investment sale at an inconvenient time. How much liquidity makes sense depends on spending needs, income stability, debt, dependents, and access to other resources. There’s no universal reserve amount or portfolio allocation.
Compare potential approaches by considering their purpose, limitations, costs, and possible tax effects. Comparing asset-protection approaches can help frame questions about strategies such as insurance and estate structures, but suitability depends on individual circumstances. Before acting, consider whether professional input would help you evaluate the trade-offs.
- Prioritize: Address urgent cash-flow or coverage concerns before less immediate changes.
- Coordinate: Consider how a portfolio decision affects retirement income, taxes, insurance, and estate goals.
- Review: Schedule check-ins and revisit the plan when goals, income, or obligations change.
If you’d like to examine how these pieces fit your circumstances, explore personalized financial planning.
Comparing asset-protection approaches: trade-offs, limits, and common misconceptions
No single strategy addresses every financial risk. Cash can support near-term access, diversification can reduce reliance on a narrow set of investments, and insurance may transfer specific risks under defined conditions. Tax planning and estate coordination address different questions. Compare each approach by its purpose, limitations, and the questions you still need to resolve.
| Approach | Purpose | Key limitation | Questions to discuss |
|---|---|---|---|
| Cash reserves | Provide accessible funds for planned needs or disruptions. | Inflation can reduce purchasing power; protections depend on account type, institution, ownership, and applicable limits. | How much access do my obligations and income stability call for? How are accounts titled, and what protections apply? |
| Diversified portfolio | Spread investment exposure rather than depending on a single holding or category. | Market risk remains, and diversification can’t assure a profit or prevent loss. | Does my mix match my goals, time horizon, and tolerance for fluctuations? |
| Insurance review | Transfer certain covered risks according to policy terms. | Exclusions, coverage limits, deductibles, and other terms can leave gaps. | What risks are covered, and where might limits or exclusions matter? |
| Tax planning | Consider how financial decisions may affect tax obligations. | Tax treatment depends on individual circumstances and can change. | Could a sale, withdrawal, or account change have tax consequences? |
| Estate coordination | Align ownership, beneficiaries, and estate intentions. | Account designations and documents may need professional review to reflect current wishes. | Are beneficiaries and ownership details current, and should I consult an estate-planning professional? |
What can diversification, cash, and insurance each address?
Diversification manages concentration exposure, but it does not assure a profit or prevent loss. It concerns how investments are distributed, not how quickly funds can be accessed. Cash may support near-term liquidity, while insurance addresses specified risks only within the policy’s terms. Cash protections aren’t identical across situations, so confirm the relevant account, institution, ownership, and applicable limits before relying on them.
Why can drastic reactions create new risks?
Selling investments after a decline can lock in losses or leave a household out of the market if prices recover. Unplanned withdrawals may disrupt long-term goals, and selling or moving assets can trigger tax consequences. Shifting everything to cash doesn’t guarantee safety either. It may reduce exposure to market swings while increasing inflation risk and, over a long retirement, the possibility that resources won’t keep pace with spending needs.
Before making significant changes, ask what risk a move may reduce and what new risk it could introduce. A measured approach to how to protect assets from economic uncertainty weighs liquidity, time horizon, taxes, insurance terms, and personal goals together rather than treating any one tool as a complete solution.
A practical financial-resilience checklist for uncertain economic conditions
A checklist turns broad concerns into decisions you can evaluate. Gather current statements, policies, account details, and income information. Then mark each issue by urgency, potential impact, reversibility, and whether it calls for professional input. An immediate cash-flow gap, for example, may need attention before a portfolio adjustment that could have tax consequences.
- Cash access: Identify funds available for near-term needs and note any access restrictions.
- Account concentration: Review how assets are spread across accounts and investments, and what role each serves.
- Debts and obligations: List payment commitments, recurring expenses, dependents, and expected large costs.
- Insurance: Check coverage, exclusions, limits, and whether policies still fit your circumstances.
- Beneficiaries: Confirm designations and account ownership details are current; flag estate documents for review with an appropriate legal professional.
- Taxes and income: Note questions about withdrawals, sales, or account changes, and consider how retirement or other income plans would respond to disruption.
Set a recurring review date that fits your circumstances. Revisit sooner after a major change, such as a new job, retirement, inheritance, marriage, divorce, or significant shift in expenses. Keep a short record of decisions and open questions so each review builds on the last.
What should you review before changing your portfolio?
Before adjusting investments, revisit your goals, time horizon, expected withdrawals, and comfort with fluctuations. Compare your current diversification with the purpose of each account: money intended for near-term spending may need a different role from assets invested for long-term goals. Consider tax implications before selling or moving assets. For deeper context, review material on investment portfolio management alongside your own plan rather than reacting to headlines.
When should you seek coordinated professional guidance?
Consider guidance when retirement income, taxes, insurance, or estate questions involve multiple accounts or competing priorities. Ask a prospective advisor about fiduciary responsibilities, the scope of advice, fees, and potential conflicts of interest. Financial advisors can help with financial planning, but they don’t replace attorneys for legal advice or legal documents.
A coordinated review can help you decide which questions to address first and how financial choices connect to your goals. To explore personalized financial planning, consider discussing your priorities, concerns, and existing plans with a financial professional.
Turn asset protection into an ongoing financial planning process
Asset protection works best as a discipline, not a one-time reaction to economic headlines. Revisit the full picture in a clear sequence: assess your finances, prioritize vulnerabilities, coordinate decisions across planning areas, document why you chose a course of action, and review it as circumstances evolve. This process can help keep short-term concerns in perspective without losing sight of long-term goals.
A coordinated review brings investment choices into conversation with retirement income needs, tax considerations, insurance analysis, and estate goals. A change in one area may affect another. For example, a withdrawal strategy can influence both available retirement income and tax questions, while a change in family circumstances may call for reviewing beneficiaries and estate arrangements.
What should a personalized review cover?
Start with your financial goals, time horizon, and tolerance for investment risk. Consider how those factors relate to portfolio decisions and the income you may need in retirement. Identify tax-planning questions before making consequential account changes, and review insurance needs with attention to policy terms and coverage. If your estate arrangements may no longer reflect your wishes, flag them for review with an attorney. Financial planning does not replace legal advice or legal document work.
Timothy Roberts & Associates, LLC provides financial planning that can bring investment portfolio management, retirement income planning, tax advising, risk management and insurance analysis, and estate and legacy planning into a broader discussion. Its fiduciary advisors focus on financial strategies tailored to each client’s goals and risk tolerance. A planning partner can help you examine how these considerations relate to your goals without guaranteeing protection from losses or a particular financial result.
How can you keep the plan relevant as conditions change?
Set regular review points, and revisit the plan sooner after a major life event, income change, or significant financial decision. A retirement date, a change in family responsibilities, or a planned withdrawal may affect priorities. Keep notes on the reasoning behind important choices, the assumptions they depend on, and questions that still need professional input. That record can make it easier to respond thoughtfully rather than changing course because of a headline.
For readers considering how to protect assets from economic uncertainty, the lasting value lies in connecting decisions and revisiting them as life changes. Resilience is an ongoing planning process, not a guaranteed outcome.
Discuss a personalized financial plan with Timothy Roberts & Associates, LLC.
Build a Plan You Can Revisit With Confidence
Protecting wealth through uncertainty isn’t about finding one asset that can’t lose value. It’s about understanding where your finances may be vulnerable, prioritizing the risks that matter most, and coordinating decisions across investments, cash needs, insurance, taxes, retirement income, and estate goals.
That’s the practical answer to how to protect assets from economic uncertainty: make choices suited to your goals and risk tolerance, document why you made them, and revisit your plan when your circumstances change. A coordinated review can help you consider how one decision may affect other parts of your financial life without promising a particular outcome.
Timothy Roberts & Associates, LLC offers financial planning, investment portfolio management, retirement income planning, tax advising, risk management and insurance analysis, and estate and legacy planning. If you’d like to discuss how these considerations fit together for you, discuss a personalized financial plan.
Uncertainty may remain, but a thoughtful process can help you meet it with greater clarity and keep moving toward the future you want to build.
Frequently Asked Questions
Can you completely protect your assets from economic uncertainty?
No. Every financial approach has limitations, and market, inflation, income, and unexpected-expense risks can’t all be eliminated. The practical aim is to identify vulnerabilities and make choices that fit your goals, time horizon, and risk tolerance. Cash may support near-term needs, while diversified investments may spread exposure. A coordinated plan can prepare for different possibilities, but it can’t guarantee that your assets will retain value or avoid loss.
Should I move my investments to cash during economic uncertainty?
Not automatically. Moving investments to cash may reduce exposure to market fluctuations, but selling can lock in losses, create tax consequences, or leave you out of the market if values recover. Cash also has limits, including the potential for inflation to reduce its purchasing power over time. Before acting, consider when you’ll need the money, the purpose of your plan, and whether the change introduces risks that matter more to you.
How can diversification help protect assets?
Diversification spreads investments across different holdings or categories, which can reduce dependence on a single investment or source of returns. It doesn’t assure a profit, prevent losses, or ensure that investments won’t decline together. To assess whether your portfolio is diversified in a meaningful way, look beyond the number of accounts or holdings. Consider what each owns, how those investments may relate, and how the mix fits your goals and time horizon.
Is cash safer than investments during a recession?
Cash can offer easier access and a steadier stated balance than investments whose values fluctuate. But “safer” depends on the risk you’re considering. Cash may lose purchasing power to inflation, while investments can fall in value and may require time to recover. The right balance depends on when you expect to use the money, your income needs, and your tolerance for uncertainty. No option is risk-free in every respect.
What happens if I withdraw retirement savings during a market downturn?
A withdrawal may provide money for current expenses, but it can also reduce the assets available for future growth or income. Selling investments after a decline may make losses permanent rather than allowing time for recovery. Depending on the account and your circumstances, withdrawals may also have tax consequences or other costs. Before taking money out, consider other available resources, your income plan, and the effect on long-term goals.
Does FDIC insurance protect investments if the economy weakens?
No. FDIC insurance applies to eligible deposits at FDIC-insured banks, subject to coverage rules and limits. It doesn’t insure investment products such as stocks, bonds, mutual funds, or exchange-traded funds against market losses. If cash is held through a brokerage account or another arrangement, ask the institution how it’s held and what protections may apply. Check current FDIC guidance for details relevant to your account ownership and deposit structure.
When should I review my financial plan during economic uncertainty?
Review your plan on a regular schedule and after meaningful changes, such as a job transition, retirement, a change in family responsibilities, or a major financial decision. Revisit cash needs, investment goals, income plans, insurance, taxes, and beneficiaries as relevant. The question of how to protect assets from economic uncertainty is best approached as an ongoing review, not a reaction to every headline. Document why you make changes and what you’ll monitor.
