Emotional discipline alone will never conquer market anxiety, but a purpose-built cash-flow architecture will. If you find yourself monitoring morning indices with an uneasy knot in your stomach, you aren’t alone; watching decades of disciplined saving feel vulnerable to an erratic correction is genuinely unsettling. Learning how to overcome fear of stock market crash in retirement isn’t about forcing yourself to feel indifferent. It requires engineering an intentional financial structure where short-term market turbulence simply cannot jeopardize your standard of living.
You likely already recognize that rigid withdrawal rules and fluctuating portfolio balances offer little peace of mind against longevity risks and persistent inflation. In this guide, you’ll discover how to replace that uncertainty with lasting confidence through proactive retirement income planning. We explore the strategic distribution of capital across defensive liquidity and disciplined growth allocations, showing you how to generate a predictable monthly paycheck that lets you fully enjoy life without checking financial headlines.
Key Takeaways
- Understand why transitioning from decades of wealth accumulation to ongoing decumulation triggers anxiety, and reframe market volatility as a structural design challenge rather than an emotional crisis.
- Discover the mechanics behind sequence of returns risk, including how selling depreciated assets during early retirement downturns can cause irreversible capital impairment.
- Learn how to overcome fear of stock market crash in retirement by constructing a multi-bucket income architecture that separates immediate living expenses from long-term growth investments.
- Implement tactical governance tools, such as a formal Investment Policy Statement and dynamic withdrawal guardrails, to preserve cash flow without reacting to cyclical market corrections.
- Explore how partnering with an independent fiduciary wealth management advisor provides tailored distribution strategies and tax planning strategies designed to protect your lifestyle.
Why Market Volatility Triggers Severe Panic in Retirement
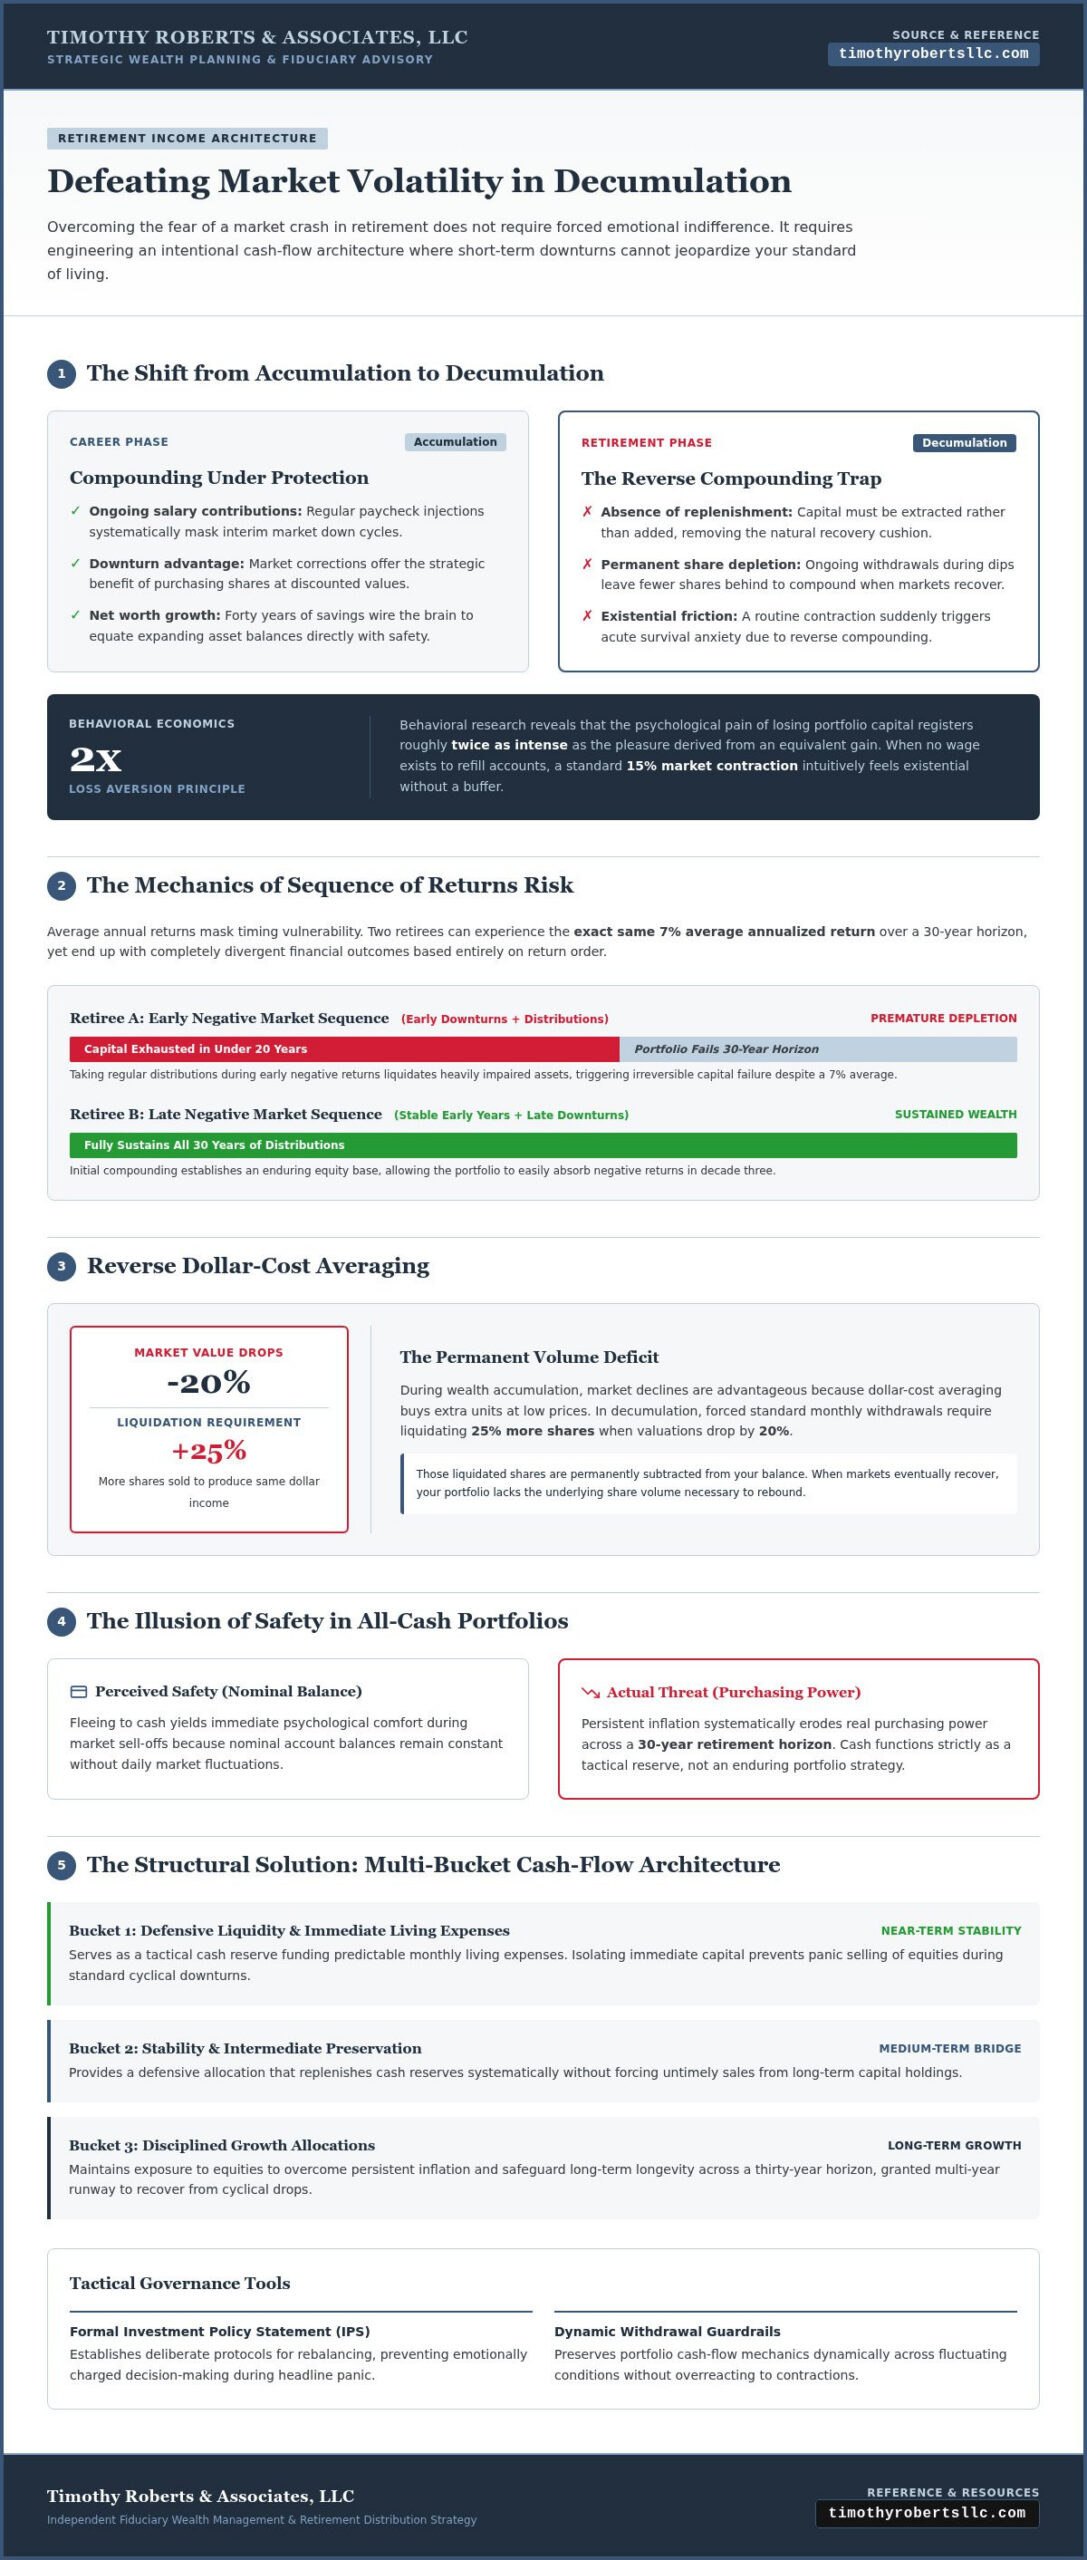
Decades of disciplined saving wire your brain to equate net worth growth with safety. During your career, routine market drops barely registered; each correction simply allowed you to purchase high-grade equities at discounted values. Once the earned paycheck stops, however, that psychology shifts abruptly. A normal 15% market contraction suddenly feels existential when you must draw capital out rather than inject fresh capital in.
This psychological friction is known as decumulation anxiety. Behavioral economists consistently demonstrate the reality of loss aversion, proving that the pain of losing capital feels roughly twice as intense as the joy of equivalent gains. When you no longer have a salary to replenish your balances, watching an account decline triggers survival instincts. Understanding these neurological reactions is the foundational step in learning how to overcome fear of stock market crash in retirement through deliberate design rather than forced emotional stoicism.
To better understand how emotional reactions distort distribution planning during market declines, watch this helpful video:
The Shift from Accumulation to Decumulation
Comprehensive retirement planning demands unlearning forty years of accumulation instincts. During your working life, compounding returns work in your favor because ongoing salary contributions mask down cycles. In decumulation, however, you confront the stark reality of reverse compounding; ongoing distributions taken during market dips leave permanently fewer shares behind to benefit from subsequent recoveries. That structural dynamic explains why market downturns provoke such immediate unease.
The Illusion of Safety in All-Cash Portfolios
Fleeing to cash offers immediate psychological comfort during market sell-offs, but it introduces an insidious alternative threat: purchasing power erosion. Cash feels benign because its nominal balance remains stable, yet cumulative inflation systematically destroys its real value across a thirty-year retirement horizon. True long-term security requires viewing cash as a tactical near-term reserve, never as an all-encompassing strategy for sustained retirement wealth.
Understanding the Mechanics of Sequence of Returns Risk
Market anxiety in retirement rarely stems from irrational worry; it stems from an intuitive grasp of mathematical vulnerability. In traditional wealth accumulation, portfolio volatility matters very little because time smoothes out interim disruptions. A market plunge in year five of retirement, however, carries vastly different mathematical consequences than an identical drop in year twenty-five. Understanding this timing vulnerability is central to mastering how to overcome fear of stock market crash in retirement.
Average annual returns mask this danger completely. Two retirees can experience the exact same 7% average annualized return across a thirty-year retirement horizon. If the first retiree endures negative market performance in their initial years, ongoing distributions can exhaust their capital in less than two decades. Conversely, if negative returns occur later, the portfolio can easily sustain thirty years of distributions. The sequence of returns, not the average return, determines your ultimate financial trajectory.
Reverse Dollar-Cost Averaging Explained
During your career, dollar-cost averaging accelerated your net worth by purchasing more shares when asset prices dropped. Decumulation flips this principle into a destructive cycle known as reverse dollar-cost averaging. When market values drop by 20%, producing your standard monthly withdrawal requires liquidating 25% more shares to generate the identical dollar amount. Those sold shares are permanently removed from your ledger. When the market inevitably recovers, your portfolio lacks the underlying share volume required to rebound, locking in permanent capital impairment.
The Mathematical Fragility Window
The five-year threshold directly flanking your retirement date represents an acute fragility window. Market corrections absorbed during this transition inflict compounding damage on decumulation lifespans, as documented in institutional portfolio distribution research. Mitigating this risk requires eliminating forced asset liquidation. Structuring an insulated liquidity buffer through disciplined retirement income planning with Timothy Roberts & Associates, LLC ensures you never sell depressed assets to fund current living expenses, neutralizing volatility before it impacts your day-to-day lifestyle.
How to Build a Volatility-Resistant Retirement Income Architecture
Generic adages advising investors to “stay the course” fall flat when monthly groceries and property taxes depend entirely on your portfolio. Lasting peace of mind requires engineering a structure where market contractions cannot disrupt your lifestyle. Rather than treating your savings as a single, exposed pool of capital, you can partition your assets into functional tranches. This multi-bucket methodology directly addresses how to overcome fear of stock market crash in retirement by divorcing your daily cash flow from immediate equity performance.
By arranging capital based on when it will be spent, you construct a resilient defense against sequence of returns risk. This architecture establishes three distinct operational tiers:
- Tier 1: Immediate Liquidity provides twelve to twenty-four months of baseline net living expenses.
- Tier 2: Mid-Term Stability holds three to seven years of cash-flow needs in defensive, income-generating instruments.
- Tier 3: Long-Term Growth invests remaining capital in equities to generate essential inflation protection over decades.
Tier 1: Immediate Liquidity and Short-Term Reserves
Liquid reserves eliminate the dread of funding retirement life through falling equity sales. This tier holds one to two years of spending needs not covered by guaranteed income sources like Social Security or pensions. By deploying vehicles such as high-yield savings accounts or money market funds, you capture competitive yields, with top institutions offering rates up to 4.15% APY, while ensuring your near-term grocery and healthcare bills remain entirely detached from market volatility.
Tier 2: The Mid-Term Capital Preservation Shield
Short-term reserves eventually require replenishment, which makes an intermediate bridge indispensable. Tier 2 houses three to seven years of net distributions inside short-duration bonds, Treasury ladders, and high-grade fixed income. If an equity bear market persists for years, this tier quietly funds Tier 1 without touching a single depreciated share. It gives your growth investments the multi-year breathing room required to endure full economic recovery cycles.
Tier 3: Long-Term Growth to Combat Inflation
Surviving a thirty-year retirement requires outpacing cumulative living costs. Tier 3 functions as your compounding growth engine, populated by diversified global equities designed to build long-term purchasing power. Because Tier 1 and Tier 2 provide years of insulated cash flow, you never need to sell these assets during a panic. Instead, you systematically rebalance, harvesting gains during strong bull markets to replenish the defensive tiers below.
Tactical Responses: Navigating Market Corrections Without Selling
Market turbulence invites panic only when you don’t have predefined protocols in place. Improvisation during a sharp downturn almost always produces catastrophic emotional mistakes, primarily liquidating shares at the exact moment valuations hit cyclical lows. By contrast, establishing a written Investment Policy Statement establishes unequivocal rules before volatility arrives. This governance framework dictates precisely when to hold, when to trim, and when to acquire assets. Embracing this level of preparedness illustrates how to overcome fear of stock market crash in retirement through systematic execution rather than emotional willpower.
Liquidating equity positions during a correction locks in theoretical losses and creates a secondary dilemma: knowing when to re-enter. Investors who exit during panic rarely return in time to capture the sharpest rebound days, permanently impairing their capital base. A strategic response replaces defensive retreat with measured, countercyclical action.
Implementing Dynamic Spending Guardrails
Inflexible withdrawal rules introduce unnecessary fragility during prolonged bear markets. Dynamic distribution guardrails offer a far more resilient alternative. Under this model, you establish predetermined parameters to temporarily trim discretionary expenditures, such as luxury travel or delayed capital upgrades, by modest percentages during market contractions. Essential living costs remain fully supported by your liquidity tiers. Once asset valuations rebound to baseline levels, discretionary distributions are immediately restored, protecting your portfolio longevity without sacrificing fundamental comfort.
Strategic Tax-Loss Harvesting and Rebalancing
Severe market contractions present exceptional tactical opportunities for thoughtful investors. Rather than freezing, a disciplined rebalancing protocol trims insulated fixed-income positions to purchase high-grade equities at discounted valuations, accelerating total portfolio recovery when markets turn upward. Concurrently, tax-loss harvesting converts temporary paper losses into immediate deductions that offset future capital gains and ordinary income.
Market dips also provide prime windows to execute partial Roth conversions, transferring assets at temporarily deflated valuations to permanently shield subsequent compound growth from taxation. Partnering with a dedicated firm for investment portfolio management ensures these technical adjustments happen dispassionately, securing your standard of living through deliberate execution.
Partnering With a Fiduciary Advisor to Anchor Your Strategy
Engineering a robust distribution plan is half the battle; maintaining emotional equilibrium through unexpected economic contractions is the other. Even well-crafted portfolios encounter stress when financial headlines reach a fever pitch. Having an objective advisor standing between your wealth and emotional impulses prevents the panic selling that derails decades of disciplined accumulation. Ultimately, discovering how to overcome fear of stock market crash in retirement requires more than static spreadsheets. It demands an experienced fiduciary partner dedicated exclusively to your best interests.
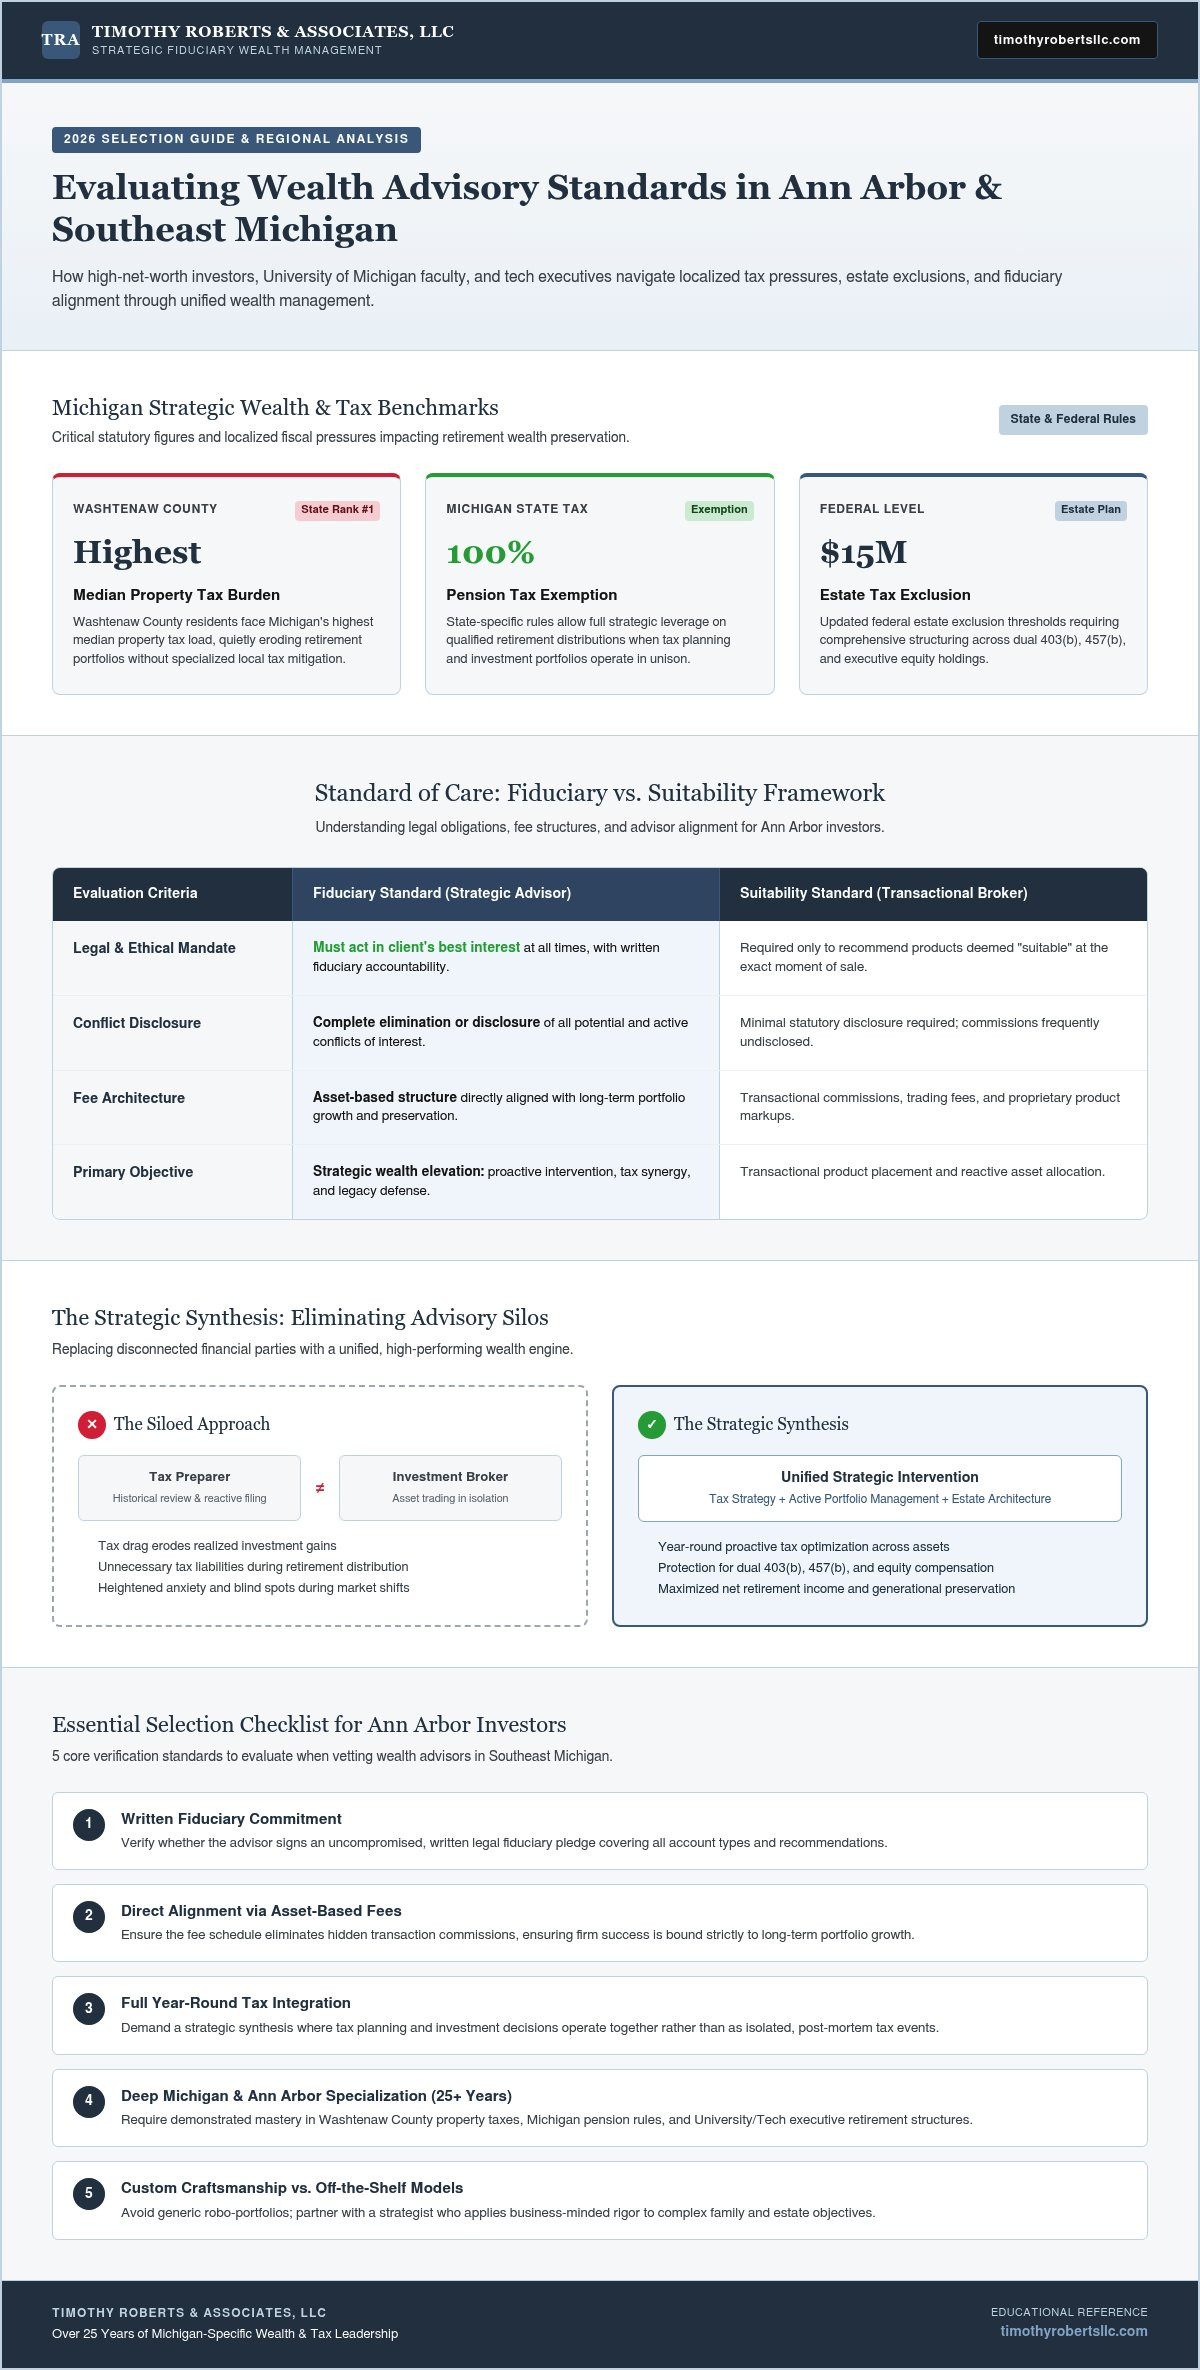
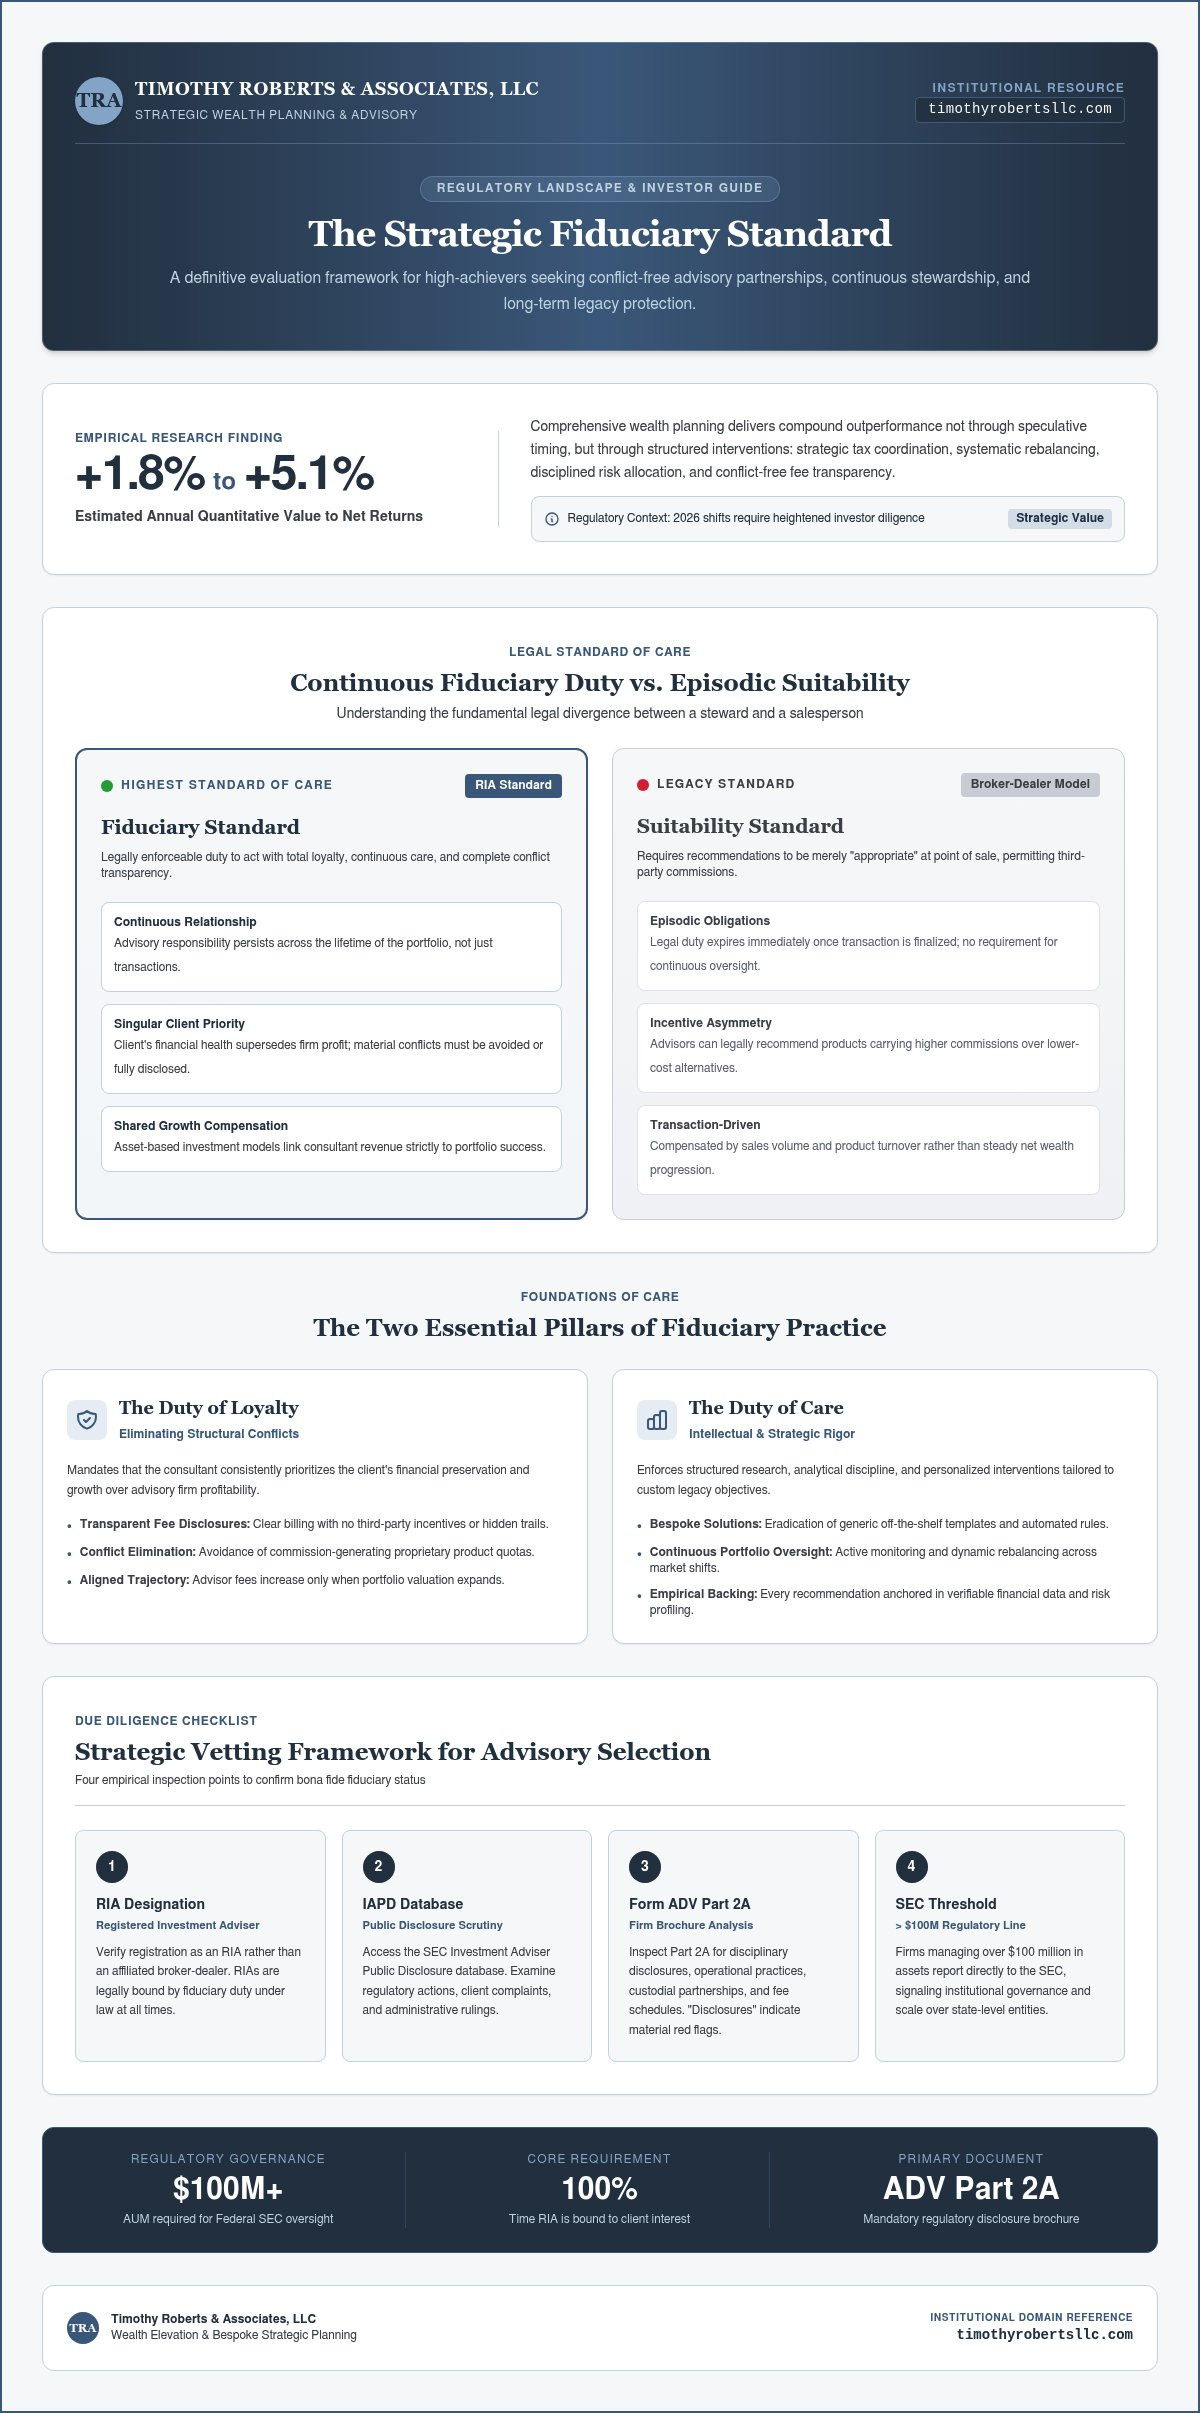
The distinction between a transactional broker and an independent fiduciary becomes critical during down markets. Broker-dealers often operate under a basic suitability threshold, occasionally directing client capital toward proprietary funds or commissioned arrangements that prioritize institutional revenue over individual outcomes. In contrast, an independent fiduciary advisor bears a strict legal duty to put your interests first, tailoring every asset allocation directly to your distinct cash-flow requirements.
The Fiduciary Difference in Decumulation Planning
In decumulation, managing risk extends far beyond picking assets. A dedicated fiduciary coordinates investment portfolio management directly with forward-looking tax planning strategies. They evaluate distribution timing across taxable, tax-deferred, and Roth accounts, optimizing tax efficiency while maintaining your required cash reserves. Rather than relying on standardized models, bespoke planning ensures each tier of your capital structure serves a specific lifestyle milestone, shielding your household while keeping growth assets undisturbed.
Achieving Enduring Peace of Mind
Sustainable peace in retirement comes from tracking plan execution instead of obsessing over daily market swings. Establishing regular review cadences allows you to dynamically adapt to shifting interest rates, tax legislation, and personal priorities without frantic adjustments. With over 25 years of wealth management and retirement planning experience, Timothy Roberts & Associates, LLC builds individualized income architectures designed to withstand any economic season. That structural clarity allows you to stop tracking ticker symbols and start enjoying the financial freedom you spent a lifetime earning.
Transforming Market Volatility into Lasting Financial Freedom
Deciding how to overcome fear of stock market crash in retirement doesn’t mean ignoring economic cycles; it means designing an income architecture where market drawdowns cannot threaten your daily life. When you intentionally separate near-term living expenses from long-term growth assets, sequence of returns risk ceases to be an existential hazard. Market corrections transform from terrifying disruptions into normal, manageable phases of a well-engineered financial plan.
True confidence emerges when your distribution roadmap, portfolio structure, and forward-looking tax planning strategies work in complete alignment. Backed by over 25 years of specialized retirement planning and wealth management experience, Timothy Roberts & Associates, LLC upholds an uncompromised fiduciary standard dedicated solely to client success. Take the next step toward securing your future and schedule a retirement income consultation with Timothy Roberts & Associates, LLC today. With the right architecture beneath you, you can stop watching the market and start fully enjoying the retirement you earned.
Frequently Asked Questions
How much cash should a retiree hold to avoid selling stocks during a crash?
A retiree should generally maintain twelve to twenty-four months of essential living expenses in cash or cash equivalents, net of guaranteed income like Social Security. This operational reserve ensures you don’t have to liquidate equities at deflated valuations during a market downturn. Pair this with a secondary stability tier of high-quality fixed income to give equities several years to recover without endangering your monthly cash flow.
What is sequence of returns risk and why is it dangerous in retirement?
Sequence of returns risk is the danger that market drawdowns occur during the initial years of your decumulation phase. When you withdraw capital from a declining portfolio, you lock in permanent share losses through reverse dollar-cost averaging. Even if long-term average returns look healthy, an early sequence of negative returns can exhaust your savings decades ahead of schedule, leaving too few assets behind to compound.
Can I safely leave my retirement portfolio in a 60/40 asset allocation?
A static 60/40 balanced portfolio provides general diversification, but it lacks the dedicated cash-flow insulation required for decumulation. When both equities and fixed-income assets decline simultaneously, a traditional 60/40 structure still forces you to sell assets at a loss to generate monthly income. Structuring a multi-tiered bucket strategy provides superior protection by dedicating specific reserves exclusively to near-term liquidity and intermediate living expenses.
What are dynamic spending guardrails and how do they protect savings?
Dynamic spending guardrails are predetermined rules that adjust your annual withdrawals based on prevailing market performance. Instead of taking an inflexible distribution, you trim non-essential discretionary expenses by a modest margin during market downturns. Understanding these tactical adjustments is vital when exploring how to overcome fear of stock market crash in retirement, as it lets you protect baseline living standards while keeping core portfolio capital intact.
How does a market crash impact required minimum distributions (RMDs)?
Required minimum distributions are calculated using your account balance from December 31 of the previous year. If the stock market crashes in the current year, your statutory withdrawal dollar amount remains tied to that prior, higher balance. This forces you to withdraw a larger percentage of your depressed assets. Proactive distribution planning and targeted tax planning strategies can help coordinate distributions across various account types to minimize this strain.
Is it ever advisable to move my retirement investments to cash during a downturn?
Liquidating long-term investments into cash during a downturn is almost never advisable because it crystallizes paper losses into permanent capital destruction. Shifting entirely to cash introduces dual timing risks: selling near market bottoms and missing the subsequent recovery. A disciplined approach to how to overcome fear of stock market crash in retirement relies on an established liquidity reserve, allowing long-term equity allocations to remain invested throughout cyclical turbulence.
How do fiduciary advisors help retirees manage severe stock market volatility?
Independent fiduciary advisors act as an objective behavioral buffer, preventing catastrophic emotional decisions during market sell-offs. Because fiduciaries are legally bound to serve your best interests, they construct customized distribution architectures rather than selling generic products. By integrating ongoing investment portfolio management with proactive tax advising, a fiduciary ensures your portfolio systematically generates monthly income while maintaining defensive reserves that withstand broad economic declines.